Why Mortgage Escrow Shortages Raise Your Monthly Payment
A mortgage escrow shortage can increase your monthly payment even when the loan rate is fixed. Learn how escrow analyses work, why shortages occur and how to check the servicer's calculation.
What you’ll need
Tap to tick things off before you start.
1. Unexpected Mortgage Payment Changes
Many homeowners face unexpected changes to their monthly mortgage payment when their lender identifies an imbalance in their escrow account. This common situation occurs because property taxes and insurance premiums fluctuate from year to year, directly impacting the total amount you must pay each month, which includes the funds allocated to your escrow account.
2. Managing Your Escrow Account
In this episode, we will examine how these accounts work, why shortages occur, and what options you have to manage your monthly payments.
3. What Is Escrow?
What is a Mortgage Escrow Account? An escrow account, sometimes called an impound account, is a specialized financial account set up and managed by your mortgage lender. Its primary purpose is to pay certain property-related expenses on your behalf, specifically your property taxes and homeowner's insurance premiums.
4. Securing Your Home Payments
When you purchase a home, these ongoing expenses are crucial, and lenders want to ensure they are paid reliably. To facilitate this, a portion of your monthly mortgage payment goes directly into this escrow account.
5. Managing Large Bills Easily
This system helps homeowners manage large, significant bills. Instead of paying a massive property tax bill or a large insurance premium once or twice a year, you send smaller, more manageable amounts to your lender each month as part of your regular payment.
6. Lender Handles the Payments
The lender holds these funds and, when bills become due, pays them directly to the tax authority and the insurance company. This arrangement provides a structured way to budget for these inevitable expenses, spreading the financial impact evenly across the entire year.
7. Avoiding Sudden Financial Strain
By breaking down annual costs into twelve equal monthly installments, homeowners can avoid the sudden financial strain of paying thousands of dollars all at once. It simplifies homeownership by consolidating multiple property-related bills into a single, predictable monthly transaction.
8. No More Missed Deadlines
This means you do not have to worry about saving separately for these large bills or missing their due dates, as the lender handles the administration. However, because these bills are based on estimates, the amount needed in the account can change.
9. Peace of Mind for Homeowners
This system offers peace of mind, knowing these critical property expenses are handled systematically, and protects the lender's interest by ensuring taxes are paid and insurance coverage remains active.
10. The Annual Escrow Analysis
The Annual Escrow Analysis To ensure your escrow account has the correct amount of money, your mortgage lender typically conducts an annual escrow analysis. This yearly review examines the financial health of your account.
11. Reviewing Past Expenditures
During this analysis, the lender looks at the actual property taxes and insurance premiums paid out over the past year. They compare these expenditures with your monthly escrow payments during that period.
12. Projecting Future Costs
Additionally, the lender projects the estimated costs of your taxes and insurance for the upcoming year. Based on this detailed comparison and projection, the lender determines whether your escrow account has a shortage, a surplus, or a deficiency.
13. Surplus Versus Deficiency
A surplus occurs when more money was collected than actual bills paid, which may result in a refund. A deficiency occurs when the account balance falls below the minimum cushion required by the lender or regulations.
14. Understanding Escrow Shortages
A shortage, a common scenario, occurs when there is not enough money in the escrow account to cover the bills the lender paid on your behalf.
15. Why Monthly Payments Change
This annual analysis is the primary reason your total monthly mortgage payment can change from year to year, even with a fixed-rate mortgage where the principal and interest portion remains unchanged.
16. Maintaining Long Term Stability
The analysis ensures the account is adjusted so future bills can be paid on time without depleting the account entirely. It is a necessary adjustment to keep your account properly funded, reflecting the real costs of property ownership and helping maintain the stability of your mortgage payment over the long term.
17. Why Shortages Happen
Why Escrow Shortages Happen An escrow shortage is directly tied to changes in the underlying costs of owning your home. Property taxes and insurance premiums can change from year to year, and when they do, your escrow payment and total monthly mortgage payment will change accordingly.
18. Rising Property Taxes
Property taxes are determined by local government municipalities and counties. These taxes can increase for several reasons, such as a reassessment of your home's market value or an increase in local tax rates to fund public services, schools, or infrastructure improvements.
19. Assessed Value Increases
For example, if your home's assessed value increases, your property tax bill will likely rise, even if the tax rate remains the same. When your local government raises your property taxes, the bill sent to your mortgage lender is higher than what was originally estimated.
20. Changing Insurance Premiums
Similarly, homeowner's insurance premiums are subject to change. Insurance companies adjust their rates based on factors like inflation, rising construction and repair costs, or changes in the risk profile of your geographic area.
21. Weather and Insurance Rates
For instance, an increase in severe weather events in your region could lead to higher premiums for all homeowners. If your insurance company raises your annual premium, that bill also increases.
22. Higher Than Expected Bills
Because your lender pays these bills on your behalf as they become due, they use the funds available in your escrow account. If the actual bills for your taxes and insurance turn out to be higher than the estimates used to calculate your monthly payments, the escrow account will experience a shortage.
23. Resolving the Deficit
The money you contributed throughout the year was simply not enough to cover the actual expenses paid by the lender. This means the lender has essentially advanced funds to cover your bills, creating a deficit that must be resolved. These increases are often outside of a homeowner's direct control, making the annual escrow analysis a critical point of adjustment.
24. Two Options for Shortages
Addressing an Escrow Shortage When an escrow shortage is identified during the annual analysis, your lender will notify you and outline the steps required to resolve the imbalance. Homeowners typically have two primary options to address an escrow shortage and bring their account back into balance.
25. Option One: Lump Sum Payment
The first option is to pay the shortage in a lump sum. If you choose this path, you make a one-time payment to your lender for the entire amount of the shortage. This immediate payment covers the deficit from the previous year.
26. Clearing the Past Deficit
By paying the shortage upfront, you prevent that specific deficit from being added to your future monthly payments. However, keep in mind that your monthly mortgage payment may still increase slightly to cover the higher projected tax and insurance costs for the upcoming year, even if the past shortage is cleared.
27. Option Two: Twelve Month Spread
The second option is to spread the shortage payment out over a twelve-month period. If you select this option, the lender will divide the total shortage amount by twelve and add that portion to your monthly mortgage payment for the next year.
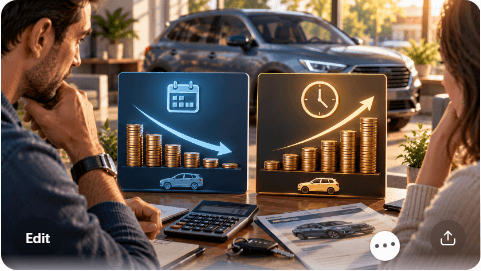
28. Managing Your Cash Flow
This option avoids the need for an immediate, large lump-sum payment, making it easier on your short-term cash flow. However, it means your total monthly mortgage payment will increase for the next twelve months, as you will be paying both the higher ongoing escrow estimate and the monthly portion of the past shortage.
29. Example Shortage Breakdown
For example, if your shortage is 1,200 dollars, choosing the 12-month option would add 100 dollars to your monthly payment for the next year, in addition to any increase from higher future estimates.
30. Choosing the Best Option
Understanding these options allows you to choose the method that best fits your household budget and financial goals, helping you avoid sudden payment shock. It is important to consider your current financial situation and cash flow when making this decision.
Many homeowners face unexpected changes to their monthly mortgage payment when their lender identifies an imbalance in their escrow account. This common situation occurs because property taxes and insurance premiums fluctuate from year to year, directly impacting the total amount you must pay each month, which includes the funds allocated to your escrow account. In this episode, we will examine how these accounts work, why shortages occur, and what options you have to manage your monthly payments. ### What is a Mortgage Escrow Account? An escrow account, sometimes called an impound account, is a specialized financial account set up and managed by your mortgage lender. Its primary purpose is to pay certain property-related expenses on your behalf, specifically your property taxes and homeowner's insurance premiums. When you purchase a home, these ongoing expenses are crucial, and lenders want to ensure they are paid reliably. To facilitate this, a portion of your monthly mortgage payment goes directly into this escrow account.
This guide turns the mechanics from the video into a document you can review at your own pace. It is general educational information, not individualized financial, legal, tax or credit advice. Verify account-specific details with the relevant lender, servicer, credit bureau or qualified professional.
Where people go wrong
Assuming a fixed rate means a fixed total payment. Principal and interest may stay fixed while taxes, insurance and escrow requirements change.
Reading only the new payment amount. Review the projected disbursements, shortage amount, cushion and calculation period.
Ignoring an insurance increase. A higher premium can create both a past shortage and a higher future monthly escrow deposit.
Paying a shortage without checking the analysis. Verify that the servicer used the correct tax bills, insurance premium and account history.
Sending tax or insurance documents to an unverified contact. Use official servicer channels and protect account numbers and personal information.
Waiting until the account becomes delinquent. Contact the servicer promptly if the new payment is unaffordable or the analysis appears wrong.
Questions people ask
A shortage occurs when the escrow account contains less than the servicer projects it needs to pay taxes, insurance and any permitted cushion.
Fixed it?
Get one guide like this every Thursday.