The Life of a Charge-Off Debt: What Happens After a Creditor Writes Off Your Balance
A charge-off does not mean your debt disappears. Learn what happens after a creditor writes off an account, how long it can affect your credit, when collectors can sue, and how canceled debt may affect your taxes.
What you’ll need
Tap to tick things off before you start.
What Happens to a Debt After a Charge-Off?
A charge-off happens when a creditor classifies a seriously overdue debt as a loss rather than an account expected to produce normal payments. However, the balance does not automatically disappear. The consumer generally remains responsible for the unpaid amount, and the account may enter another stage of debt recovery. Understanding what happens to charge-off debt requires separating the creditor's internal financial decisions from the borrower's continuing obligations and the possible consequences that follow.
Why Banks Charge Off Unpaid Accounts
Banks charge off unpaid accounts because financial reporting must reflect realistic expectations about recovering outstanding loans. Keeping severely delinquent balances classified as collectible assets could exaggerate a bank's financial strength. Banking regulators therefore establish standards for recognizing credit losses. Charge-offs help institutions maintain accurate records, evaluate lending risks, and communicate financial performance to investors and regulators. This classification is a routine accounting requirement, not a reward for missed payments or a voluntary decision to forgive borrowers.
How a Loan Becomes an Accounting Loss
When a lender issues credit, the amount expected from the borrower becomes a receivable recorded among its financial assets. Initially, the lender anticipates repayment under the agreed schedule. As missed payments accumulate, the likelihood of collecting the full balance may decline. The institution estimates potential credit losses and establishes appropriate allowances. Eventually, amounts considered uncollectible are charged against those allowances, reducing the recorded loan asset. This process recognizes deterioration in the loan's expected financial value.
Charge-Off Versus Debt Forgiveness
A charge-off and debt forgiveness represent different events. A charge-off changes the creditor's accounting treatment without necessarily changing what the borrower owes. Debt forgiveness involves a creditor agreeing to cancel some or all of an enforceable obligation. A negotiated settlement may also resolve a balance when its documented terms are satisfied. Bankruptcy discharge can eliminate personal liability for qualifying debts through a separate legal process. Written agreements and applicable law determine whether an obligation has actually been released.
When Credit Card Accounts Are Charged Off
Many credit card accounts reach charge-off status after approximately 180 days of continuous delinquency. Federal banking guidance generally uses this threshold for open-end retail credit, while many closed-end installment loans follow a 120-day standard. The Federal Deposit Insurance Corporation describes these classifications in its retail credit guidance. Actual timing can vary with account circumstances, regulatory requirements, and earlier loss recognition. Bankruptcy, fraud, and certain secured loans may also involve different accounting treatment or accelerated charge-off decisions.
What Happens to Interest and Late Fees?
Interest and late fees do not necessarily stop when an account is charged off. Whether additional amounts can accrue depends on the original credit agreement, applicable federal and state laws, and any subsequent agreements. Some creditors stop certain charges after closing an account, while others may continue permitted interest. A collector cannot lawfully impose amounts that lack contractual or legal authorization. Consequently, the amount claimed later may differ from the balance originally recorded at charge-off.
How a Charge-Off Affects Your Credit
A charge-off can significantly damage creditworthiness because it indicates an account experienced serious payment problems. Credit reports may show earlier missed payments, the charged-off account status, and an outstanding balance when applicable. Credit scoring models evaluate these details alongside the rest of a consumer's credit history. According to the Consumer Financial Protection Bureau, negative payment information can affect credit scores and borrowing opportunities. Lenders may interpret the entry as evidence of elevated repayment risk.
The Seven-Year Credit Reporting Rule
Under the Fair Credit Reporting Act, a charge-off generally becomes too old to report after approximately seven years. The federal outer limit is seven years plus 180 days from the beginning of the delinquency that immediately preceded the collection or charge-off activity. Credit reporting companies commonly remove these entries around the seven-year mark. The Consumer Financial Protection Bureau explains that most negative account information has a limited reporting period. This restriction prevents adverse credit history from remaining indefinitely.
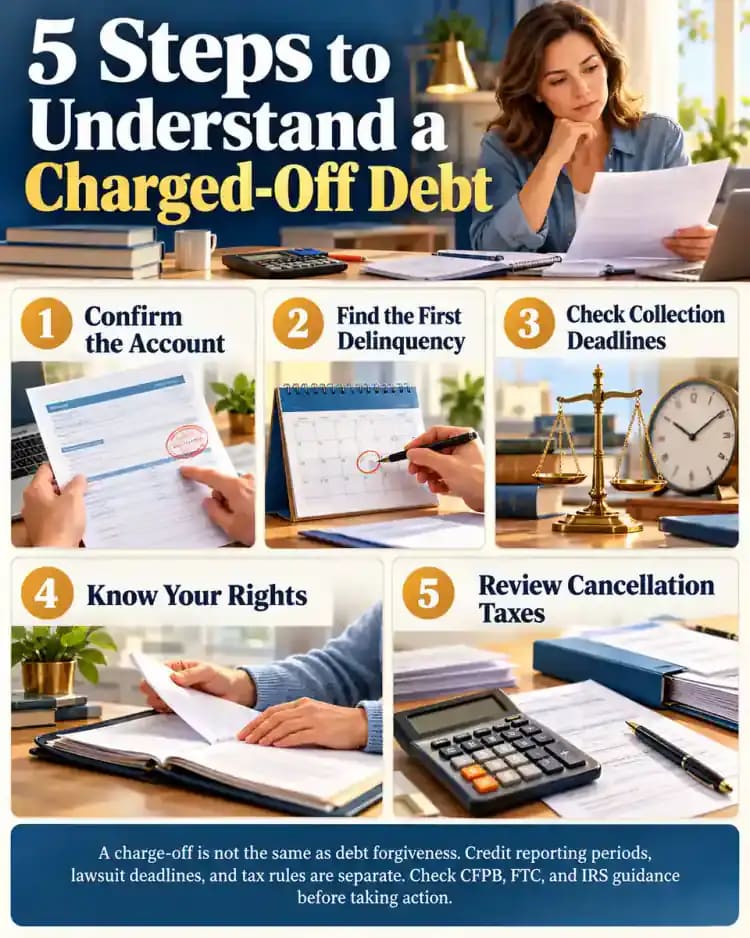
How to Find the First Delinquency Date
The date of first delinquency identifies when the uninterrupted sequence of missed payments leading to a charge-off began. For example, if a payment was missed in January and the account was charged off in July without becoming current, January establishes the relevant starting point. Later charge-off updates do not restart that timeline. Consumers can compare old statements, payment records, and credit reports to identify the month. Inaccurate delinquency dates can be disputed with credit reporting companies.
What Happens When the Credit Entry Ages Off?
When a charge-off ages off a credit report, credit reporting companies generally stop displaying that particular negative entry in ordinary consumer reports. Its disappearance does not independently cancel the underlying obligation. A creditor or collector may still pursue repayment when legally permitted, although state statutes of limitations restrict lawsuits over older debts. The Consumer Financial Protection Bureau emphasizes that collection rights and reporting periods operate under separate rules. Therefore, a cleaner credit report does not necessarily mean the debt is resolved.
How to Check All Three Credit Reports
Start by requesting free credit reports from Equifax, Experian, and TransUnion through AnnualCreditReport.com, the federally authorized website. According to the Consumer Financial Protection Bureau, free online reports are available weekly. Review each report separately because creditors may report information differently across bureaus. Compare account numbers, outstanding balances, payment histories, charge-off statuses, and dates of first delinquency. Look for duplicate entries, unfamiliar accounts, and inconsistent dates. Save copies of all three reports for future reference.
How to Dispute Incorrect Charge-Off Information
If a charge-off contains incorrect information, submit a dispute to the credit bureau reporting the error. Identify the account, explain the mistake, and include supporting documents such as payment confirmations or account statements. The bureau generally has 30 days to investigate, with certain exceptions and extensions, and must communicate its findings. You can also dispute inaccuracies directly with the information provider. Under the Fair Credit Reporting Act, accurate negative information generally cannot be removed simply because it harms your credit.
What Creditors Do With Charged-Off Debt
After charging off an account, a creditor typically chooses among three collection strategies. It may retain ownership and pursue repayment through its internal recovery department. Alternatively, it may hire a third-party collection agency while continuing to own the balance. A third option is selling the account to a debt-buying company, often at a discount. These approaches involve different business arrangements, but an accounting charge-off alone does not forgive the obligation. The chosen strategy can also change over time.
What Happens When a Debt Is Sold?
When a creditor sells charged-off debt, the purchaser generally acquires the creditor's contractual rights to collect the outstanding balance, subject to applicable law. The buyer may purchase individual accounts or large portfolios containing thousands of debts. Ownership can transfer multiple times, making unfamiliar company names common in collection correspondence. Consumers can examine notices for the current creditor's identity and compare those details with previous records. A legitimate ownership transfer does not automatically create new charges or eliminate existing consumer protections.
How to Request Debt Validation
Under federal debt collection rules, covered collectors generally must provide validation information identifying the creditor, amount claimed, and dispute rights. The Consumer Financial Protection Bureau explains that consumers generally have 30 days after receiving the validation information to submit a written dispute. A timely written dispute requires the collector to pause collection of the disputed amount until verification is provided. Examine the balance breakdown and creditor details carefully. Keep dated copies of correspondence and delivery records to document the exchange.
How State Statutes of Limitations Work
A statute of limitations establishes the period during which a creditor or collector can generally file a lawsuit to enforce a debt. The Consumer Financial Protection Bureau notes that many jurisdictions use periods between three and six years, although some are longer. Applicable deadlines depend on state law, debt classification, contract provisions, and sometimes where the parties reside. Credit cards, written agreements, and other obligations may follow different rules. This legal deadline is separate from credit reporting retention periods.
When the Collection Lawsuit Clock Starts
Determining when a lawsuit limitation period begins requires examining the event that triggers the applicable state law. Depending on the jurisdiction and agreement, this could involve a missed payment, default, acceleration of the balance, or another legally defined event. The charge-off date itself is not necessarily the starting point. Account statements, payment records, and original contract terms help establish the relevant sequence. Some laws also address periods when the clock pauses, making an apparently simple calendar calculation more complicated.
Can a Payment Restart an Old Debt?
Making a partial payment on an old debt can have consequences beyond reducing the balance. In certain states, a payment may restart the statute of limitations or revive the ability to sue on an otherwise time-barred obligation. Some jurisdictions also treat written acknowledgments or new promises to pay as legally significant, while others impose stricter requirements or prohibit revival in particular circumstances. The Consumer Financial Protection Bureau cautions that these rules vary. Even a small payment deserves careful consideration under applicable law.
Can Collectors Contact You About Time-Barred Debt?
An expired statute of limitations does not necessarily prohibit every collection communication. In many states, collectors may still request voluntary repayment of time-barred debt through lawful calls or letters. However, federal Regulation F prohibits covered debt collectors from filing or threatening lawsuits to collect such debts, apart from its specified bankruptcy exception. The Federal Trade Commission also identifies deceptive and abusive collection practices as unlawful. Additional state restrictions may apply, including required disclosures. Consumers retain rights concerning unwanted communications and harassment.
What to Do if You Receive a Collection Lawsuit
Receiving a collection lawsuit requires attention to the court's stated response deadline, even when the debt appears too old to enforce. The Consumer Financial Protection Bureau warns that ignoring legal papers can lead to a default judgment. Review the complaint, identify the plaintiff, preserve financial records, and examine potential defenses, including expired limitations periods or disputed ownership. Such defenses may need to be raised affirmatively under court procedures. Legal aid organizations and qualified consumer attorneys can explain available options and filing requirements.
Your Rights Under the Fair Debt Collection Practices Act
The Fair Debt Collection Practices Act, or FDCPA, establishes federal protections for consumers contacted by covered debt collectors. According to the Federal Trade Commission and Consumer Financial Protection Bureau, the law generally applies to third-party collection agencies, debt buyers, and certain attorneys collecting consumer debts. It generally does not cover original creditors collecting their own debts under their own names, although other laws may apply. These protections remain important when collection activity involves charged-off accounts or older outstanding balances.
Debt Collection Practices That Are Prohibited
Covered debt collectors cannot use harassment, abusive language, threats of violence, or deceptive statements to pressure consumers. The FDCPA also restricts repeated calls intended to harass, communications at inconvenient times, and contact at workplaces when collectors know employers prohibit such communications. Collectors generally cannot disclose debt information to unauthorized third parties. Misrepresenting an amount owed, falsely threatening arrest, or claiming legal powers they do not possess can also violate federal consumer protection rules.
How to Document Collection Problems
A clear record can help establish what happened during questionable collection activity. Maintain a dated log of calls, caller identities, telephone numbers, and conversation details. Save collection letters, emails, text messages, voicemail recordings, and payment requests. Preserve original documents and avoid altering evidence. Where legally permitted, recordings may provide additional context. Consumers can submit complaints through the Consumer Financial Protection Bureau or report suspected violations to the Federal Trade Commission, providing supporting details without unnecessarily sharing sensitive information.
How Debt Settlement Changes the Balance
Debt settlement occurs when an authorized creditor or debt owner agrees to accept less than the claimed outstanding balance in satisfaction of an obligation. For example, a $5,000 balance might be resolved through an agreed $3,000 payment. Written terms should identify the account, authorized settling party, payment deadline, and treatment of the remaining balance. Settlement may affect credit reporting and create potential canceled-debt tax consequences. A reduced payment does not automatically remove accurate historical negative information.
When Canceled Debt Becomes Taxable Income
The Internal Revenue Service generally treats canceled debt as income when a borrower is released from an obligation to repay, unless an exception or exclusion applies. This treatment reflects the financial benefit of no longer owing the forgiven amount. A charge-off alone, however, is an accounting classification and does not necessarily establish forgiveness. The distinction matters because a creditor may still pursue repayment after recording a charge-off. Actual discharge circumstances determine whether cancellation-of-debt income rules become relevant.
Understanding the Form 1099-C $600 Threshold
The IRS generally requires applicable financial entities to file Form 1099-C when an identifiable reporting event involves cancellation of $600 or more of debt. Qualifying events can include negotiated forgiveness, certain judicial proceedings, and creditor decisions to discontinue collection. The $600 threshold determines reporting obligations, not whether canceled debt is taxable. Smaller forgiven amounts may still be taxable even without a form. Receiving Form 1099-C also does not establish that the entire reported amount is taxable income.
Bankruptcy and Insolvency Tax Exclusions
IRS Publication 4681 explains exclusions that may prevent certain canceled debts from becoming taxable income. Debt discharged in a qualifying Title 11 bankruptcy case generally qualifies for exclusion. Insolvency can also provide relief, limited to the amount by which total liabilities exceeded the fair market value of assets immediately before cancellation. Eligible taxpayers generally report these exclusions using Form 982, potentially with additional tax attribute adjustments. Because calculations and eligibility depend on individual circumstances, professional tax review may be appropriate.
What to Review Before Settling Charged-Off Debt
Before evaluating a settlement proposal, a practical review can identify important gaps in the available information. Check the debt validation notice, claimed balance, current ownership, and supporting account records. Examine applicable state limitation periods and whether acknowledgment or payment could affect legal deadlines. Compare proposed written terms with the requested payment amount and remaining obligation. Consider how the settlement will be reported to credit bureaus and whether forgiven amounts could create tax consequences. Preserve the completed agreement and payment confirmation.
A Practical Charge-Off Review Checklist
Four questions provide a useful framework for understanding what happens to charge-off debt. First, who currently owns the account and has authority to collect? Second, when did the continuous delinquency begin, establishing the credit reporting timeline? Third, what state law and legal deadlines govern potential collection lawsuits? Fourth, could eventual debt forgiveness create reportable or taxable income? Keeping separate answers and supporting documents for each question helps distinguish ownership, credit reporting, legal enforcement, and tax treatment.
Where to Find Reliable Help With Charged-Off Debt
Reliable information is available through several public and nonprofit resources. The Consumer Financial Protection Bureau provides debt collection guidance and complaint channels, while the Federal Trade Commission explains protections against unfair collection practices. IRS Publication 4681 covers canceled-debt tax treatment. Local legal aid organizations may explain applicable legal options, and reputable nonprofit credit counseling agencies can provide budgeting and debt management education. Maintaining organized records and checking information against official sources supports informed decisions without relying on questionable debt relief promises.
You check your credit report and notice an account marked "charged off." Maybe the bank has stopped sending regular statements, or a collection company has started contacting you. Does this mean your debt has disappeared? Unfortunately, a charge-off usually means something very different.
A charge-off is an accounting action that a creditor takes when an unpaid account is considered unlikely to be collected. It changes how the creditor records the balance, but it does not automatically forgive what you owe. Depending on your agreement and applicable laws, collection activity, interest, and fees may continue.
Understanding what happens next can help you avoid expensive misunderstandings. A charged-off account can damage your credit history, may be transferred or sold to another company, and could eventually become involved in a collection lawsuit. However, consumer protection laws place important limits on credit reporting and debt collection.
For example, negative account information generally remains on consumer credit reports for about seven years, measured from the delinquency that led to the charge-off. The deadline for filing a collection lawsuit is a separate issue governed largely by state law. If a creditor actually cancels a debt, federal income tax rules may also become relevant.
This guide explains these differences using guidance from the Consumer Financial Protection Bureau (CFPB), Federal Trade Commission (FTC), and Internal Revenue Service (IRS). You will learn how to identify who owns an account, examine important dates, understand collection protections, and recognize when professional guidance may be worthwhile.
Where people go wrong
Assuming a Charge-Off Erases the Balance. A charge-off changes the creditor's accounting treatment, not necessarily your repayment obligation. The original creditor or a subsequent owner may still pursue lawful collection. Verify whether the debt was actually forgiven before treating the account as resolved.
Counting Seven Years From the Charge-Off Date. The credit reporting period is generally tied to the original delinquency that led to the charge-off, not the later accounting entry. Confusing these dates can cause you to misunderstand when the negative information should stop appearing.
Confusing Credit Reporting With Lawsuit Deadlines. Credit reporting limits and statutes of limitations serve different purposes. An account disappearing from your credit report does not automatically eliminate the underlying debt. Likewise, an expired lawsuit deadline does not necessarily stop every lawful collection attempt.
Making Payments on Old Debt Without Checking the Law. Depending on state law, making a partial payment or acknowledging an old obligation may restart the limitations period. Before agreeing to repayment, establish the debt's identity, ownership, history, and applicable legal deadlines, preferably with professional guidance when uncertain.
Ignoring Collection Verification Information. An unfamiliar collector should not automatically be assumed to own a valid debt. Review the collection notice, verify the organization independently, and use applicable dispute rights when information appears incorrect. Keep copies of everything submitted or received.
Ignoring a Collection Lawsuit. Even when a debt may be too old for legal enforcement, failing to respond to court papers can result in a default judgment. A limitations defense generally must be raised through the appropriate legal process and within applicable deadlines.
Assuming Canceled Debt Is Always Tax-Free. A settlement or actual debt cancellation can have federal income tax consequences. Bankruptcy, insolvency, and other exceptions or exclusions may apply, but eligibility is not automatic. Review relevant IRS guidance and consider professional tax assistance before filing.
Questions people ask
A charge-off means a creditor has classified an unpaid account as a loss for accounting purposes. It does not automatically mean the creditor has forgiven the balance. The account may remain collectible, and the creditor may continue collection efforts, hire a collection agency, or sell the debt to another company.
Fixed it?
Get one guide like this every Thursday.