The Real Cost of Selling Your Home: Closing Costs, Agent Fees, and Taxes Explained
Selling your home involves more than agreeing on a price. Learn how closing costs, real estate commissions, mortgage payoffs, and capital gains taxes affect your proceeds, plus practical ways to prepare before closing.
What you’ll need
Tap to tick things off before you start.
Why Your Home's Sale Price Is Not Your Profit
The cost of selling a house begins with an important distinction: the sale price is not the amount the homeowner takes home. A $400,000 sale does not necessarily produce $400,000 in available cash. The remaining mortgage balance must be repaid, transaction expenses must be deducted, and applicable adjustments must be settled. What remains is the seller's net cash proceeds. Those proceeds also differ from taxable profit, which is calculated under separate tax rules involving the property's adjusted basis.
The Expenses That Can Surprise Home Sellers
Unexpected selling expenses can quickly reduce the cash available after closing. Common charges include real estate commissions, title services, escrow or settlement fees, transfer taxes, recording charges, and prorated property taxes. Sellers may also encounter mortgage-related payoff charges, homeowners association assessments, or agreed repair expenses. Some costs arise before closing, including cleaning, staging, moving, and preparing the property for sale. Because not every expense appears on the final closing paperwork, a complete selling budget should account for both transaction charges and preparation costs.
Why Selling Property Involves Multiple Professionals
A home sale requires coordination among several parties with distinct responsibilities. Real estate brokers market the property, facilitate negotiations, and help manage the transaction. Title companies investigate ownership records and identify potential title problems. Settlement or escrow agents coordinate documents and distribute funds. Mortgage lenders provide payoff information or financing for the buyer. Government offices handle recording and applicable taxes. In some states or transactions, attorneys prepare documents, oversee closing, or address legal questions. Understanding these roles helps explain why selling generates multiple service charges.
Who Actually Pays Closing Costs?
Both parties can be responsible for closing expenses, but their obligations are not automatically equal. The Consumer Financial Protection Bureau explains that responsibility for particular charges often depends on the purchase contract or applicable state law. Buyers commonly encounter loan-related charges, while sellers frequently cover expenses associated with transferring ownership. However, individual arrangements can differ. A purchase agreement may assign certain costs to either party, subject to legal and financing restrictions. The important distinction is between customary payment arrangements and actual contractual obligations.
Why Closing Costs Differ Across States and Counties
Location can substantially change the expenses associated with transferring residential property. Some states, counties, or municipalities impose real estate transfer taxes, while others use different tax structures or exemptions. Recording fees depend on local government requirements. Title insurance practices also vary, including whether certain policies are traditionally purchased by buyers or sellers. Some jurisdictions commonly use attorneys for closings, while others rely primarily on title or escrow companies. Consequently, national closing cost averages may not accurately represent expenses in a particular community.
Which Seller Expenses Can Be Negotiated?
Not every selling expense has the same flexibility. Real estate brokerage compensation is negotiable rather than fixed by law, and agreements may use percentage-based commissions, flat fees, or defined service packages. Sellers can also compare competing settlement or title service providers when permitted. Purchase contracts may allocate certain charges differently through negotiation. However, government-imposed taxes, statutory recording fees, and legally required obligations cannot simply be waived through private agreement. Negotiating who bears a charge does not necessarily eliminate the underlying expense.
Why the Highest Offer May Not Be the Best Offer
A higher purchase offer can produce a weaker financial result when it includes costly conditions. Consider a $410,000 offer requesting $15,000 in seller concessions compared with a $400,000 offer requesting only $2,000. Before other transaction expenses, the first effectively provides $395,000, while the second provides $398,000. Repair credits, inspection contingencies, financing uncertainty, and closing timelines also influence an offer's attractiveness. Comparing the economic terms and likelihood of completion provides a more meaningful assessment than looking exclusively at the proposed price.
How to Estimate Your Net Proceeds
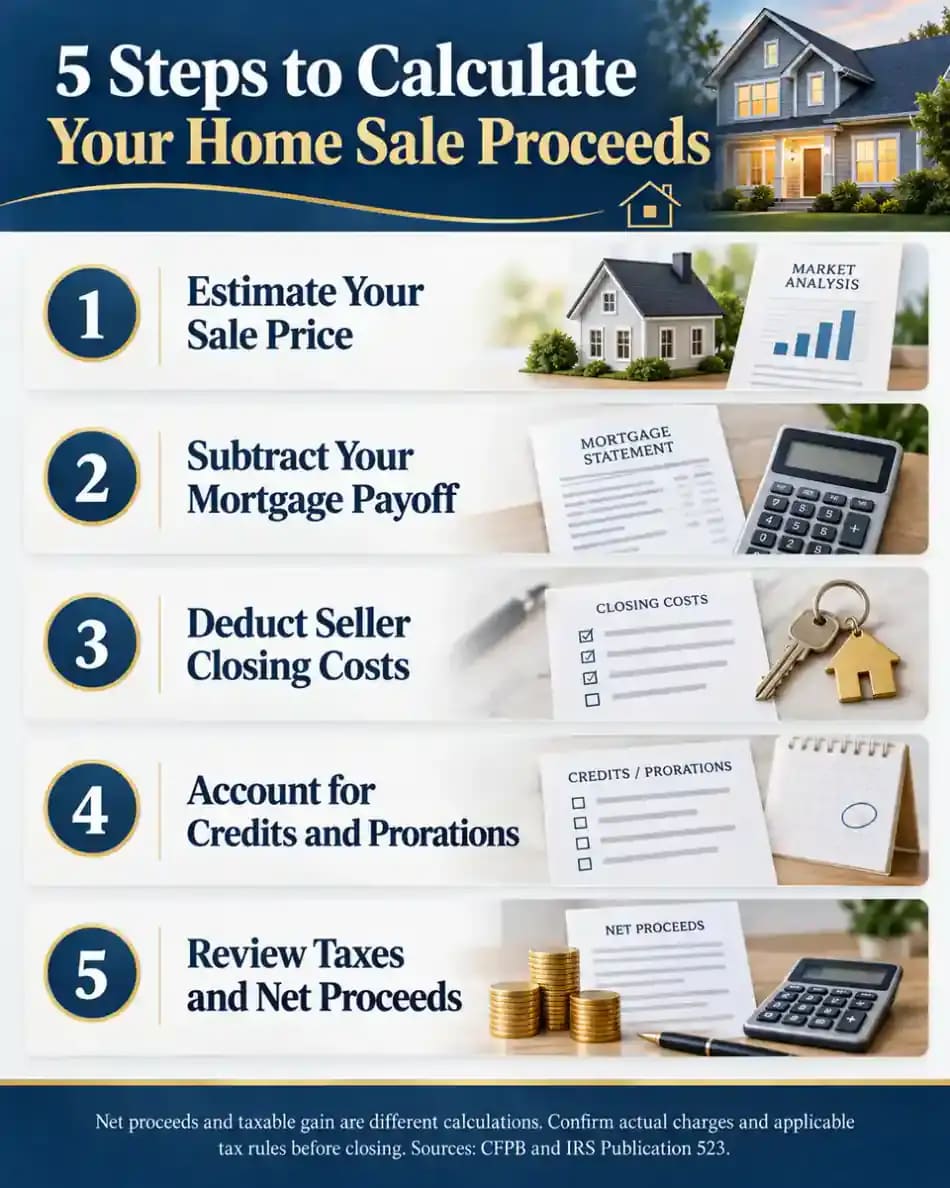
A basic estimate starts with the sale price, then subtracts the mortgage payoff, seller-paid transaction expenses, and net contractual adjustments. Suppose a home sells for $400,000, the mortgage payoff is $240,000, seller expenses total $24,000, and net adjustments reduce proceeds by $3,000. Estimated cash proceeds would equal $133,000. This calculation assumes no additional liens or obligations. Mortgage payoff figures may include accrued interest and other amounts, so preliminary estimates can change before closing. The result represents cash proceeds, not taxable capital gain.
What the Closing Disclosure Tells You
The Consumer Financial Protection Bureau's Closing Disclosure is a standardized mortgage document that identifies transaction charges and how they are allocated. In covered mortgage transactions, seller-paid expenses appear in designated sections alongside other closing information. The form helps clarify which charges are attributed to the seller, although it primarily serves the mortgage disclosure process. Sellers should also examine their applicable settlement statement, which may provide a more direct accounting of their proceeds. Not every property sale requires a Closing Disclosure.
Understanding Your Seller Settlement Statement
A seller settlement statement organizes the financial entries used to determine the final amount payable to the homeowner. The sale price generally appears as a credit, while loan payoffs, transaction charges, and other seller obligations appear as debits. Prorations allocate shared expenses, such as property taxes, according to the applicable closing period. Additional credits may reflect deposits or contractual adjustments. The statement then reconciles these entries with disbursements, showing how funds are distributed to lenders, service providers, and ultimately the seller.
The Most Common Seller Closing Charges
The cost of selling a house includes several charges beyond the listing price and mortgage balance. Common deductions include mortgage payoff amounts, real estate broker compensation, government transfer taxes, recording fees, title insurance, and escrow or settlement services. Sellers may also owe property taxes prorated through closing, outstanding homeowners association dues, or association transfer charges. The Consumer Financial Protection Bureau explains that responsibility for closing expenses varies according to contractual agreements and applicable state laws.
Where Every Dollar of Your Sale Price Goes
Consider a hypothetical home sale for $400,000 with a $220,000 mortgage payoff. Suppose transaction expenses total $24,000 and negotiated seller credits equal $6,000. The seller would receive approximately $150,000 before any additional adjustments or tax consequences. That represents 37.5% of the sale price, not the full $180,000 remaining after mortgage repayment. These figures are illustrative rather than typical percentages. Actual proceeds depend on financing balances, negotiated terms, local charges, and final settlement calculations.
How Closing Statement Errors Happen
Settlement documents can contain mistakes even when professionals prepare them carefully. A service charge might appear twice, or an expense assigned to the buyer could mistakenly reduce the seller's proceeds. Property tax prorations may use an incorrect closing date or outdated assessment information. Mortgage payoff figures can also become inaccurate when interest accrues beyond the statement's effective date. These discrepancies matter because even relatively small accounting errors can change the amount ultimately disbursed to the seller.
How to Check Closing Charges Against Your Contract
A useful verification process starts with the signed purchase agreement and any amendments. Compare their expense allocations, seller concessions, and closing date against the settlement statement or applicable Closing Disclosure. Next, confirm that agreed credits appear correctly and request supporting calculations for unfamiliar adjustments. The Consumer Financial Protection Bureau provides guidance on understanding closing documents, although the specific forms sellers receive can vary. Raise discrepancies with the settlement agent and request corrected figures before funds are disbursed.
How Much Do Real Estate Agents Charge?
Real estate agents often receive compensation calculated as a percentage of the property's sale price, although flat fees and other arrangements are available. For illustration, a 2.5% listing commission on a $400,000 sale equals $10,000. That example is not a standard or required rate. The amount depends on the agreement and services provided, potentially including pricing guidance, photography, marketing, showings, negotiations, and transaction coordination. Compensation reduces seller proceeds when it is charged to the seller.
Why Real Estate Commissions Are Negotiable
No federal law establishes a mandatory real estate commission percentage. Broker compensation is negotiable, including the amount, services, and payment conditions. Written listing agreements should identify the compensation arrangement, its duration, and circumstances that trigger payment. Sellers can also discuss contract termination provisions and whether additional services require separate charges. Evolving industry practices have increased attention to clearly documented compensation terms. Negotiability does not guarantee that every brokerage will accept a particular proposed fee or service arrangement.
How Real Estate Compensation Practices Have Changed
Historically, many listing brokers received compensation from sellers and offered part of that amount to brokers representing buyers. Following major industry changes implemented in August 2024, offers of buyer-broker compensation were prohibited on multiple listing services operated under National Association of Realtors policies. Such compensation can still be arranged through permitted channels outside those systems. Buyer representation agreements also became more prominent, making compensation obligations more explicit. Applicable requirements vary by brokerage, transaction, and jurisdiction.
Comparing Percentage, Flat-Fee, and Limited-Service Models
Percentage-based arrangements generally increase in dollar value as the sale price rises, while flat-fee models specify a set payment regardless of price. Limited-service arrangements may charge separately for listing access, photography, marketing, negotiations, or paperwork assistance. Lower advertised fees do not necessarily mean lower total transaction costs. Some packages exclude services that sellers must purchase elsewhere. Comparing these models requires examining total compensation, included responsibilities, contract limitations, and the professional support available when complications arise.
Who Pays the Buyer's Real Estate Agent?
Buyer-agent compensation can be handled through several contractual arrangements. A buyer may pay their representative directly under a written agreement. Alternatively, a seller may authorize compensation to the buyer's broker through a negotiated transaction arrangement. Sellers might also provide concessions that help buyers cover eligible closing expenses, potentially including representation costs where permitted. These alternatives are not automatically interchangeable. Contract language, lender restrictions, applicable regulations, and brokerage policies can affect how payments are structured and recorded.
How to Protect Your Home Equity During Negotiations
Protecting equity requires evaluating the entire financial outcome rather than simply accepting the highest offer. Compare estimated net proceeds after transaction charges, requested concessions, and anticipated repair contributions. Consider whether financing contingencies, appraisal conditions, or uncertain closing timelines introduce additional risk. When evaluating brokerage proposals, weigh the services and professional assistance included against total compensation. A slightly lower offer with fewer deductions and stronger terms may produce a better result than a higher offer carrying expensive conditions.
When Selling a Home Creates a Tax Obligation
Selling a home can create a federal capital gains tax obligation, but the amount deposited into your bank account is not necessarily your taxable profit. Net proceeds reflect the sale price minus mortgage payoffs and transaction expenses. Capital gain generally reflects the amount realized from the sale minus your adjusted tax basis. The Internal Revenue Service treats qualifying sales of principal residences differently from many other asset sales, potentially allowing homeowners to exclude substantial gains from federal income.
Understanding the $250,000 and $500,000 Home Sale Exclusions
IRS Publication 523 explains that eligible taxpayers can generally exclude up to $250,000 in gain from selling their main home. Married couples filing jointly may qualify for an exclusion of up to $500,000 when the applicable requirements are satisfied. These figures apply to capital gain, not the home's selling price or the seller's closing check. For example, selling a property for $600,000 does not automatically create $600,000 in taxable gain. Eligibility determines how much qualifying gain can be excluded.
The IRS Two-Out-of-Five-Year Ownership and Use Tests
To qualify for the federal home sale exclusion, taxpayers generally must have owned the property for at least two years during the five years before the sale. They must also have used it as their main home for at least two years within that period. The ownership and residence periods need not overlap or be consecutive, although special rules apply to married filers. IRS Publication 523 also describes additional eligibility conditions, exceptions, and reduced exclusions for certain qualifying circumstances.
When Home Sale Gains May Be Excluded From Federal Tax
Consider an eligible single homeowner with a correctly calculated $200,000 gain on a principal residence. The federal exclusion could eliminate income tax on that entire gain. However, recent use of the exclusion, partial eligibility, or depreciation attributable to certain business or rental uses can change the outcome. Gains exceeding the applicable exclusion may remain taxable. IRS Publication 523 also explains that receiving Form 1099-S can trigger a reporting requirement even when the gain is fully excludable.
Why a Loss on Your Main Home Usually Is Not Deductible
A disappointing selling price does not automatically translate into a deductible tax loss. According to the IRS, losses from selling a home used as a personal residence are generally nondeductible, even when the adjusted basis exceeds the amount realized. Such losses cannot ordinarily offset wages or investment gains. Properties held for investment or used in a business follow different tax rules, including special considerations when property use changes. This distinction matters when evaluating an unsuccessful home sale.
Why You Should Request a Seller Net Sheet Early
Request a preliminary seller net sheet from your real estate agent or settlement professional before setting a listing price or evaluating offers. It should estimate broker compensation, mortgage payoff, transfer taxes, title and settlement charges, prorations, concessions, and expected cash proceeds. Ask for scenarios using different sale prices to reveal how negotiations affect your outcome. Because this worksheet is an estimate rather than a final settlement statement, update it whenever financing, closing dates, fees, or contract terms change.
How Home Improvement Records Affect Your Tax Basis
Your home's adjusted tax basis generally begins with its original cost, plus certain acquisition expenses, and changes through qualifying adjustments. Capital improvements that add value, extend useful life, or adapt a home to new uses can increase basis and potentially reduce taxable gain. Examples may include a new roof, an addition, or a major kitchen renovation. Ordinary repairs and routine maintenance generally do not qualify independently. Keep invoices, payment records, permits, and project descriptions to support adjustments under IRS Publication 523.
Questions to Ask Before Signing Closing Documents
Before signing, ask your agent whether broker compensation and seller concessions match the negotiated agreements. Ask the settlement professional which charges are final, which remain estimates, and whether tax or homeowners association prorations are accurate. An attorney can clarify disputed contractual responsibilities or unfamiliar legal provisions. A qualified tax adviser can address unusual ownership, residence, or property-use circumstances. The Consumer Financial Protection Bureau emphasizes understanding closing charges, making unexplained differences worth resolving before completing the transaction.
Your Home Selling Cost Checklist
A complete selling cost review should cover seven verification areas: purchase contract allocations, agreed broker compensation, current mortgage payoff, title and settlement charges, tax and homeowners association adjustments, documented capital improvements, and federal tax exclusion eligibility. Check whether credits or concessions appear on the correct party's side of the transaction. Keep supporting agreements, invoices, and settlement records together. This organized checklist makes the cost of selling a house easier to audit and reduces the chance of overlooking an important financial detail.
Make Your Next Home Sale Decision With Better Numbers
The strongest home sale decisions start with realistic figures instead of an attractive asking price. Obtain an updated seller net sheet, verify closing charges against signed agreements, and preserve records supporting your financial calculations. Compare competing offers by their expected proceeds after all negotiated expenses, not simply their headline amounts. When tax treatment or contractual language is complicated, qualified professionals can provide transaction-specific guidance. Understanding the full cost of selling a house gives homeowners a clearer foundation for their next move.
You accept an offer of $400,000 for your home. It sounds like a substantial payday. But how much of that money will actually reach your bank account?
The answer depends on considerably more than the agreed sale price. Real estate agent compensation, title and settlement services, transfer taxes, mortgage payoffs, seller concessions, and adjustments for property taxes can all reduce the amount you receive at closing. Some charges are predictable, while others depend on your location and the terms negotiated with the buyer.
According to the Consumer Financial Protection Bureau, responsibility for transaction charges can depend on the purchase contract and applicable state law. There is no universal seller closing cost percentage that accurately describes every transaction.
Taxes introduce another consideration. Under IRS Publication 523, Selling Your Home, eligible homeowners may exclude up to $250,000 of gain, or $500,000 for qualifying married couples filing jointly. However, ownership requirements, residence history, and other circumstances can change the outcome.
This guide explains where your sale proceeds go, which expenses may be negotiable, how to examine closing paperwork, and what records can help you evaluate potential tax consequences. You will also learn how to request a preliminary seller net sheet and compare competing offers based on the money you could actually keep.
The objective is simple: understand the financial mechanics before signing a contract, rather than discovering unexpected deductions at closing.
Where people go wrong
Confusing the Sale Price With Take-Home Money. A $400,000 sale does not mean a $400,000 payout. Mortgage debt, transaction fees, concessions, and prorated expenses may substantially reduce the proceeds. Create a seller net sheet before listing and update it whenever the expected terms change.
Assuming Agent Commissions Are Fixed. Real estate broker compensation is negotiable, not established by a universal legal rate. Accepting a proposed percentage without discussing services, alternatives, and buyer-agent compensation arrangements can increase expenses. Compare written agreements and evaluate the services included before signing.
Ignoring the Financial Impact of Seller Concessions. A higher offer can produce lower net proceeds if it includes substantial closing cost credits, repair allowances, or other seller obligations. Compare offers using the estimated amount remaining after contractual expenses instead of ranking them by purchase price alone.
Failing to Review Settlement Charges. A settlement statement may contain estimated amounts, incorrect prorations, or charges allocated to the wrong party. Comparing the final figures against your signed contract and earlier estimates gives you an opportunity to question discrepancies before funds are disbursed.
Treating Every Home Improvement as a Tax Deduction. Certain capital improvements can increase a home's adjusted tax basis, but ordinary repairs and maintenance generally follow different rules. Assuming every renovation expense automatically reduces taxable gain can produce misleading estimates. Preserve documentation and verify the applicable IRS treatment.
Assuming Every Home Sale Gain Is Tax-Free. The federal home sale exclusion has eligibility requirements and limits. Ownership, primary residence use, previous exclusions, depreciation, and other circumstances may affect the result. Review IRS Publication 523 rather than assuming the entire profit automatically qualifies for exclusion.
Forgetting That Closing Costs Vary by Location. Transfer taxes, recording charges, title services, and customary fee allocations differ across jurisdictions. Applying a national average to a specific transaction can distort your budget. Obtain local estimates and verify which charges are legally required and which responsibilities can be negotiated.
Questions people ask
The cost depends on your sale price, location, agreed broker compensation, settlement services, taxes, and buyer concessions. Your mortgage payoff also reduces the cash you receive, although it is repayment of debt rather than a transaction fee. A preliminary seller net sheet provides a more useful estimate than a national average.
Fixed it?
Get one guide like this every Thursday.