How to Build a Realistic Monthly Budget for Your Dog or Cat
Discover how to create a realistic monthly pet budget that covers food, routine care, annual vet bills, supplies, and emergency savings. Includes a practical budgeting worksheet and sample costs for dog and cat owners.
What you’ll need
Tap to tick things off before you start.
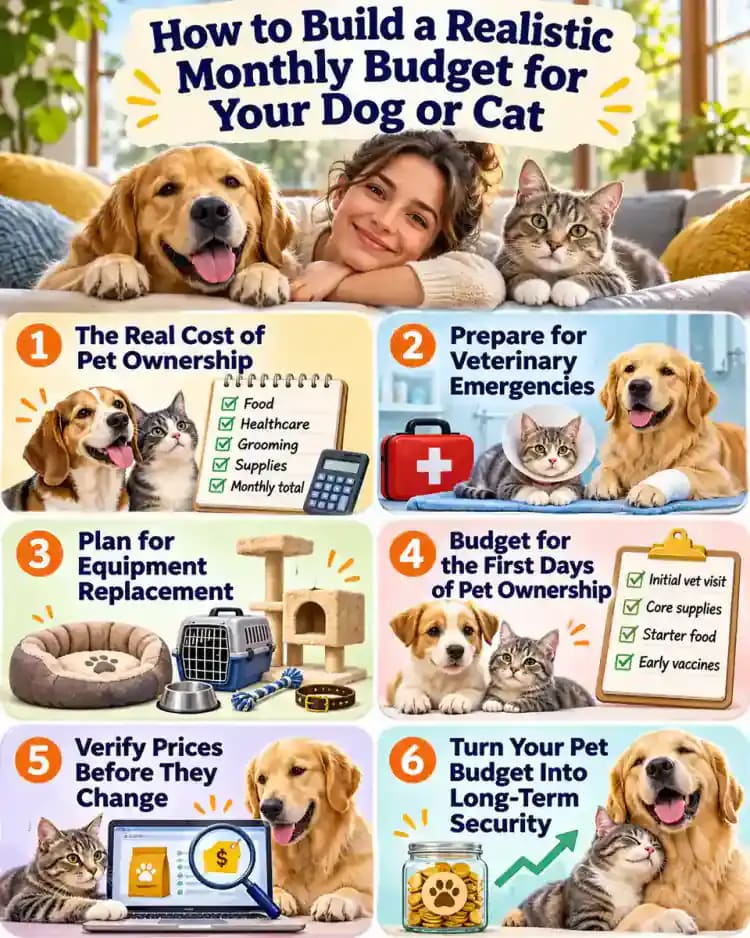
The Real Cost of Pet Ownership
Start by identifying everything you spend to keep your dog or cat healthy and comfortable. Look beyond food to include grooming, veterinary visits, litter, preventive medications, and replacement supplies. Review recent receipts and bank transactions to uncover expenses you might overlook. Understanding your complete spending picture is the foundation of a realistic monthly pet budget.
Create Three Budget Categories
Divide your budgeting worksheet into three columns: Monthly Expenses, Occasional Expenses, and Emergency Savings. Place regular purchases such as food and litter in the first column, annual veterinary bills and replacement equipment in the second, and unexpected medical costs in the third. Keeping these categories separate makes upcoming expenses easier to anticipate and manage.
Calculate Everyday Pet Expenses
Calculate recurring expenses using actual purchase prices and how frequently you replace each product. For food, multiply your pet's daily portion by 30, then calculate its cost using the package price and quantity. Include litter, waste bags, grooming, preventive medications, and basic supplies. Compare local retailers and veterinary recommendations to develop estimates that reflect your pet's needs.
Turn Annual Bills Into Monthly Savings
List predictable expenses that occur less frequently, including routine veterinary examinations, vaccinations, identification renewals, and replacement equipment. Estimate each annual cost using local prices and divide the total by 12. For example, a $240 yearly expense requires $20 in monthly savings. Set this money aside consistently so scheduled bills do not unexpectedly strain your household budget.
Build a Practical Monthly Example
Test your worksheet with a fictional dog budget: $60 for food, $20 for grooming, $15 for preventive care, $25 for supplies, and $30 saved toward annual expenses. Together, these categories total $150 per month before emergency savings or insurance. Replace these example figures with your actual local prices and adjust categories to match your pet's requirements.
Prepare for Veterinary Emergencies
Create a separate emergency fund for unexpected veterinary expenses, including accidents, sudden illnesses, and urgent treatments. Contact local emergency clinics to understand potential costs, then choose a monthly savings contribution you can maintain. If considering pet insurance, compare premiums, deductibles, coverage exclusions, reimbursement percentages, and annual limits. Keep accessible savings available even when insured.
Track Spending and Adjust Your Estimates
Review your actual pet spending against your budget every month. Save receipts, check transaction records, and update your spreadsheet whenever costs differ from estimates. Account for changing needs as your pet grows from puppy or kitten to adult and senior. Revisit food quantities, veterinary expenses, and supplies regularly to keep your monthly budget accurate.
Create Your Budget and Take Action
Write down your pet's recurring costs, divide occasional expenses into monthly savings targets, and add an affordable emergency fund contribution. Calculate the complete monthly amount and schedule automatic transfers when possible. Review your budget regularly, adjusting estimates as needed. Focus on consistent, sustainable planning that helps you provide dependable care without unnecessary financial surprises.
Identify Hidden Pet Ownership Expenses
Check for less obvious expenses such as boarding, pet sitting, training classes, travel arrangements, and additional cleaning supplies. Estimate costs using local providers and how frequently you realistically need each service. Separate essential care from optional conveniences, and create savings targets for predictable events. Avoid including unnecessary services simply because other pet owners purchase them.
Adjust Costs for Size and Lifestyle
Adjust your budget to reflect each animal's size, age, activity level, and living environment. Larger dogs generally require more food, while certain preventive medications are priced by weight. Indoor and outdoor cats may need different supplies and services. For multiple pets, calculate individual expenses separately, then account for shared equipment without overlooking recurring costs.
Compare Real Value Instead of Price
Compare pet products by cost per serving or actual usage rather than package price alone. Calculate how many meals a food bag provides and consider proper storage and freshness. For cat litter, track how long each container lasts. Choose products that meet your pet's needs, since cheaper purchases may ultimately cost more through waste or frequent replacement.
Plan for Equipment Replacement
Create a simple inventory of your pet's equipment, including collars, leashes, beds, carriers, and scratching posts. Record purchase dates, inspect items regularly, and estimate when replacements might be necessary. Prioritize damaged safety equipment, such as a frayed leash, before optional upgrades. Set aside a small monthly amount to spread predictable replacement costs across the year.
Automate Your Pet Savings
Set up automatic transfers into dedicated pet savings accounts or clearly labeled budget categories. Schedule contributions shortly after payday and choose amounts your household can consistently afford. Keep savings for routine veterinary bills and planned purchases separate from emergency reserves. Review your balances monthly, increasing contributions gradually when possible rather than committing to unrealistic savings targets.
Save Money Without Sacrificing Care
Reduce pet expenses through careful comparison shopping, appropriate package sizes, and realistic purchasing schedules rather than skipping essential care. Ask your veterinarian which preventive services your pet needs and request written cost estimates. Compare reputable providers and discuss available payment options. Prioritize nutrition, necessary treatments, and safety before spending on optional accessories or convenience services.
Handle Months That Exceed Your Budget
When actual spending exceeds your monthly pet budget, identify the cause before changing your plan. Separate one-time purchases from permanent price increases and inaccurate estimates. Cover essential care first, then adjust future savings targets or spread predictable expenses across additional months. Record the difference in your worksheet and revise recurring amounts when higher costs are likely to continue.
Make Pet Budgeting a Lasting Habit
Schedule a recurring monthly reminder to review your pet expenses and compare actual spending with your budget. Update estimates when prices or care requirements change, and share the plan with everyone responsible for your pet. Keep receipts and savings balances accessible. A consistent review habit helps your household make informed decisions and prepare for unexpected costs.
Prepare for Changes in Household Income
Create a backup plan for periods when household income decreases unexpectedly. Identify essential expenses such as food, necessary medications, and veterinary treatment, then separate purchases that can safely wait. Estimate how long your available savings could cover basic pet care. Research reputable local assistance programs and discuss affordable care options with your veterinarian before financial difficulties escalate.
Budget for the First Days of Pet Ownership
Before bringing home a new dog or cat, calculate one-time startup expenses separately from your regular monthly budget. Include adoption fees, initial veterinary care, identification, food bowls, bedding, carriers, and safety equipment. Ask the shelter which medical services are already included. Compare local prices and establish a startup savings target before committing to adoption.
Account for Housing and Property Costs
Review your housing agreement and property needs for expenses connected to pet ownership. Renters should check applicable pet deposits, recurring fees, and cleaning requirements, while homeowners may need fencing, repairs, or protective equipment. Record one-time housing expenses separately from monthly charges. Keep these costs distinct from veterinary savings so your care budget remains accurate.
Use Medical History to Improve Planning
Organize your pet's veterinary records, vaccination history, medication instructions, and previous invoices in one accessible location. Review these documents to identify scheduled follow-up visits, recurring prescriptions, and predictable care expenses. Ask your veterinarian about recommended future services and estimated costs. Update your monthly savings targets using professional guidance rather than making assumptions about your pet's health.
Calculate the Cost of Traveling With Pets
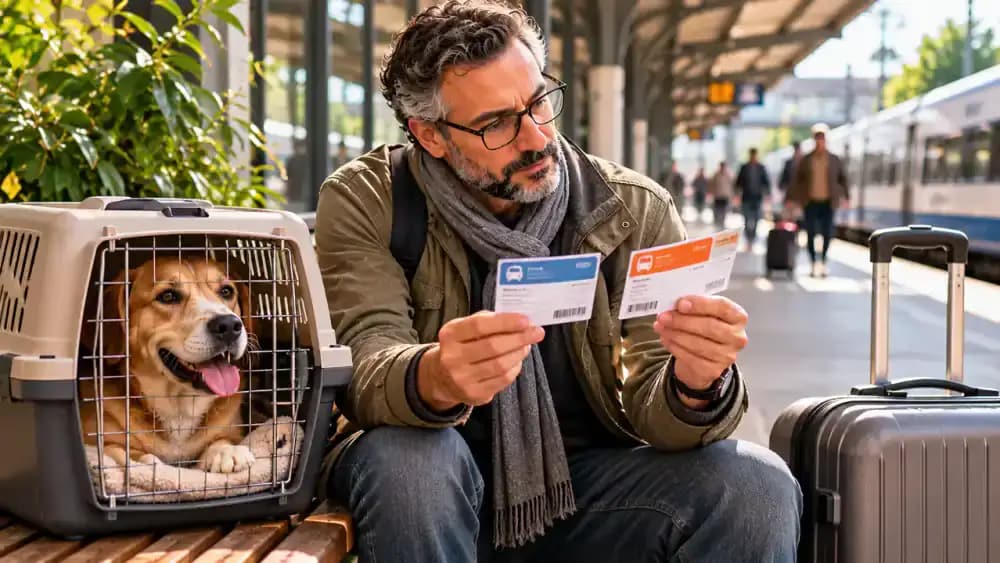
Before traveling with your pet, compare transportation fees, approved carrier requirements, pet-friendly accommodation charges, and necessary documentation costs. Request current prices and review applicable travel policies before booking. Compare the total with boarding or trusted in-home pet care. Keep travel expenses in a separate discretionary category so routine veterinary care and essential supplies remain funded.
Stress Test Your Budget Before Committing
Compare your proposed monthly pet budget against household income after accounting for housing, utilities, groceries, and existing financial obligations. Test affordable, tight, and higher-cost scenarios, including unexpected price increases. Avoid depending on credit to cover predictable care. If essential expenses exceed available income, reduce discretionary purchases or reconsider the timing of adopting another pet.
Complete Your Sustainable Pet Care Budget
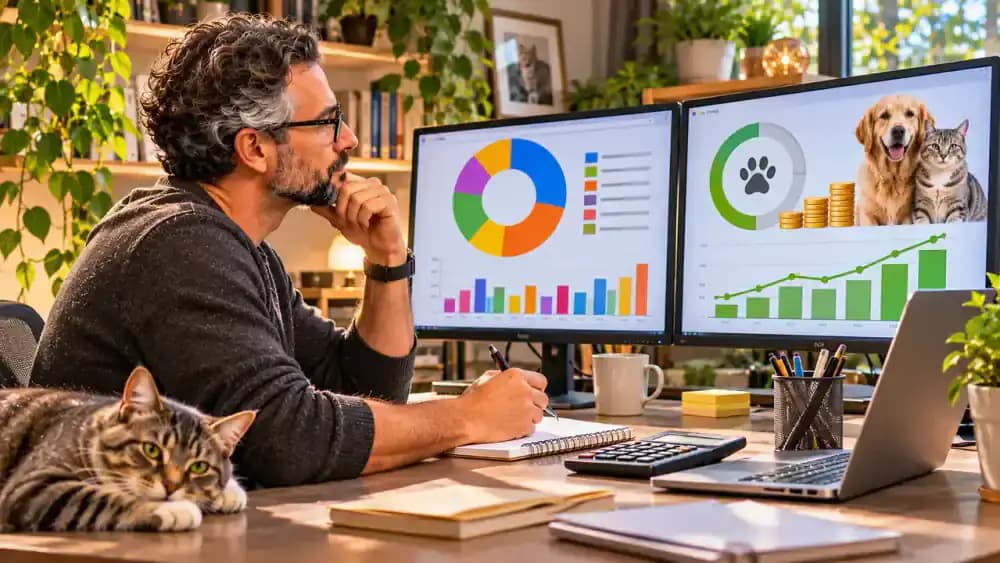
Review your completed budget to confirm it covers next month's essentials, upcoming veterinary bills, planned purchases, and emergency savings. Compare expected expenses with available funds and identify any shortfalls before they become urgent. Keep your worksheet straightforward and revisit it monthly. A sustainable budget should support dependable care while protecting your household's broader financial stability.
Verify Prices Before They Change
Schedule regular price checks for veterinary services, grooming appointments, boarding, and frequently purchased supplies. Contact providers before appointments to confirm current rates, including additional service fees. Compare updated estimates with previous invoices and revise your monthly savings targets when necessary. Checking prices in advance prevents outdated assumptions from creating avoidable financial surprises when bills arrive.
Prepare for Seasonal Pet Care Expenses
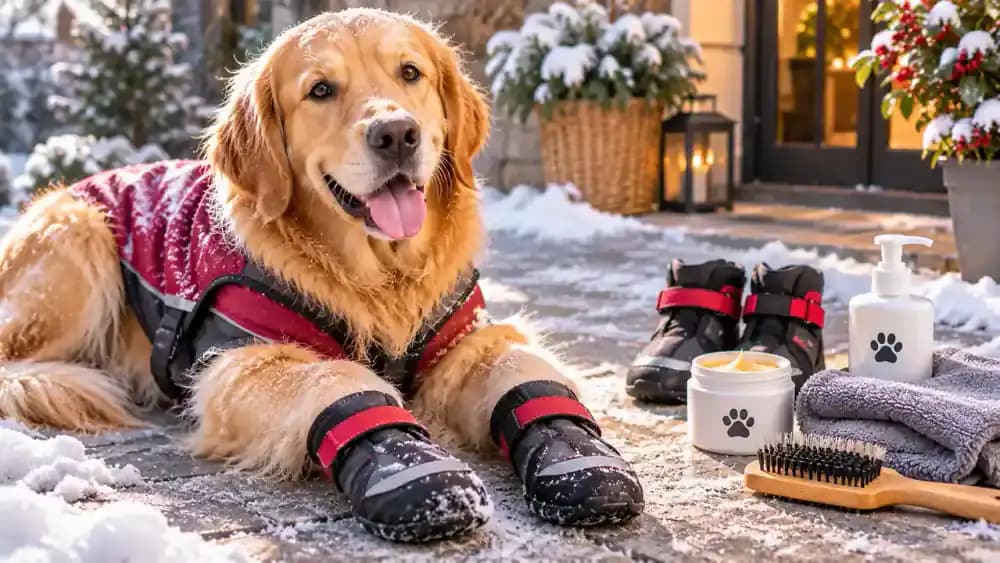
Adjust your pet budget for seasonal needs based on your local climate and your animal's lifestyle. Consider cooling supplies during hot weather, paw protection in winter, and veterinarian-recommended parasite prevention throughout relevant seasons. Ask your veterinarian about appropriate seasonal care rather than assuming every product is necessary. Spread predictable seasonal purchases across monthly savings contributions.
Control Delivery and Subscription Costs
Review the complete cost of recurring pet supply orders, including shipping fees, subscription requirements, and potential price changes. Compare standard delivery with expedited shipping before purchasing. Maintain a reasonable supply of essentials to avoid expensive last-minute orders, but check expiration dates and storage requirements. Cancel subscriptions that no longer provide meaningful savings or convenience.
Plan for Changes in Your Daily Schedule
Consider how changes in work hours, travel, or personal availability might affect your pet care expenses. Research local dog walking, grooming assistance, and temporary caregiving rates before you need them. Identify a reliable backup caregiver and document their contact information. Include predictable assistance costs in your monthly budget and reserve savings for unexpected schedule disruptions.
Avoid Spending More Because of Discounts
Evaluate promotional offers against your pet's actual needs rather than the advertised discount. Before purchasing toys, accessories, or extra supplies, check your shopping list and existing inventory. Consider whether each item supports necessary care, safety, or appropriate enrichment. Skip unnecessary purchases, even when heavily discounted, and direct available money toward planned expenses or emergency savings.
Divide Pet Expenses Between Caregivers
When multiple people share responsibility for a pet, establish clear agreements about expenses and payments. Assign recurring purchases, veterinary bills, and emergency contributions, then record responsibilities in a shared tracker. Decide how reimbursements will work and who can authorize urgent spending. Review the arrangement regularly so essential supplies and appointments remain covered when circumstances change.
Turn Your Pet Budget Into Long-Term Security
Choose one practical improvement to make today: verify a recurring supply price, confirm your next veterinary appointment, or increase your emergency savings contribution by an affordable amount. Record the action in your budgeting worksheet and schedule your next review. Consistent small improvements help your financial plan support dependable pet care throughout your companion's life.
Your dog is happily chasing a favorite toy, your cat is curled up in a sunny window, and both have everything they need for another comfortable day. Food bowls are full, the litter box is clean, and the next routine veterinary visit is on the calendar. These everyday moments make pet ownership rewarding, but keeping them consistent takes more than buying a bag of food every month.
A realistic monthly pet budget accounts for predictable purchases, less frequent expenses, and money reserved for unexpected veterinary care. Food, litter, grooming, preventive medications, identification, toys, and cleaning supplies all contribute to the cost of caring for a dog or cat. Annual checkups, vaccinations, and replacement equipment can also strain your finances when you haven't planned ahead.
The simplest approach is to divide your budget into three categories: recurring expenses, occasional expenses, and emergency savings. You can then use actual prices from local stores, veterinary clinics, and service providers instead of relying on national averages that may not reflect your pet's needs.
This guide explains how to organize a straightforward budgeting worksheet, convert occasional costs into monthly savings targets, and calculate a practical example. You'll also learn where pet insurance fits, how much flexibility to build into your estimates, and why your budget should evolve as your pet ages. The goal isn't to predict every expense perfectly. It's to make responsible care financially manageable, month after month.
Where people go wrong
Budgeting Only for Food and Treats. Food is one of the easiest pet expenses to estimate, but it rarely represents the complete cost of ownership. Routine veterinary visits, vaccinations, parasite prevention, grooming, waste disposal, and replacement supplies can create substantial additional expenses. Build your budget around every category your pet actually needs, even when certain purchases happen only a few times per year.
Using National Averages Instead of Local Prices. Online estimates can provide a useful starting point, but veterinary fees, grooming rates, and product prices differ considerably between locations. A budget based entirely on national averages may underestimate what you will actually spend. Check nearby veterinary clinics, pet stores, grooming providers, and online retailers to establish realistic prices for the products and services you use.
Forgetting Annual and Seasonal Expenses. A yearly veterinary examination or a replacement pet carrier might seem unrelated to your monthly budget, but these costs still need funding. Divide predictable annual expenses by 12 and set aside that amount every month. Account for seasonal needs, boarding, licensing renewals, and other occasional purchases so they do not become unexpected financial pressures.
Treating Emergency Savings as Routine Spending Money. Emergency savings should remain available for unexpected injuries, illnesses, or urgent veterinary treatment. Using the same balance for food, vaccinations, or scheduled grooming can leave you financially unprepared when something serious happens. Maintain separate categories for predictable pet expenses and emergency reserves, and replenish the emergency fund after withdrawals whenever your financial situation allows.
Assuming Pet Insurance Covers Everything. Pet insurance may help manage eligible veterinary expenses, but policies frequently include deductibles, reimbursement percentages, exclusions, annual limits, or waiting periods. Many plans also require owners to pay the veterinarian before receiving reimbursement. Compare actual policy terms and premiums instead of assuming every treatment will be covered, and retain accessible savings even when your pet is insured.
Ignoring Your Pet's Size, Age, and Individual Needs. A large dog may consume considerably more food than a small dog, while some cats require specialized litter, additional grooming, or specific veterinary care. Costs can also change as pets grow older. Avoid copying another owner's budget without adjusting it for your animal's size, age, lifestyle, veterinary recommendations, and individual needs.
Setting an Unrealistic Savings Target. An emergency fund goal is useful only when you can contribute consistently without sacrificing essential household expenses. Choosing an aggressive monthly amount that you cannot maintain may cause you to abandon the plan entirely. Start with an achievable contribution, automate transfers when practical, and increase the amount gradually as your financial circumstances improve.
Never Reviewing Actual Spending. Even a carefully prepared budget becomes inaccurate when prices increase or your pet's needs change. Compare your planned expenses against actual purchases every month, especially during the first few months of tracking. Adjust recurring estimates, update annual savings targets, and revisit emergency contributions whenever veterinary recommendations, insurance premiums, or household finances change.
Questions people ask
There is no single monthly amount that accurately reflects every pet's needs. As an illustrative planning example, a dog owner might calculate $65 for food, $25 for preventives, $30 for grooming and supplies, $35 for routine veterinary savings, and $50 for emergencies, totaling $205 per month. Actual costs depend on your location, pet, insurance choices, and services used.
Fixed it?
Get one guide like this every Thursday.