How Much Emergency Savings Do You Really Need? Beyond the 3-6 Month Rule
The three-to-six-month emergency fund rule is a starting point, not a perfect answer. Learn how to calculate your essential expenses, adjust for income risk, choose safe accounts, and build a savings cushion that fits your household.
What you’ll need
Tap to tick things off before you start.
Why Your Emergency Fund Needs a Personal Target
A useful emergency fund starts with your household's circumstances, not someone else's savings balance. Two families earning identical salaries might face very different risks because their necessary expenses, income reliability, and financial responsibilities differ. One household may have substantial obligations, while another has considerable monthly flexibility. Instead of asking only how much emergency savings you need, consider what financial disruptions your household must be prepared to withstand and how long those disruptions could realistically last.
What Federal Reserve Data Reveals About Emergency Savings
According to the Board of Governors of the Federal Reserve System, 55% of adults reported having emergency savings covering three months of expenses in 2024, a figure that remained at 55% in 2025. This measures reported savings, not every possible resource households could use during hardship. Some people might borrow, receive assistance, or sell assets instead. The findings highlight an important distinction: having readily available savings differs from having potential alternatives during a financial emergency.
What Counts as a Real Financial Emergency?
A financial emergency is an unexpected event requiring money to protect your health, safety, housing, or essential financial stability. Examples include urgent plumbing repairs, necessary medical treatment, or expenses during an unforeseen income interruption. Routine annual insurance premiums, vacations, and predictable car maintenance generally belong in separate savings categories. A useful test is whether the expense is necessary, difficult to anticipate precisely, and unable to wait without creating significant consequences for your household.
How Emergency Savings Protect Your Household
Accessible emergency savings create breathing room when ordinary cash flow is disrupted. A reserve can help maintain mortgage or rent payments, keep utilities connected, and cover necessities without immediately turning to credit cards or expensive loans. The U.S. Securities and Exchange Commission encourages setting aside money for unexpected needs. Although savings cannot eliminate financial hardship, they can reduce difficult short-term decisions and protect longer-term goals from being disrupted by a temporary setback.
Understanding the Three-to-Six-Month Savings Rule
The familiar three-to-six-month guideline expresses emergency savings as a multiple of monthly living expenses. The Federal Deposit Insurance Corporation discusses maintaining at least six months of expenses in a federally insured savings product as a general recommendation. The Federal Reserve, meanwhile, uses three months of emergency savings as one measure of household financial resilience. These figures serve different purposes, and neither establishes a universal requirement. Treat the range as a reference point rather than a mandatory financial threshold.
When Three Months Might Be a Reasonable Starting Point
A three-month savings horizon may be worth evaluating when household income is relatively predictable and essential obligations are manageable. Examples include workers with consistent earnings, limited financial dependents, and substantial flexibility to reduce optional spending temporarily. Reliable access to additional household income can also strengthen financial resilience. However, stable employment does not eliminate unexpected risks. Consider whether a shorter reserve would realistically provide enough time to adjust spending and recover from a disruption.
When Six Months or More May Be Worth Considering
A longer savings horizon may provide additional protection when financial risks are harder to predict. Irregular freelance income, seasonal employment, possible layoffs, and extended job searches can increase the time a household must rely on reserves. Supporting children or other dependents may also limit spending flexibility. Homeownership and substantial unavoidable expenses introduce further uncertainty. In these circumstances, evaluating six months or more of essential expenses can help account for prolonged disruptions or overlapping emergencies.
How to Identify Your Essential Monthly Expenses
Start by reviewing recent statements and identifying costs your household must continue paying during an income interruption. Include rent or mortgage payments, basic groceries, utilities, insurance premiums, necessary transportation, medications, and required debt payments. Account for essential expenses billed quarterly or annually by dividing their yearly totals by 12. Use realistic amounts rather than unusually low estimates. The result should represent a sustainable monthly survival budget that preserves basic living conditions without unnecessary purchases.
Fixed Expenses Versus Flexible Spending
Fixed expenses generally remain consistent from month to month, such as rent, loan payments, and certain insurance premiums. Flexible expenses vary, including restaurant meals, entertainment, shopping, and some grocery purchases. However, not every variable expense is optional: food and necessary transportation remain essential even when their costs fluctuate. Categorize spending by whether it can safely be reduced or postponed during hardship. This distinction helps establish a realistic emergency budget without cutting necessities simply because their amounts change.
How to Calculate Your Emergency Fund Target
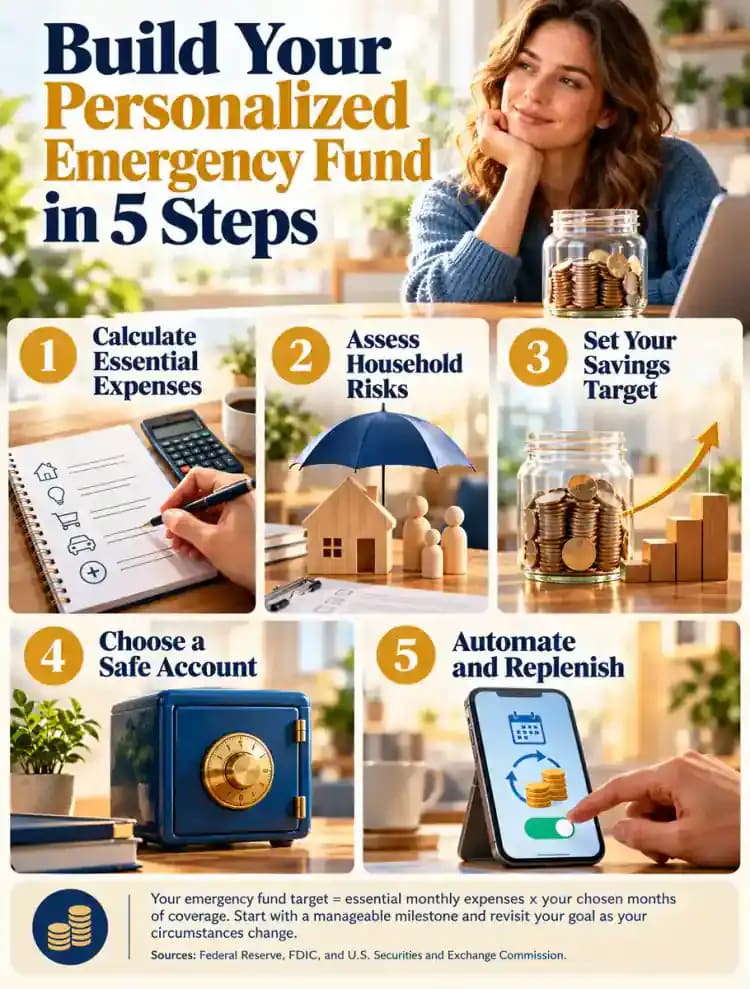
Calculate your target by multiplying essential monthly expenses by your chosen months of coverage. For example, if necessary household costs total $2,500 monthly, three months equals $7,500, six months equals $15,000, and nine months equals $22,500. Next, subtract money already designated for emergencies to identify the remaining savings gap. With $4,000 saved toward a $15,000 target, that gap is $11,000. These figures are illustrative, and your calculation should reflect your actual costs and circumstances.
Example Emergency Fund Targets for Different Budgets
Emergency savings goals change significantly with household expenses. For a household spending $1,500 monthly on necessities, three, six, and nine months of coverage equal $4,500, $9,000, and $13,500. At $3,000 monthly, those targets become $9,000, $18,000, and $27,000. A household requiring $4,500 monthly would need $13,500, $27,000, or $40,500. These illustrative comparisons show why identical coverage periods produce different dollar amounts. Higher essential costs require larger reserves even when the savings timeline stays unchanged.
How Job Security Changes Your Savings Needs
Employment stability affects how long emergency savings might need to replace lost income. Consider your industry's hiring conditions, employer stability, professional specialization, and likelihood of layoffs. Replacement-job timelines can vary considerably between occupations and economic cycles. A highly specialized worker may face a longer search than someone with widely transferable skills. Review how long comparable job searches typically take, while recognizing that past hiring patterns cannot guarantee future employment opportunities or income continuity.
Emergency Savings for Freelancers and Self-Employed Workers
Freelancers and self-employed workers often face irregular payment schedules, seasonal demand, and unexpected gaps between contracts. Reviewing income across an entire year can reveal patterns that a single strong month might hide. Personal emergency savings should also remain separate from business operating reserves used for expenses such as software, inventory, and contractor payments. Distinguishing these purposes helps prevent business obligations from consuming household protection during periods when client revenue temporarily declines or payments arrive late.
How Dependents Affect Your Financial Buffer
Supporting children, aging parents, or other dependents can increase the financial consequences of an income interruption. Childcare payments, essential school expenses, medications, and ongoing support obligations may continue even when earnings decline. Some families also have limited opportunities to reduce working hours or relocate to lower-cost housing. Consider which dependent-related expenses are unavoidable and whether alternative caregivers or assistance are available. These responsibilities can make additional emergency savings particularly valuable during prolonged financial uncertainty.
Extra Savings Considerations for Homeowners
Homeownership introduces expenses that renters may not face directly, including urgent roof repairs, plumbing failures, and replacement of essential heating or cooling equipment. Insurance can reduce certain covered losses, but deductibles, exclusions, and claim processing delays may still leave substantial immediate costs. Routine maintenance deserves its own budget because it is predictable over time. Emergency savings provide additional protection when sudden damage or equipment failure creates an essential expense that cannot reasonably be postponed.
How Health and Insurance Costs Influence Your Target
Healthcare expenses can create financial pressure even for households with insurance coverage. Deductibles, copayments, coinsurance, uncovered treatments, and prescription costs may require payments beyond ordinary monthly premiums. Reviewing plan documents can help identify potential out-of-pocket exposure, including applicable annual maximums for covered services. Necessary ongoing medical expenses should also be considered when assessing household obligations. Because insurance terms and healthcare needs vary, these figures provide planning context rather than a prediction of future medical bills.
Assessing Risk When Your Household Has Two Incomes
Two incomes can provide financial resilience, but their protective value depends on how independently they operate. If either paycheck can cover essential expenses, losing one income may be more manageable. However, partners employed by the same company or within closely related industries could face simultaneous disruptions. Compare necessary household costs against each income separately. Also consider whether losing one job would increase childcare or transportation expenses. Multiple paychecks offer diversification, but they do not eliminate financial risk.
Avoiding Both Undersaving and Excess Cash
An emergency fund should balance financial protection against the opportunity cost of holding cash. Saving too little can increase reliance on borrowing or force investments to be sold during unfavorable market conditions. Holding substantially more than necessary in low-yield accounts, however, may limit progress toward other financial goals. The U.S. Securities and Exchange Commission emphasizes preparing for unexpected expenses while considering broader savings objectives. A defined household safety margin helps evaluate these competing priorities without assuming one balance suits everyone.
Choosing a Safe Place for Emergency Savings
Emergency savings generally prioritize safety and dependable access over maximum investment returns. Evaluate whether an account preserves deposited principal, allows withdrawals when needed, and clearly discloses fees or access restrictions. Federally insured deposit products are commonly used for this purpose. Stocks and other market investments can fluctuate sharply, potentially losing value during an emergency. The Federal Deposit Insurance Corporation recommends federally insured savings products for unexpected expenses. Compare practical access arrangements before choosing where to maintain your reserve.
FDIC and NCUA Insurance Explained
The Federal Deposit Insurance Corporation insures qualifying deposits at FDIC-insured banks, while the National Credit Union Administration provides federal share insurance at federally insured credit unions. Standard coverage is generally $250,000 per depositor, per insured institution, per ownership category. Eligible checking accounts, savings accounts, and certificates of deposit can qualify. Coverage depends on account ownership and institution status, not simply the account name. Verify participating institutions and applicable limits directly with the FDIC or NCUA before assuming deposits are protected.
Are High-Yield Savings Accounts Good for Emergencies?
High-yield savings accounts can offer competitive interest earnings while keeping emergency money accessible. However, annual percentage yields are variable and may decrease without advance notice. Compare transfer processing times, minimum balance requirements, maintenance fees, and withdrawal policies before opening an account. Confirm that the institution provides FDIC or NCUA insurance for eligible deposits. An attractive interest rate matters, but dependable access and minimal fees are equally important when evaluating where to hold emergency savings.
Checking Accounts Versus Savings Accounts
Checking accounts generally make everyday payments convenient through debit cards, electronic transfers, and bill payment services. Savings accounts create separation from routine spending and may provide higher interest earnings. However, some savings products impose transaction restrictions or require additional time for transfers. Checking accounts may also charge maintenance or overdraft fees. Consider how quickly funds must become available and whether keeping emergency money separate from daily purchases would make the reserve easier to preserve.
Should Emergency Savings Go Into CDs?
Certificates of deposit, commonly called CDs, may offer predictable interest rates over specified terms, making them useful for certain cash reserves. However, traditional CDs generally impose penalties when funds are withdrawn before maturity. Some institutions offer no-penalty CDs with different rates or conditions. The Federal Deposit Insurance Corporation recognizes federally insured CDs as a potential savings vehicle. Compare maturity dates, withdrawal provisions, and interest earnings carefully, especially when emergency expenses might require immediate access to cash.
Splitting Your Fund Between Immediate Cash and Reserves
A layered emergency fund separates money needed immediately from reserves that can tolerate modest withdrawal delays. One portion might remain in an accessible checking or savings account for urgent bills, while another stays in a separate insured savings product. Some households also consider CDs for less immediate needs. Before dividing funds, evaluate transfer timing, account restrictions, and possible penalties. The arrangement should preserve access to sufficient cash without requiring complicated transactions during stressful circumstances.
How to Start an Emergency Fund With Limited Income
Building emergency savings on a tight budget can begin with achievable milestones rather than a large final target. An initial goal of $100, $250, or $500 may help establish momentum, depending on available income. Review recurring expenses for manageable reductions without sacrificing necessities. Even occasional small contributions can gradually increase protection. If monthly cash flow is already insufficient for essential bills, addressing immediate obligations takes priority. Progress should remain sustainable rather than creating additional financial strain.
Automating Savings Without Straining Your Budget
Automatic transfers can turn emergency saving into a consistent habit without requiring repeated decisions. The Federal Deposit Insurance Corporation highlights regular automated deposits as a practical savings strategy. Scheduling transfers shortly after payday may help, provided enough money remains for upcoming bills. Start with a contribution your budget can reliably support, then adjust it as circumstances change. Check account balances regularly and understand transfer cancellation deadlines to avoid overdrafts or other unnecessary banking fees.
Using Tax Refunds, Bonuses, and Other Windfalls
Occasional windfalls can accelerate emergency savings without increasing regular monthly commitments. Examples include tax refunds, workplace bonuses, monetary gifts, and unexpected reimbursements. Rather than assuming these payments will arrive, treat them as optional opportunities when they become available. Consider allocating a portion toward your reserve while accounting for existing obligations. The Federal Deposit Insurance Corporation identifies windfalls as a practical way to strengthen savings. Their irregular nature makes them helpful supplements, not dependable substitutes for recurring contributions.
Balancing Emergency Savings With Debt Repayment
Emergency savings and debt repayment compete for limited household cash, but both support financial stability. A modest reserve may reduce the need to borrow when surprise expenses occur, while paying expensive debt can lower future interest costs. Required minimum payments remain important regardless of savings goals. Compare borrowing rates, payment obligations, available cash, and potential penalties before allocating extra funds. There is no universal split that works for every household or financial circumstance.
When to Use Your Emergency Fund and How to Refill It
Emergency savings are intended for unexpected, necessary expenses that cannot reasonably wait. Before withdrawing money, consider whether the cost threatens essential household stability and whether another designated budget category applies. Record the withdrawal and its purpose to maintain an accurate balance. Afterward, establish a realistic replenishment schedule using affordable contributions. Avoid treating legitimate emergency spending as failure. The reserve fulfilled its purpose, and rebuilding it gradually helps restore protection against future disruptions.
Your Personal Emergency Savings Action Plan
Turn emergency savings planning into a manageable routine. Calculate essential monthly expenses, assess household financial risks, and choose a realistic coverage period. Multiply expenses by that period to establish your target, then subtract existing reserves. Select an accessible, federally insured account and arrange affordable recurring contributions. Review progress periodically and revisit your goal after major income or household changes. The U.S. Securities and Exchange Commission encourages preparing for unexpected costs as part of responsible financial planning.
How much emergency savings do you really need? You've probably heard the familiar advice: save three to six months of living expenses. It's a useful starting point, but your ideal emergency fund depends on more than a universal rule.
Consider two households with identical monthly expenses. One has two reliable incomes, few dependents, and relatively predictable bills. The other relies on freelance work, supports children, and owns an older home. Their expenses might look similar on paper, but their financial risks are very different.
Emergency savings provide money for unexpected setbacks, including job loss, urgent repairs, medical bills, and temporary income interruptions. Without accessible cash, even a manageable surprise can create pressure to borrow or postpone essential payments.
The need is widespread. According to the Federal Reserve's May 2025 report on the economic well-being of U.S. households in 2024, only 55% of adults reported having emergency savings sufficient for three months of expenses. The Federal Reserve's May 2026 report found the same percentage for 2025.
The Federal Deposit Insurance Corporation (FDIC) highlights six months of living expenses as a common savings recommendation. However, that benchmark works best when adjusted for your household's actual obligations, income reliability, and exposure to unexpected costs.
This guide explains how to calculate your essential monthly expenses, choose a realistic savings target, compare federally insured accounts, and gradually build your reserve through automatic contributions and occasional windfalls.
The goal isn't to accumulate the largest possible cash balance. It's to build a practical financial cushion that supports everyday stability without overlooking your other financial priorities.
Where people go wrong
Treating Three to Six Months as a Universal Requirement. A standard savings range doesn't reflect every household's circumstances. Someone with unpredictable income or significant family obligations may need more protection, while a household with reliable income and flexible expenses may reasonably evaluate a smaller reserve.
Calculating Savings From Income Instead of Essential Expenses. Emergency savings targets should generally reflect the cost of maintaining necessary household obligations, not simply replacing every dollar of normal income. Include housing, food, insurance, transportation, and required payments while separating discretionary purchases that could temporarily stop.
Ignoring Job Stability and Income Volatility. A stable monthly paycheck and irregular freelance earnings create different financial risks. Choosing a target without considering employment uncertainty, possible job search duration, or seasonal income changes can leave a household with less protection than its circumstances require.
Keeping Emergency Money in Risky Investments. Stocks and other market investments can lose value just when emergency cash is needed. Although investments may serve longer-term goals, emergency reserves generally prioritize principal preservation and reliable access through appropriate, federally insured deposit accounts.
Locking Every Dollar Into Certificates of Deposit. Certificates of deposit can offer competitive interest rates, but traditional CDs commonly charge penalties for early withdrawals. Holding an entire emergency fund in restricted accounts may create inconvenient delays or expenses when an urgent bill arrives.
Saving Only Whatever Remains at Month's End. An unpredictable leftover amount makes progress difficult to maintain. Scheduling manageable transfers around payday can establish a more consistent habit, while leaving sufficient checking-account funds for bills helps avoid overdrafts and unnecessary financial stress.
Using Emergency Savings for Predictable Purchases. Annual insurance premiums, routine maintenance, holidays, and planned vacations should generally have separate budget categories. Repeatedly spending emergency reserves on foreseeable expenses weakens the financial buffer intended to handle genuine disruptions and unexpected essential costs.
Questions people ask
Three to six months of essential living expenses is a common starting range, while the FDIC discusses at least six months as a general recommendation. Your appropriate target depends on income reliability, household obligations, dependents, and other financial risks. Calculate your essential monthly costs before selecting a savings amount.
Fixed it?
Get one guide like this every Thursday.