The Home Buying Closing Process: Your Complete Guide to the Final 30 Days
Buying a home? Learn what happens during the final 30 days before closing, how to review your Closing Disclosure, calculate closing costs, understand escrow, avoid wire fraud, and prepare for closing day.
What you’ll need
Tap to tick things off before you start.
Understand What Happens During the Final 30 Days
The final month before closing is primarily about confirming that the property, financing, and purchase agreement are ready to be completed.
Your lender finishes underwriting, the title company investigates ownership, and your closing agent coordinates documents and money transfers. Your real estate agent may also manage remaining contractual deadlines.
A typical transaction involves several organizations performing different responsibilities. Nobody should assume that another participant has verified every detail.
Begin by requesting a written closing schedule and identifying the person responsible for each outstanding requirement.
Create Your Home Closing Timeline
Organize the remaining work into four approximate periods:
- Days 30-21: Confirm financing, inspection issues, insurance, and title progress. - Days 20-11: Respond to underwriting requests and resolve outstanding conditions. - Days 10-4: Confirm the signing appointment, review projected costs, and prepare funds. - Final three business days: Review the Closing Disclosure, verify payment instructions, and resolve discrepancies.
These are planning milestones, not mandatory legal deadlines. Your purchase contract and lender determine the actual schedule.
Keep one shared checklist so outstanding tasks cannot disappear between email conversations.
Identify Everyone Involved in Closing
Your lender provides financing and prepares mortgage disclosures. The settlement or closing agent coordinates signing, collects funds, and handles disbursements. A title company may examine ownership records and arrange title insurance.
Your real estate agent helps coordinate the purchase agreement and final walkthrough. In some states, a real estate attorney performs additional closing responsibilities.
Ask who will provide your final cash-to-close figure, who controls payment instructions, and who can explain title-related questions. Having clear contacts prevents confusion when deadlines become urgent.
Keep Your Financial Profile Stable
A mortgage approval may still have conditions attached. Your lender can recheck credit information, employment, assets, or liabilities before closing.
Avoid opening unnecessary new credit accounts, making major financed purchases, or changing how your closing funds are held without discussing the consequences with your lender.
A new car loan, for example, could change your debt-to-income ratio and affect qualification.
This does not mean every financial change automatically cancels approval. It means unexpected changes can require additional review, documentation, or underwriting decisions.
Respond Promptly to Underwriting Requests
During final underwriting, your lender may request updated pay stubs, bank statements, employment verification, or documentation explaining large deposits.
Provide accurate, complete information through the lender's approved secure channel. Do not send sensitive financial documents to an unfamiliar email address simply because a message appears urgent.
Ask whether the requested documents satisfy the remaining conditions and whether any additional approval is required.
A conditional approval is not necessarily the same as authorization to fund the mortgage. Confirm your actual loan status directly with your lender.
Confirm Appraisal and Property Requirements
Most financed purchases require the lender to evaluate the property as collateral. An appraisal may be part of that process.
If the appraised value is below the agreed purchase price, financing or contract decisions may need to be revisited. Potential responses depend on the loan program, available cash, and purchase agreement.
Separately, check whether inspection negotiations or agreed repairs remain unfinished.
An appraisal primarily serves the lender's valuation needs. It does not replace an independent home inspection or guarantee that the property is free from defects.
Review the Title Search and Ownership Details
A title search investigates public records connected to property ownership. Potential concerns include liens, unresolved judgments, recording errors, and certain competing ownership claims.
The settlement or title professional should explain any unresolved issue affecting the proposed transfer.
Also confirm the buyer names, property address, and legal description appearing in the relevant documents.
Title insurance is a separate subject worth understanding. A lender's title policy generally protects the lender's covered interest, while an owner's policy addresses covered owner-related risks subject to exclusions and policy terms.
Arrange Homeowners Insurance
Mortgage lenders commonly require acceptable homeowners insurance before funding a home purchase.
Compare coverage terms, deductibles, exclusions, and effective dates. Confirm that the lender receives the necessary evidence of coverage.
Standard homeowners policies generally do not cover flood damage, so additional coverage may be appropriate or required for some properties.
Your first insurance premium may be paid before closing or collected as part of settlement arrangements. Check the Closing Disclosure to avoid overlooking an expense or mistaking a prepaid premium for an escrow deposit.
Understand the Five-Page Closing Disclosure
The Closing Disclosure presents important final information about your mortgage and settlement costs.
Its five pages cover loan terms and projected payments, closing costs, the cash-to-close calculation, additional loan disclosures, and other details about the transaction.
Review the entire document instead of focusing only on the amount you must bring to closing.
The Consumer Financial Protection Bureau, or CFPB, provides explanations of mortgage closing forms through its Buying a House resources.
The form is designed to help borrowers understand the financial obligation before legally committing to the loan.
Know the Three-Business-Day Disclosure Rule
For most mortgages covered by the federal integrated disclosure rules, the lender must ensure you receive the Closing Disclosure at least three business days before consummation, when you become legally obligated on the loan.
For this waiting-period calculation, Saturdays generally count, while Sundays and federal legal public holidays do not.
Delivery and receipt rules matter, particularly when disclosures are mailed or transmitted electronically.
The waiting period is not an automatic right to cancel a home purchase after signing.
If timing is uncertain, ask your lender to confirm the earliest permitted signing date under the applicable rules.
Compare Your Loan Estimate and Closing Disclosure
Place your original or most relevant revised Loan Estimate beside your Closing Disclosure.
Compare the loan amount, interest rate, projected payment, mortgage insurance, lender fees, and estimated funds required at closing.
Some legitimate charges can change because of updated property taxes, insurance quotes, prepaid interest, or choices of settlement services.
Other charges face specific federal limitations on increases, depending on their classification and circumstances.
Do not assume that every increase is illegal or that every increase is acceptable. Request an itemized explanation whenever the numbers differ materially.
Verify Your Mortgage Interest Rate and APR
Your interest rate helps determine the interest charged on your outstanding loan balance. The annual percentage rate, or APR, incorporates the interest rate and certain additional borrowing costs under applicable disclosure rules.
The APR is therefore generally different from the note rate.
Check whether the loan has a fixed or adjustable interest rate, and review any applicable adjustment provisions.
If you expected a fixed-rate mortgage but see adjustable-rate terms, raise the discrepancy immediately.
A seemingly small percentage difference can affect borrowing costs substantially over a long repayment period.
Examine Your Projected Monthly Mortgage Payment
Review the payment table carefully. Your housing payment may include principal, interest, property taxes, homeowners insurance, and mortgage insurance where applicable.
For example, a hypothetical payment might consist of $1,700 in principal and interest, $350 in property taxes, and $150 in insurance, totaling $2,200 per month.
These figures are illustrative, not market estimates.
Taxes, insurance premiums, and escrow contributions may change over time, even with a fixed interest rate.
Your budget should also account for utilities, maintenance, association dues, and repairs that may not appear in the mortgage payment.
Review Loan Terms and Potential Penalties
Confirm the loan term, payment structure, and whether any unusual features appear in your documents.
Review disclosures about possible balloon payments, negative amortization, adjustable-rate changes, and prepayment penalties where relevant.
A prepayment penalty can impose a charge under specified conditions if a borrower pays off a covered loan early.
Not every mortgage includes these features, and applicable restrictions differ by loan type and regulation.
If you discover an unexpected feature, ask your lender for a written explanation before signing. Verify that the actual loan agreement matches the structure you selected.
Break Down Your Mortgage Closing Costs
Closing costs may include lender origination charges, appraisal fees, title services, recording charges, prepaid insurance, and other transaction expenses.
As a broad planning convention, buyers sometimes budget around 2% to 5% of the purchase price, excluding the down payment. Actual charges can fall outside that range.
For a $350,000 home, the illustrative range would be $7,000 to $17,500.
Your actual Closing Disclosure, not a percentage estimate, determines the amount shown for your transaction.
Distinguish charges for services from prepaid items and escrow funding rather than treating them all as identical fees.
Understand Cash to Close
Cash to close is the calculated amount you need to provide at settlement after accounting for relevant payments and credits.
It is not simply the down payment plus an advertised estimate of closing costs.
For example, imagine a $350,000 purchase with a $35,000 down payment and $10,000 in buyer closing expenses. If the buyer already paid $5,000 in earnest money and receives a $3,000 seller credit, the simplified cash-to-close calculation is $37,000.
Real disclosures may include additional prorations and adjustments. Always use the verified final amount supplied through your closing team.
Understand Your Mortgage Escrow Account
An escrow or impound account helps pay certain recurring property expenses, commonly property taxes and homeowners insurance.
A mortgage servicer collects money through your monthly payment, holds it in the account, and pays covered bills as they become due.
The CFPB explains this arrangement in its guide to escrow and impound accounts.
This mortgage escrow account differs from the temporary settlement arrangements used to handle purchase funds.
Not all mortgages require escrow, and the expenses included can depend on the loan and applicable rules.
Check the Initial Escrow Deposit
Your lender may require an initial escrow deposit at closing to establish enough reserves for upcoming eligible expenses.
The amount depends on factors such as property tax schedules, insurance due dates, existing prepaid amounts, and applicable escrow rules.
For example, if annual property taxes are $4,800, a simplified monthly collection for taxes would be $400 before accounting for timing and adjustments.
That calculation does not establish the legally permitted initial deposit.
Ask for the initial escrow account statement and an explanation of how the required amount was calculated.
Prepare for Future Escrow Changes
An escrow account does not freeze your property taxes or homeowners insurance costs.
If those expenses increase, your mortgage servicer may adjust the escrow portion of your monthly payment following the applicable review process.
An escrow shortage may also require additional payments or a repayment arrangement, depending on the circumstances.
Review the annual escrow account statement and contact the servicer about unexplained changes.
Build some flexibility into your homeownership budget rather than assuming your total mortgage payment will remain unchanged indefinitely.
Confirm the Source of Your Closing Funds
Before moving money, confirm that funds are available and properly documented.
Mortgage lenders may need to verify where a down payment originated, especially when funds come from gifts, transfers between accounts, or unusual deposits.
A legitimate gift may require additional paperwork under the lender's loan program.
Avoid moving money through unnecessary accounts shortly before closing, because that can complicate verification.
Also confirm that funds are sufficiently accessible for your settlement date. A pending deposit or recently initiated transfer may not be available when required.
Check Your Bank's Wire Transfer Procedures
Ask your bank whether an outgoing wire must be initiated in person, online, or through another approved method.
Check daily limits, identity verification requirements, wire fees, and processing cutoff times.
Some banks require additional authorization for large transfers, while others impose restrictions on newly added recipients.
Never assume a transfer will arrive immediately because your banking application displays a successful submission.
Coordinate timing with the closing agent and allow for appropriate processing time, while following your bank's security procedures.
Recognize Mortgage Closing Wire Fraud
Mortgage closing fraud often involves criminals impersonating lenders, agents, attorneys, or settlement companies.
A fraudulent message may claim that payment instructions have changed or that funds must be transferred urgently to prevent a canceled closing.
Some criminals compromise genuine email accounts or imitate familiar addresses, making messages appear authentic.
The CFPB specifically warns buyers about these risks in its guidance on closing with confidence.
Treat unexpected changes to wire instructions as a serious warning sign, even when the message includes accurate information about your purchase.
Verify Every Wire Instruction Independently
Before authorizing payment, call your closing company using a phone number independently verified before receiving the payment request.
Do not use the phone number contained in a suspicious email, attachment, or unexpected text message.
Confirm the receiving bank, beneficiary identity, routing number, account number, and payment amount using the closing company's established procedures.
If the closing company reports a last-minute account change, stop and complete an additional independent verification.
A familiar-looking email address is not proof that payment instructions are legitimate. Never authorize a substantial transfer based only on an electronic message.
Act Immediately if You Suspect Wire Fraud
If you believe closing funds were sent to a fraudulent account, contact your sending bank's fraud department immediately.
Request a wire recall or other available recovery action and provide the transaction details. Recovery is uncertain, and delays can reduce the chances of success.
Notify the legitimate settlement company through a verified contact method.
Report suspected fraud to the FBI's Internet Crime Complaint Center and follow instructions from your bank and relevant authorities.
Preserve emails, payment confirmations, account details, and communication records. Do not send additional funds to anyone promising guaranteed recovery.
Schedule and Complete Your Final Walkthrough
Buyers commonly perform a final walkthrough shortly before settlement, according to their purchase agreement and local practice.
Check whether agreed repairs were completed, whether included fixtures remain, and whether the property's condition matches contractual expectations.
Test accessible appliances and basic systems where practical, and look for newly visible damage.
The walkthrough is not a substitute for the original home inspection. It is a final opportunity to identify concerns before ownership changes.
If you discover a problem, notify your real estate agent or attorney before signing rather than assuming it can be resolved afterward.
Review Last-Minute Disclosure Changes
A revised Closing Disclosure does not always require another three-business-day waiting period.
Under CFPB rules, a new waiting period is generally required when a correction makes the disclosed APR inaccurate beyond applicable tolerances, changes the disclosed loan product, or adds a prepayment penalty.
Other changes may require a corrected disclosure without restarting the full waiting period.
See the CFPB's TILA-RESPA Integrated Disclosure FAQs for the regulatory distinctions.
Ask your lender which rule applies before relying on an unchanged signing date.
Prepare for Your Closing Appointment
Confirm the appointment time, location, required identification, and whether signatures will be completed in person, remotely, or through an approved combination of methods.
Ask whether additional documents or payment confirmations are needed.
Review the documents you can obtain in advance and write down questions about unfamiliar language or charges.
Do not assume the appointment will take only a few minutes. Complex transactions may involve numerous documents and additional explanations.
If a significant term cannot be explained or does not match your understanding, request clarification before providing your signature.
Understand the Documents You Sign
Common closing documents include the promissory note, security instrument such as a mortgage or deed of trust, Closing Disclosure, and various settlement or lender forms.
The promissory note establishes your promise to repay the loan according to its terms. The security instrument provides the lender with specified rights concerning the property.
Other documents may address occupancy, escrow, insurance, or identity verification.
Read important provisions and request explanations when necessary.
Signing a standard home purchase mortgage generally does not provide the same federal three-day rescission right available for certain refinance or home-equity transactions.
Confirm Funding, Recording, and Key Release
Signing documents does not necessarily mean that every closing activity is complete.
The lender may still need to authorize funding, the settlement agent may need to disburse money, and the deed may require delivery and recording under applicable procedures.
The precise moment ownership transfers depends on state law and the transaction documents. Key delivery also follows local practice and contractual arrangements.
Ask your closing agent to confirm when the transaction is complete and when you are authorized to take possession.
Keep your final settlement documents and payment confirmations in a secure location.
Set Up Your Finances for Homeownership
After closing, confirm the identity of your mortgage servicer, first payment date, and approved payment methods.
Keep enough cash available for moving expenses, utilities, maintenance, and unexpected repairs.
Review future mortgage statements and annual escrow information so changing taxes or insurance costs do not catch you by surprise.
Store your Closing Disclosure, note, insurance records, title policy, and other important documents securely.
The CFPB's broader home closing guidance reinforces the importance of careful preparation and asking questions.
Successful homeownership requires ongoing financial management after the closing appointment.
You've found a house, negotiated an offer, and secured mortgage financing. Now comes the home buying closing process - the final stretch between having an accepted purchase agreement and becoming a homeowner.
For many first-time buyers, these last 30 days feel more complicated than finding the house itself. Your lender is checking financial documents, the title company is investigating ownership, insurance arrangements must be completed, and thousands of dollars may need to move between bank accounts.
One of the most important documents you'll receive is the Closing Disclosure, a standardized five-page form showing the final details of your mortgage. For most covered mortgage transactions, federal rules require your lender to ensure you receive it at least three business days before you legally commit to the loan.
This guide explains how to navigate those final weeks, compare your Closing Disclosure with your Loan Estimate, understand escrow deposits, identify unexpected charges, and protect your closing funds from wire transfer scams.
What you'll accomplish: You'll build a practical closing timeline, understand the money involved, and know which questions to ask before signing legally binding paperwork.
The timeline is illustrative rather than guaranteed. A closing may take fewer or more than 30 days, and procedures vary by state, loan type, contract, and settlement provider. This guide focuses on a typical financed home purchase in the United States, not a refinance or cash purchase. It provides general financial education rather than individualized financial, legal, or tax advice.
Where people go wrong
Not Reading the Closing Disclosure. Some buyers concentrate on moving plans and assume their lender has already verified every financial detail. Review all five pages, compare important terms with your Loan Estimate, and request explanations for discrepancies before signing.
Assuming the Initial Loan Estimate Is the Final Price. Property tax adjustments, insurance costs, prepaid items, and certain settlement charges can change. Verify the final amounts and distinguish permitted adjustments from charges that require additional explanation.
Making Major Credit Purchases Before Closing. Financing a car or opening a large new credit line may change your debt-to-income ratio or require another underwriting review. Discuss significant financial changes with your lender before making commitments.
Confusing Down Payment With Cash to Close. The amount due at closing includes multiple adjustments and credits. Earnest money, seller concessions, prepaid expenses, and closing charges can all affect the final calculation.
Trusting Emailed Wire Instructions. A message may appear to come from a familiar professional while actually directing funds to a criminal account. Verify the receiving account through an independently confirmed phone number before authorizing the transfer.
Forgetting Bank Transfer Limits. Some banks require additional verification or advance arrangements for large wires. Confirm processing deadlines and transfer procedures before your scheduled closing date.
Ignoring Initial Escrow Requirements. Buyers sometimes budget for the down payment and lender fees while overlooking the escrow deposit and prepaid insurance. Review all prepaid and escrow-related amounts and understand their purpose.
Assuming Signing Automatically Means Ownership. The completion of funding, legal transfer, recording, and possession can vary by state and transaction. Obtain confirmation from the closing agent before treating the property as officially yours.
Questions people ask
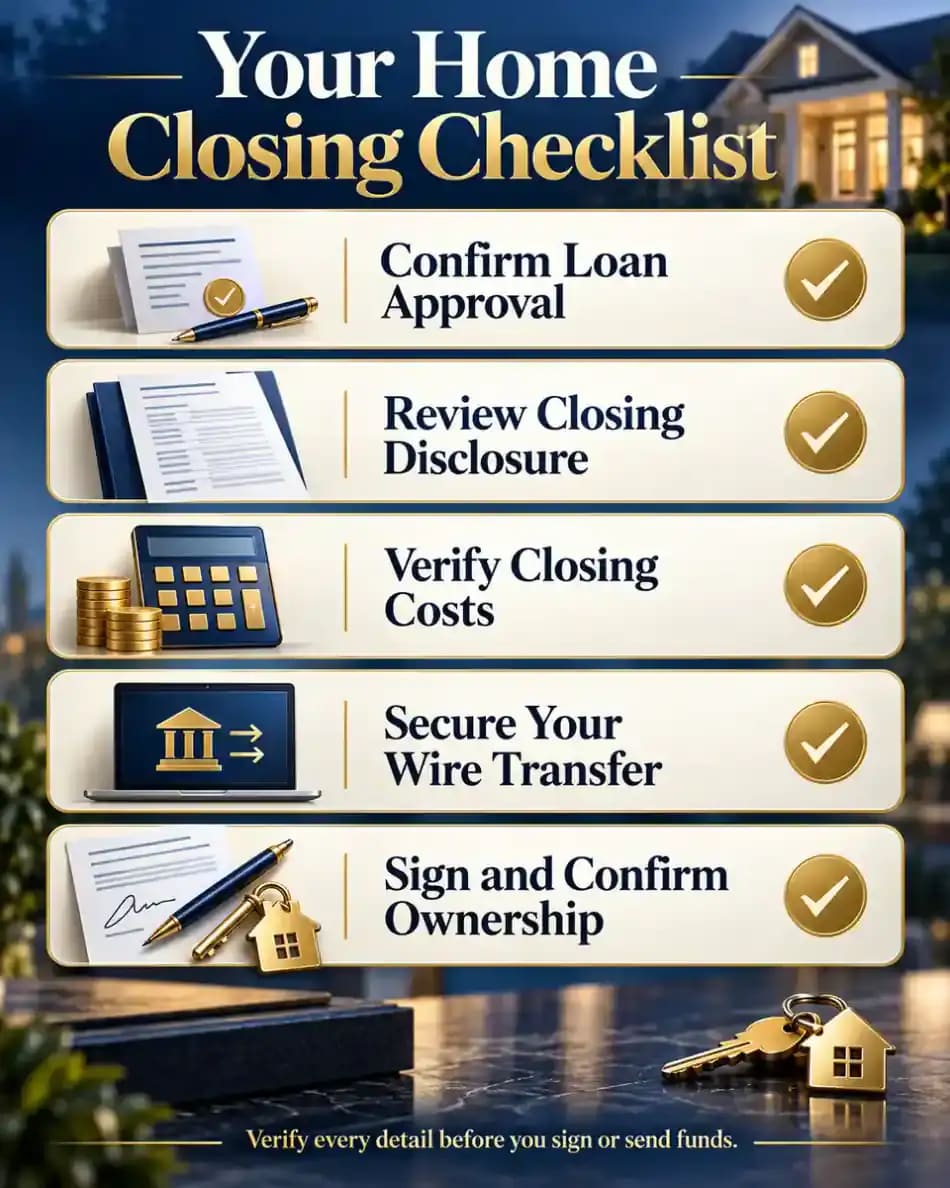
The lender completes remaining underwriting requirements, property and title issues are addressed, insurance is arranged, closing documents are prepared, and the buyer verifies the final financial terms. Funds are transferred and documents are signed according to the scheduled closing process. The exact sequence varies.
Fixed it?
Get one guide like this every Thursday.