The Hidden Costs of Timeshare Contracts Explained
Timeshare ownership can cost far more than the initial purchase price. Learn how maintenance fees rise, why resale can be difficult, how to spot exit scams, and which consumer protection options may help.
What you’ll need
Tap to tick things off before you start.
What Makes Timeshares a Long-Term Commitment
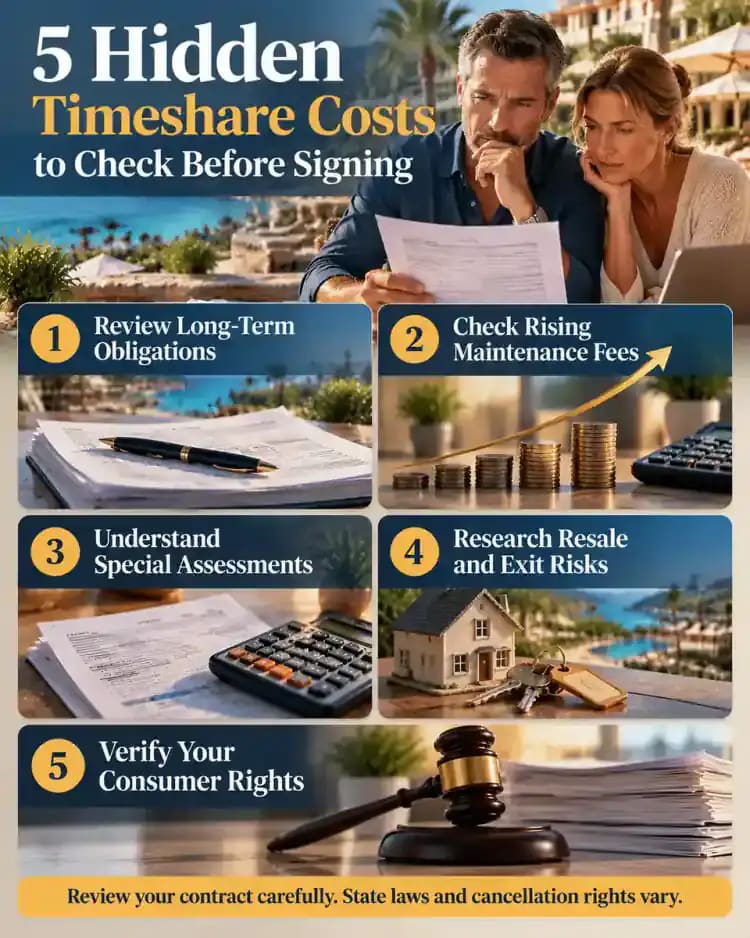
A timeshare offers the right to use a vacation property for a designated period, but the financial commitment can extend well beyond the purchase date. Contracts commonly require owners to pay recurring expenses whether or not they use the resort. Some obligations may continue for the owner's lifetime or raise questions for an estate after death. Before focusing on vacation benefits, examine the contract's duration, ongoing payment requirements, and conditions for ending the agreement.
Deeded Ownership vs. Right-to-Use Contracts
Timeshare agreements generally use one of two structures. A deeded interest typically gives the buyer a legally recorded fractional interest in real estate. A right-to-use contract instead grants permission to use a property or resort network for a defined period, without necessarily conveying real estate ownership. These structures can differ in duration, transfer rules, and legal responsibilities. Read the actual agreement carefully rather than assuming every timeshare provides the same ownership rights or obligations.
Why Maintenance Fees Keep Rising
Maintenance fees help cover resort operations, including landscaping, utilities, insurance, taxes, staffing, and routine upkeep. These expenses can change as labor costs rise, buildings age, and services become more expensive. The resort's governing documents may allow management or an owners' association to adjust fees. Request historical fee statements and review the rules governing increases. A low starting fee does not guarantee that annual ownership expenses will remain affordable over the life of the contract.
Special Assessments and Unexpected Expenses
Regular maintenance fees may not cover every major resort expense. A special assessment is an additional charge that may be imposed for significant repairs, storm damage, infrastructure upgrades, or other capital projects. Depending on the governing documents and applicable rules, owners may be responsible for their allocated share even when the expense was not anticipated at purchase. Ask how assessments are authorized, review recent notices, and check whether planned projects or outstanding repair needs could create additional costs.
The Financial Consequences of Missed Payments
Unpaid timeshare obligations can create consequences beyond the original balance. Depending on the agreement, the type of debt, and applicable law, a resort or creditor may pursue collection, seek foreclosure of a timeshare interest, or report qualifying delinquencies to credit bureaus. The process and consequences vary, so do not assume that ignoring invoices will cancel the contract. Keep notices and account statements, identify the party claiming payment, and seek qualified advice if collection or foreclosure proceedings arise.
Why Timeshares Can Be Difficult to Resell
Selling a timeshare may be harder than selling conventional real estate. Many owners compete for a limited pool of interested buyers, and the resale value can be far below the original purchase price. Some interests attract little demand even when listed at a nominal price. Online asking prices do not prove that similar properties actually sold for those amounts. Research comparable listings, verify completed-sale evidence where available, and account for transfer costs before treating resale as a reliable way to recover your investment.
Recognizing Timeshare Exit and Resale Scams
Owners who want to sell or exit a timeshare can attract companies offering expensive solutions. Warning signs include guaranteed resale or cancellation, pressure to act immediately, vague service agreements, and substantial upfront fees without clear deliverables. Verify the company's identity, investigate its track record independently, and read every contractual term before paying. Be especially cautious when a provider tells you to stop loan or maintenance payments without explaining the potential consequences. The Federal Trade Commission offers consumer guidance about deceptive travel and resale practices.
Using Federal Consumer Protection Resources
Federal agencies can help consumers identify reporting options, although their roles differ. The Consumer Financial Protection Bureau accepts complaints involving covered financial products and services, which may include certain timeshare financing or debt collection disputes. The Federal Trade Commission provides information about deceptive business practices and pursues enforcement actions against unlawful conduct. A complaint does not guarantee reimbursement or contract cancellation. Preserve relevant agreements, statements, and correspondence, then use the agency's official website to determine whether your concern fits its process.
Questions to Ask Before Signing
Before committing, request the current maintenance fee schedule and historical increases, then ask whether the contract limits future increases. Review the financing terms, including the annual percentage rate, repayment period, and additional charges. Identify the applicable cancellation or rescission deadline and the exact notice procedure. Also clarify transfer restrictions, potential costs, and what happens to obligations after death. Ask for important promises in writing and take time to review the complete agreement outside a sales presentation before making a decision.
Planning Your Next Step as a Timeshare Owner
If you already own a timeshare and are considering leaving, begin by gathering the signed agreement, recent invoices, financing records, and correspondence. Identify any cancellation or transfer provisions and verify the current status of your account. Research proposed exit options carefully rather than relying on unsolicited promises. If a deadline is approaching, a creditor has threatened legal action, or the contract's meaning is disputed, consider consulting an attorney familiar with the law governing the property. The appropriate next step depends on your documents and circumstances.
Calculate the True Lifetime Cost
The full cost of a timeshare includes more than the amount paid at signing. To estimate the long-term commitment, combine the purchase price, financing charges, recurring maintenance fees, and any other applicable ownership expenses. Build a year-by-year estimate across several possible ownership periods, such as 10, 20, and 30 years. Clearly separate known contractual charges from uncertain future costs. This approach reveals how a seemingly manageable annual expense can become a substantial cumulative financial commitment.
How Inflation Affects Future Ownership Costs
Inflation can increase the cost of labor, insurance, utilities, supplies, and contracted services that keep a resort operating. As these expenses change, the budget supporting a timeshare property may also change. Even modest annual increases can produce a meaningful difference over many years. Historical fee records provide useful context, but they cannot predict future increases with certainty. When evaluating affordability, consider several possible cost paths instead of assuming today's maintenance fee will remain representative throughout ownership.
Compare Timeshare Costs With Independent Vacations
A useful comparison measures timeshare ownership against the cost of booking similar vacations independently. Include comparable accommodation quality, travel dates, location, transportation, and the number of nights used each year. For ownership, account for the purchase price, financing, recurring fees, assessments, and other charges. For independent travel, use realistic current prices rather than unusually cheap promotional rates. The comparison should reflect how often the owner actually travels and whether the timeshare's booking restrictions fit those habits.
Understand Financing Interest and Loan Terms
Financing can substantially increase the total amount paid for a timeshare. Review the annual percentage rate, repayment term, monthly payment, applicable fees, and total scheduled repayment shown in the loan documents. A lower monthly payment may simply reflect a longer repayment period rather than a cheaper loan. Distinguish the financing obligation from maintenance fees and other resort charges, which may continue after the loan is repaid. The complete financing agreement provides a more reliable picture than a sales presentation alone.
Check Exchange Programs and Booking Restrictions
Exchange programs may let timeshare owners request stays at other properties, but participation does not guarantee availability or equivalent accommodations. Review membership charges, exchange fees, reservation windows, blackout dates, and any limits on destinations or travel periods. Some arrangements may require advance planning or additional payments to access preferred resorts. Before assigning value to exchange privileges, examine the actual terms and determine whether the available options match your travel preferences. Promotional descriptions alone may not explain every practical restriction.
Review Ownership Transfer and Exit Conditions
Transferring a timeshare may involve requirements beyond finding someone willing to accept it. The contract or resort rules may require approval, specific paperwork, administrative payments, or completion of outstanding obligations. A proposed transfer does not necessarily end the original owner's responsibility immediately. Review the process for recording a transfer and determine what documentation confirms that the change is complete. Because rules differ across agreements and jurisdictions, verify the applicable requirements before relying on a transfer as a way to end future ownership costs.
Understand State-Specific Timeshare Laws
Timeshare consumer protections are not identical across the United States. The law governing a property can affect cancellation rights, required notices, transfer procedures, and available remedies. A rescission period may be limited, and the applicable deadline and delivery method must be verified rather than assumed. Contract language and the location of the resort can both matter when determining which rules apply. Consult official state resources or a qualified attorney for jurisdiction-specific questions, particularly when a deadline is approaching or a dispute has developed.
Prepare Evidence for a Financial Complaint
A clear complaint begins with an organized record of what happened. Gather the signed contract, financing documents, billing statements, payment confirmations, relevant advertisements, and correspondence with the resort or lender. Create a dated timeline that distinguishes confirmed facts from estimates or recollections. State the disputed charge or conduct clearly and explain what records support the concern. The Consumer Financial Protection Bureau provides an official complaint process for eligible financial issues. Keep copies of everything submitted and retain any confirmation or response for future reference.
When Professional Legal Advice Is Worthwhile
Some timeshare issues involve legal questions that general consumer information cannot resolve. Examples include disputed contract terms, threatened foreclosure, contested collection claims, complex transfer arrangements, and uncertainty about obligations connected with an estate. A qualified attorney familiar with the property's jurisdiction can review the actual documents and explain the legal issues relevant to the circumstances. Bring contracts, notices, payment records, and prior correspondence to the consultation. Independent advice is especially important when a deadline, formal legal notice, or substantial financial exposure makes delay risky.
Build a Practical Timeshare Decision Checklist
Before committing to a timeshare, bring the key findings together in one written checklist. Record the total purchase and financing costs, current maintenance fees, historical increases, possible assessments, booking restrictions, and transfer conditions. Compare those expenses with realistic vacation alternatives and avoid assuming the interest can be resold easily. Confirm the applicable cancellation rules and identify any unresolved questions that need independent verification. A documented comparison helps distinguish attractive vacation promises from the contractual responsibilities that determine whether ownership fits your long-term plans.
Estimate Future Maintenance Fee Scenarios
A useful budget test compares several possible annual maintenance fee increases rather than relying on a single forecast. Create low, moderate, and high scenarios using clearly stated assumptions, then calculate the cumulative payments over different ownership periods. Keep special assessments separate unless you have a defensible estimate for them. These projections are not predictions, but they show how sensitive the total cost is to annual increases and help reveal whether ownership remains affordable under less favorable conditions.
Understand Resort Management and Owner Oversight
Maintenance budgets are shaped by resort management, governing documents, and, where applicable, an owners' association. These parties may determine operating budgets, authorize certain expenditures, and communicate assessments to owners. Review the agreement to understand how budgets are approved, what financial information owners can access, and whether meetings or voting rights apply. Ask for available budget summaries and assessment explanations when evaluating charges. Knowing how decisions are made helps you understand the process behind ownership expenses without assuming individual owners control every increase.
Check Reservation Availability Before Buying
The practical value of a timeshare depends partly on whether you can reserve the dates you actually want. High-demand holidays, school breaks, and popular seasons may have limited availability or require reservations well in advance. Review booking windows, priority rules, cancellation conditions, and any points-based restrictions before assigning value to promised vacation access. Ask how the reservation process works in practice and what happens when preferred dates are unavailable. A vacation entitlement is less useful when its conditions conflict with your schedule.
Evaluate Contractual Use and Guest Restrictions
A timeshare's usage rules can affect how easily you share or make use of the property. Contracts may set conditions for bringing guests, transferring reservations, renting unused periods, or changing the names on a booking. Some arrangements restrict activities or require advance approval and additional fees. Read the relevant provisions rather than assuming you can use the timeshare like a privately owned vacation home. Clarifying these restrictions before signing helps establish whether the available flexibility matches your intended use.
Recognize Misleading Sales Presentation Tactics
Sales presentations may emphasize luxury amenities, future savings, or offers that appear available only for a short time. Pressure to sign immediately can make it harder to examine the full contract or compare alternatives. Treat verbal assurances as claims to verify, not substitutes for written terms. Request copies of every relevant document and check whether promised benefits, discounts, or cancellation conditions appear in the agreement. The Federal Trade Commission provides consumer information about deceptive business practices and can be a useful resource when evaluating concerning sales conduct.
Keep a Complete Record of Ownership Costs
Maintaining a clear record of ownership expenses makes it easier to understand spending, check billing accuracy, and explain a dispute. Keep maintenance invoices, special assessment notices, financing statements, payment confirmations, and receipts for other contractual charges. Record payment dates and note any differences between amounts billed and amounts paid. Store digital copies securely alongside the original agreement and important correspondence. A consistent record also helps distinguish recurring expenses from one-time charges, making annual budgeting and later reviews more reliable.
Assess Whether Your Vacation Habits Have Changed
A timeshare that once suited your travel routine may become less useful as family needs, work schedules, health, or preferred destinations change. Consider how often you have actually used the property in recent years and whether future travel plans remain compatible with its booking rules. Compare the benefits you receive with the commitment required to maintain ownership. This review is not about past spending alone; it is about whether the arrangement still fits your likely needs and available budget going forward.
Verify Promises About Rental Income
Some owners are told they can rent out unused timeshare periods to recover part of their costs. Actual results depend on rental demand, permitted use, booking availability, platform charges, taxes, and the terms of the agreement. Rental income should not be treated as guaranteed or assumed to cover all maintenance expenses. Check whether rentals are permitted, what approvals may be required, and whether comparable rental opportunities exist. Evaluate any income projection using realistic evidence rather than relying solely on a sales representative's estimate.
Compare Alternatives to Long-Term Vacation Commitments
Timeshare ownership is not the only way to plan recurring vacations. Booking hotels, renting vacation homes, or setting aside money for travel can offer different levels of flexibility and financial commitment. Compare realistic accommodation prices for the destinations and seasons you actually visit, including taxes, cleaning charges, and cancellation terms. Consider how each option handles changing plans and unused vacation time. The purpose is not to assume one method is always cheaper, but to determine which arrangement best balances total cost, flexibility, and travel preferences.
Make a Documented, Informed Ownership Decision
Before buying or pursuing an exit, bring verified information together in a written comparison. Include contractual obligations, estimated long-term costs, reservation restrictions, transfer conditions, and realistic resale expectations. Separate confirmed facts from assumptions and identify any unanswered questions that could materially affect the decision. Independent professional guidance may be appropriate when the agreement or applicable law is unclear. A documented review will not remove every uncertainty, but it can reduce reliance on sales claims and help ensure the decision reflects both the financial commitment and your actual vacation needs.
A timeshare can seem like an affordable way to enjoy regular vacations, but the initial purchase price reveals only part of the financial commitment. Before signing, understand the ongoing expenses, the contract terms, and how difficult it may be to leave the arrangement if your needs change.
Maintenance fees typically cover resort operations, insurance, repairs, taxes, and amenities. These charges can increase over time, and owners may also face special assessments for major repairs or improvements. Financing interest and other contractual charges can further increase the total cost. Request the current fee schedule, historical increases, assessment policies, and any contractual limits on future increases before making a decision.
Resale deserves equal attention. Timeshares can be difficult to sell, and resale prices may fall far below the original purchase price. Do not assume that listing your interest will end your financial obligations. Review transfer requirements and confirm when responsibility for future fees officially ends.
If you already own a timeshare and want to exit, be cautious of companies promising guaranteed cancellation or resale in exchange for large upfront payments. Review your agreement, preserve written communications, and verify any proposed exit provider independently. The Consumer Financial Protection Bureau (CFPB) may help with complaints involving covered financial products and services, including certain financing and debt collection disputes. The Federal Trade Commission (FTC) provides guidance about deceptive business practices and potential scams.
Cancellation rights and timeshare laws vary by state and contract type. If you recently signed, check the applicable rescission deadline immediately because missing it may limit your options. Follow the required cancellation procedure precisely and retain proof of delivery. For complicated disputes, threatened foreclosure, or questions about inherited obligations, consult an attorney familiar with the property's jurisdiction. Careful review before signing is generally easier than trying to unwind a binding agreement later.
Where people go wrong
Focusing Only on the Purchase Price. The initial price excludes years of maintenance fees, possible special assessments, financing interest, and other charges. Estimate the total cost over a realistic holding period before deciding whether the vacation benefits justify the financial commitment.
Assuming Maintenance Fees Will Stay Low. A current fee quote does not establish a reliable long-term cost. Request historical increases, assessment records, and contractual limits. Model several cost scenarios rather than assuming fees will remain stable or rise only with inflation.
Treating a Timeshare Like Traditional Real Estate. Timeshares can have limited resale demand and may lose substantial value after purchase. Do not rely on appreciation or assume you can recover your investment. Research comparable resale listings and remember that asking prices do not establish completed-sale values.
Missing the Rescission Deadline. Some contracts and state laws provide a limited cancellation window with strict notice requirements. Do not assume a phone call is sufficient or that the deadline can be extended. Check the governing rules immediately after signing.
Paying an Exit Company a Large Upfront Fee. Promises of guaranteed cancellation, resale, or debt elimination can be warning signs. Verify the provider's identity, reputation, contract terms, and claims independently. Avoid pressure tactics, and be especially cautious of urgent payment requests.
Stopping Payments Without Understanding the Risks. Abandoning payments may trigger collection activity, credit consequences, or foreclosure, depending on the contract and applicable law. Before withholding payment, obtain advice about your obligations and document any billing dispute or proposed exit arrangement.
Assuming Federal Agencies Can Cancel Any Contract. The CFPB handles complaints involving covered financial products and services, while the FTC addresses deceptive practices and consumer education. Neither agency guarantees contract cancellation. Identify the relevant issue, preserve evidence, and consider state regulators or legal counsel when appropriate.
Questions people ask
Common costs include recurring maintenance fees, special assessments for major repairs or improvements, financing interest, taxes, and contractual transfer or exchange charges. Some fees can increase over time. Review the complete contract and recent statements to identify applicable expenses and determine whether additional assessments may arise.
Fixed it?
Get one guide like this every Thursday.