The Hidden Cost of Low Monthly Auto Loan Payments
A lower car payment can feel like a win, but stretching an auto loan over more years can add thousands of dollars in interest. Learn how loan term, amortization, interest type, add-ons and prepayment rules affect the real cost of financing a vehicle.
What you’ll need
Tap to tick things off before you start.
Start With the Amount You Are Actually Financing
The first number to identify is not the monthly payment. It is the amount financed. A vehicle advertised at one price can result in a larger loan after taxes, registration charges, dealer fees and optional products are added. A down payment or trade-in can reduce the amount borrowed.
This distinction matters because interest is charged on the financed balance according to the terms of the contract. If the amount financed rises, the total interest cost generally rises as well.
Before comparing loan lengths, make sure you are comparing the same amount financed. Otherwise, a lower payment could simply reflect a different loan amount rather than a better financing structure.
Why Monthly Payment Gets So Much Attention
Monthly payment is important because it determines how much money must leave your budget each month. A lower payment can provide breathing room for rent, groceries, insurance, savings and other obligations.
The problem begins when the monthly payment becomes the only comparison point. A lender can often reduce the payment by extending the repayment term. That does not automatically reduce the cost of borrowing. It can simply spread the debt across more months.
A useful question is therefore not only, "Can I afford this payment?" but also, "What is the total cost required to get this payment?"
A 48-Month Versus 72-Month Example
Assume a $30,000 loan at an 8.5% APR. Under the illustrative calculations used here, a 48-month term produces a payment of about $739.45, while a 72-month term produces a payment of about $533.35.
The 72-month option lowers the scheduled monthly payment by $206.10. That is a meaningful cash-flow difference.
However, the lower payment is achieved by keeping the debt outstanding longer. That gives interest more time to accumulate. This is why term length should be viewed as a cost variable, not merely a payment-adjustment tool.
The Lower Payment Is Not the Same as Savings
Saving $206.10 per month in required cash flow is not the same thing as saving money overall. In the example, the 48-month loan generates approximately $5,493.56 in interest. The 72-month loan generates approximately $8,401.31.
That is about $2,907.75 more interest for the longer term.
This is the core distinction consumers should keep in mind. A financing offer can improve short-term affordability while increasing long-term cost. Neither factor should be ignored. The goal is to understand the trade-off before signing.
Look at Total Interest Paid
Total interest is one of the clearest ways to compare similar loan offers. If two loans finance the same amount at the same APR but use different terms, the longer loan usually carries more total interest because the balance remains outstanding for more time.
In the example, the difference is nearly $3,000. That is money paid for financing rather than for the vehicle itself.
When reviewing a loan, ask for or calculate the total scheduled interest and total of payments. These figures make it much harder for an attractive monthly payment to hide an expensive structure.
Understand What APR Tells You
APR is designed to help consumers compare the cost of credit. It is expressed as an annual rate and can incorporate certain finance charges depending on the transaction and disclosure requirements.
APR is valuable, but it should not be viewed in isolation. Two loans with the same APR can have different total interest costs if their terms differ. Likewise, a small change in APR can matter more when the loan balance is large or the term is long.
Compare APR, amount financed, term, monthly payment and total cost together rather than treating any one figure as the complete answer.
Amortization Splits Every Payment
Most installment auto loans are amortizing loans. Each scheduled payment is divided between interest and principal. Interest is the cost of borrowing. Principal is the remaining amount of the loan balance itself.
The CFPB explains that amortization determines how a fixed payment is allocated between interest and principal over time. The split does not usually stay constant from the first payment to the last.
Understanding this allocation helps explain why borrowers can make payments for months and still see a sizable remaining balance.
Early Payments Often Contain More Interest
At the beginning of an amortizing loan, the outstanding principal is at or near its highest level. Because interest is calculated using that balance under common simple-interest structures, a larger dollar amount of interest generally accrues earlier in the loan.
As the principal falls, the interest portion typically decreases and more of the fixed payment can go toward principal.
This does not mean the lender is arbitrarily charging all the interest first. It is a mathematical result of calculating interest on a larger outstanding balance during the earlier months.
Later Payments Shift Toward Principal
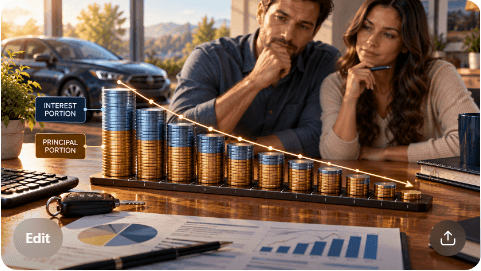
As scheduled payments reduce the balance, the interest calculation applies to a smaller amount. The interest charge generally becomes smaller, which allows more of each fixed payment to reduce principal.
This gradual shift is an important feature of amortization. It also means that the timing of principal reduction can influence future interest under a simple-interest loan.
Borrowers who want to understand their own schedule can request an amortization table from the lender or use a reputable loan calculator, then verify the figures against the contract.
Longer Terms Keep the Balance Alive Longer
A 72-month loan gives the borrower 24 more scheduled payments than a 48-month loan. The lower payment reduces the balance more slowly, so more principal remains outstanding for more time.
That extended exposure to interest is a major reason the total cost rises.
This effect can be especially important on higher-priced vehicles. A difference that seems modest on a monthly basis can compound into thousands of additional dollars over five, six or seven years of repayment.
Long Terms Can Affect Your Financial Flexibility
Total interest is not the only consideration with a long loan. Because the balance may decline slowly, the borrower can remain financially tied to the vehicle for many years.
During that period, life can change. The car may need repairs, driving needs may shift, insurance costs may change, or the owner may want to replace the vehicle before the loan is fully repaid.
A longer term can therefore affect future flexibility even if the payment feels easier today. That is another reason to compare the repayment horizon with how long you realistically expect to keep the vehicle.
Compare the Loan With the Vehicle's Likely Ownership Period
If you expect to own a vehicle for four years but finance it for six or seven years, you could still owe money when you want to sell or trade it.
That does not automatically make the loan inappropriate, but the mismatch deserves attention. The remaining payoff balance becomes part of the next transaction.
Before selecting a long term, compare the loan length with your normal vehicle replacement cycle. A payment that fits today may become less convenient if you decide to change cars before the debt is gone.
Know the Difference Between Simple and Precomputed Interest
The CFPB distinguishes between simple-interest auto loans and loans using precomputed interest. The difference matters because it can affect what happens when you pay more than required or pay off the loan early.
With simple interest, interest generally depends on the outstanding principal balance. With precomputed interest, the financing charge is calculated differently and the effect of early payments can be less straightforward.
Do not assume all auto loans work the same way. Check the contract before planning an accelerated payoff strategy.
How Simple Interest Usually Works
In a simple-interest loan, interest is generally calculated using the outstanding principal balance over a specified period. Depending on the contract, calculations may be based on daily or periodic accrual.
Because future interest depends on the remaining balance, reducing principal sooner can potentially reduce future interest charges.
However, borrowers should still verify how their lender applies payments. Sending extra money does not always guarantee that it is credited to principal exactly the way the borrower expects. The contract and lender procedures control the result.
Extra Payments May Help on Simple-Interest Loans
If a lender properly applies additional funds to principal on a simple-interest auto loan, the lower balance can reduce the amount on which future interest is calculated.
That can shorten the repayment period or reduce total interest, depending on the loan structure and how payments are handled.
Before making extra payments, confirm whether there is a specific principal-only procedure, whether additional funds advance the due date, and how the lender records the transaction. A payment strategy should be based on the actual servicing rules, not an assumption.
Precomputed Interest Works Differently
With precomputed interest, the finance charge is calculated in advance using the contractual method and incorporated into the repayment structure.
Because the interest was determined differently from a standard simple-interest balance calculation, paying ahead may not produce the same savings pattern borrowers expect.
The CFPB recommends checking the contract to determine which interest method applies. If the wording is unclear, ask the lender to explain how an early payoff is calculated and how additional payments affect the amount owed.
Do Not Guess Which Interest Method You Have
Many borrowers know their APR and monthly payment but have never checked how interest is calculated. That missing detail can matter later, particularly if you plan to pay aggressively.
Review the promissory note, retail installment contract and Truth in Lending disclosures. Search for language describing simple interest, daily interest, precomputed finance charges or the treatment of unearned interest.
If anything is unclear, obtain an explanation from the lender before sending a large additional payment or requesting payoff.
Check for Prepayment Penalties
Paying off a loan early sounds straightforward, but some contracts or legal frameworks may affect whether a penalty or fee applies.
The CFPB notes that the ability to prepay an auto loan without penalty depends on the contract and applicable state law. That means a general statement about all auto loans would be unreliable.
Look for a prepayment clause before assuming that an early payoff will be free of additional charges. If a provision appears ambiguous, consider asking the lender or an appropriate professional for clarification.
Read the Truth in Lending Disclosures
Federal credit disclosures are designed to make important loan terms easier to compare. Depending on the transaction, disclosures can show figures such as APR, finance charge, amount financed, total of payments and payment schedule.
These numbers provide a more complete view than the monthly payment alone.
When comparing lenders, place the disclosures side by side. Confirm that the loan amount, term, vehicle and included products are truly comparable. A payment comparison is meaningful only when the underlying deal structure is understood.
Ask for the Payoff Amount Before Acting
The account balance displayed online may not always be identical to the official payoff amount needed to close the loan on a specific date. Accrued interest, fees or administrative timing can affect the figure.
If you are considering a full early payoff, request an official payoff quote and note how long it remains valid.
This is particularly important when refinancing, selling or trading the vehicle, because another transaction may depend on the exact amount required to satisfy the existing lien.
Separate Vehicle Price From Financing Cost
Car negotiations can become confusing when purchase price, trade-in value, financing and add-on products are discussed at the same time.
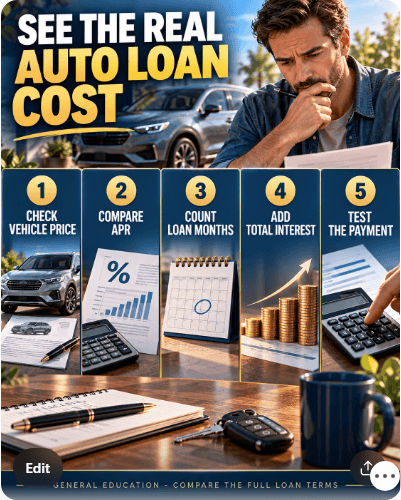
One practical way to understand the deal is to separate the components conceptually. First identify the vehicle price. Then identify the value or payoff of any trade-in. Next identify the amount financed. Finally, evaluate the financing terms.
This structure makes it easier to see whether a low payment came from a better price, a larger down payment, a longer loan, a different APR or additional amounts rolled into financing.
Review Optional Add-On Products
The CFPB notes that a monthly auto loan payment can include amounts related to optional add-on products agreed to in the contract. Examples may include service contracts, extended warranties or GAP products.
When these costs are financed rather than paid separately, they can increase the amount financed. Depending on the loan structure, that can also increase the interest paid over time.
Ask for an itemized list of every product included in the transaction, its price and whether it is financed. Evaluate each product independently instead of judging it solely by how little it changes the monthly payment.
Do Not Judge an Add-On by Its Monthly Cost
A product that adds only $15 or $25 to the monthly payment can appear inexpensive. But multiplied over 60, 72 or 84 months, the total amount can be substantial, especially if the product itself is financed.
Convert add-ons back into total dollars whenever possible. Ask what the product costs in full, whether interest is charged on the financed amount, whether it is optional and what cancellation rules apply.
A small monthly increment can disguise a much larger purchase decision.
Compare Loan Offers on the Same Assumptions
A fair comparison requires consistent inputs. If one lender quotes a 48-month loan and another quotes 72 months, the lower payment does not tell you which offer is less expensive.
Ask each lender for comparable terms where possible. Compare the same amount financed and the same loan duration, then examine APR, payment, fees and total borrowing cost.
You can also compare multiple term lengths from the same lender to understand what you are paying in exchange for monthly flexibility.
Stress-Test the Payment Against Your Budget
A shorter loan may cost less in total interest, but that does not automatically mean its higher required payment fits every household budget.
A useful comparison should include both total cost and resilience. Consider whether the required payment leaves reasonable room for insurance, fuel, maintenance, emergency expenses and other recurring obligations.
The purpose is not to choose the shortest term at any cost. It is to understand the financial price of extending the term and make the trade-off consciously rather than accidentally.
Watch for Payment-First Sales Conversations
If the conversation begins with, "What monthly payment are you looking for?" remember that many combinations of price, down payment, APR and term can produce the same payment.
A target payment can therefore be useful for budgeting but poor as the only negotiating metric.
Keep the vehicle price and financing terms visible. If the payment changes, ask exactly which variable changed. This prevents a longer term or a larger amount financed from quietly creating the appearance of a better deal.
Calculate the Cost of Extending the Term
Whenever you are offered a longer term, calculate two differences: the reduction in the monthly payment and the increase in total interest.
In the $30,000 example at 8.5% APR, moving from 48 to 72 months reduces the payment by $206.10 but increases total interest by about $2,907.75.
Putting both numbers side by side makes the trade-off concrete. You can then decide how much value you place on the extra monthly cash flow relative to the additional lifetime cost.
Verify How Extra Money Will Be Applied
If you plan to pay more than the required amount, contact the lender or check the servicing instructions. Confirm whether additional money reduces principal, advances the next due date, covers accrued interest first, or is handled in another way under the contract.
This operational detail can determine whether your strategy produces the effect you expect.
Keep records of additional payments and review subsequent statements to confirm they were applied correctly.
Review the Entire Contract Before Signing
The final contract controls the legal and financial relationship, not a verbal estimate made earlier in the sales process.
Before signing, review the amount financed, APR, term, payment schedule, finance charge, optional products, interest method and any early payoff provisions. Make sure the contract matches the transaction you intended to accept.
If a term is unfamiliar, ask what it means before signing. Taking additional time to understand the agreement is preferable to discovering an expensive provision after the vehicle has already been purchased.
Use Total Cost and Monthly Affordability Together
The strongest auto loan comparison uses more than one metric. The monthly payment tells you about immediate cash flow. APR helps describe the cost of credit. The loan term shows how long the obligation lasts. Total interest and total payments show what the financing can cost over time.
The CFPB's consumer guidance on amortization, interest methods, monthly payment components and prepayment rules reinforces the importance of reading the complete loan structure rather than focusing on one number.
In the example used throughout this guide, extending a $30,000 loan at 8.5% APR from 48 to 72 months lowers the payment by $206.10 but adds approximately $2,907.75 in interest. Taxes, fees, optional products and possible differences in lender pricing were excluded, so real-world offers can differ materially.
Before committing, compare the same amount financed across multiple terms, understand what is included in the loan, verify how interest is calculated and read the early payoff provisions. A lower payment can be useful, but only when you know exactly what you are paying to obtain it.
A lower monthly car payment can make an expensive vehicle suddenly look manageable. That is exactly why monthly payment is such a powerful number in the car buying process. It affects household cash flow immediately, it is easy to compare, and it can make two very different financing offers appear similar.
But the monthly payment is only one part of the cost.
Consider an illustrative $30,000 auto loan at an 8.5% annual percentage rate, or APR. A 48-month term produces a payment of about $739.45 per month. Stretch the same assumed loan to 72 months and the payment falls to about $533.35. The monthly difference is $206.10.
That lower payment sounds attractive, but it comes with a trade-off. Under these assumptions, the 48-month loan generates about $5,493.56 in total interest, while the 72-month loan generates about $8,401.31. The longer loan therefore costs about $2,907.75 more in interest.
This guide explains why that happens, how amortization works, why the method used to calculate interest matters, what optional products can do to your balance, and what to verify before making extra payments. The Consumer Financial Protection Bureau, or CFPB, specifically advises borrowers to understand amortization, the distinction between simple and precomputed interest, possible prepayment penalties, and what is included in a monthly auto payment.
The numbers here are examples, not personalized financial advice. Actual loan costs can vary based on lender pricing, credit profile, loan structure, state law, fees, taxes, vehicle price, trade-in value, down payment and optional products.
Where people go wrong
Shopping Only by Monthly Payment. A low payment can be created by stretching the loan across more months. Always compare term, APR, total interest and amount financed as well.
Ignoring the Amount Financed. Taxes, fees and optional products can increase the loan balance even when the vehicle's advertised price has not changed.
Assuming a Longer Term Is Cheaper. A longer term usually reduces the required payment but can substantially increase total interest.
Assuming All Auto Loans Calculate Interest the Same Way. Simple-interest and precomputed-interest structures can respond differently to extra payments and early payoff.
Making Extra Payments Without Checking Servicing Rules. Verify how the lender applies additional funds so the payment has the effect you intend.
Assuming Early Payoff Is Always Penalty-Free. Contract terms and applicable state law can affect whether a prepayment penalty or other restriction applies.
Financing Add-Ons Without Reviewing Their Full Cost. A small monthly increase can represent a significant total purchase when spread across a long term.
Comparing Different Loan Offers Using Different Terms. Compare similar amounts financed and similar loan lengths to understand whether one lender is actually offering better credit terms.
Questions people ask
The same financed balance is spread across more scheduled payments. That reduces the amount due each month, but because the balance remains outstanding longer, total interest can increase.
Fixed it?
Get one guide like this every Thursday.