Health Insurance Deductibles vs. Out-of-Pocket Maximums Explained
Confused by health insurance deductibles and out-of-pocket maximums? Learn how premiums, copays, and coinsurance affect your medical bills, what expenses count toward your limits, and how to budget for healthcare costs.
What you’ll need
Tap to tick things off before you start.
Deductible vs. Out-of-Pocket Maximum: Key Differences
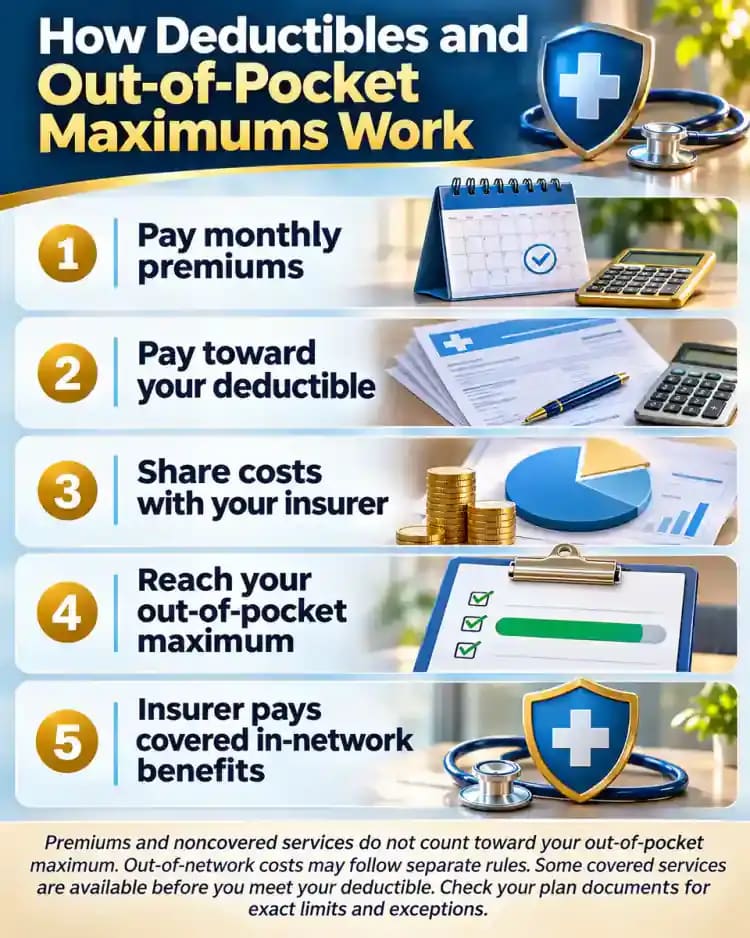
The difference between a deductible and an out-of-pocket maximum comes down to when each limit matters. Your deductible is the amount you generally pay for covered healthcare before your insurer begins sharing certain expenses. Your out-of-pocket maximum limits your eligible cost-sharing payments during a plan year. These thresholds work together: deductible payments usually count toward your maximum, but reaching your deductible does not mean all subsequent care becomes free. Your policy determines the specific amounts and coverage rules.
How Your Health Insurance Deductible Works
Your deductible accumulates as qualifying healthcare claims are processed during your coverage period. Suppose your annual deductible is $2,000 and you receive covered treatment with an insurer-negotiated allowed amount of $600. If the deductible applies and remains unmet, you generally owe $600, leaving $1,400 before reaching the threshold. The provider's original billed charge may be higher, but contracted rates typically determine your responsibility. Certain preventive services and other plan-specific benefits may be covered before the deductible is satisfied.
What Happens After You Meet Your Deductible?
After satisfying an applicable deductible, you commonly enter a cost-sharing arrangement with your insurer. A copayment is a fixed charge, such as $30 for an eligible office visit. Coinsurance is a percentage, such as 20% of a covered service's allowed amount. Your insurer pays its designated share while you remain responsible for yours. However, coverage categories may follow different rules. Some services use copayments immediately, while others have separate deductibles or cost-sharing requirements.
How the Out-of-Pocket Maximum Protects You
The out-of-pocket maximum establishes an annual ceiling on qualifying cost-sharing for covered in-network healthcare. Applicable deductible payments, copayments, and coinsurance generally contribute toward this threshold. Once you reach it, an Affordable Care Act-compliant insurer pays 100% of covered in-network essential health benefits for the remainder of the plan year. This protection is particularly valuable during serious illnesses or repeated treatment. The maximum does not eliminate every possible healthcare expense, so understanding its coverage boundaries remains important.
Which Healthcare Expenses Do Not Count?
Several healthcare expenses fall outside standard deductible and out-of-pocket calculations. Monthly insurance premiums never count toward either threshold. Services excluded from your policy generally do not qualify, even when medically necessary. Out-of-network treatment may follow separate accumulation rules or receive no credit toward your in-network maximum. Charges exceeding an insurer's allowed amount can also remain your responsibility when permitted. Federal surprise-billing protections create important exceptions for certain emergency and other qualifying services received outside your network.
Real-World Example: Calculating Your Medical Costs
Consider a hypothetical plan with a $2,000 deductible, 20% coinsurance, and a $5,000 out-of-pocket maximum. Assume no previous spending and one covered in-network procedure with a $10,000 allowed amount. You pay the first $2,000 toward your deductible. Of the remaining $8,000, your 20% share is $1,600. Your total responsibility is $3,600, while the insurer pays $6,400. You remain $1,400 below your annual maximum. Actual calculations depend on specific plan provisions.
Individual vs. Family Deductibles and Limits
Family insurance policies can organize deductibles differently. An embedded deductible allows individual family members to satisfy personal thresholds before the entire household reaches its combined deductible. An aggregate deductible generally requires qualifying family spending to reach a shared threshold before deductible-based benefits begin, subject to applicable exceptions. Family out-of-pocket maximums also track household spending. Under ACA rules, covered individuals cannot be required to exceed the applicable individual out-of-pocket limit, even when enrolled in family coverage.
High Deductible Health Plans and HSA Eligibility
The IRS establishes annual requirements for high deductible health plans, or HDHPs, that can support Health Savings Account eligibility. For 2024, qualifying plans generally required minimum deductibles of $1,600 for individuals and $3,200 for families. Maximum out-of-pocket amounts were $8,050 and $16,100, respectively. These are historical figures, not current thresholds. HDHP qualification alone does not guarantee HSA contribution eligibility. Other requirements apply, including restrictions involving disqualifying health coverage and Medicare enrollment.
How to Compare Health Insurance Plans
Comparing health insurance requires evaluating total potential spending rather than premiums alone. Multiply each monthly premium by 12, then estimate expected spending on covered services using the plan's cost-sharing rules. Consider anticipated prescriptions, specialist visits, and recurring treatment. Verify whether preferred providers participate in each network. For a high-cost scenario, add annual premiums to the applicable out-of-pocket maximum for covered in-network care. This comparison reveals financial exposure, although excluded expenses can increase actual costs.
Questions to Ask Before Choosing Your Coverage
Before enrolling, ask your insurer or benefits administrator to confirm deductible and out-of-pocket limits for your coverage level. Which services bypass the deductible? Are prescription and medical deductibles separate? How are out-of-network claims handled? Request details about referrals, prior authorization, and potential billing restrictions. Confirm provider participation directly with the insurer and medical office. Ask for the Summary of Benefits and Coverage and relevant policy documents so important answers can be checked against written terms.
How to Track Your Deductible Throughout the Year
Most insurers provide an online member portal showing how much of your annual deductible you have satisfied. Look for amounts applied, remaining balances, and individual versus family totals when applicable. Compare these figures with processed claims and benefit statements rather than relying solely on provider receipts. Claims can take time to appear, so recent treatment may not immediately affect your balance. Reviewing your account monthly helps identify missing transactions, duplicate entries, or unexpected adjustments before they become confusing.
Understanding Your Explanation of Benefits
An Explanation of Benefits, or EOB, explains how your insurer processed a healthcare claim. The billed charge is what the provider requested, while the allowed amount reflects the amount recognized under your coverage rules. The document identifies insurer payments, adjustments, and your calculated responsibility. An EOB is not a bill. The provider generally sends a separate statement requesting payment. Comparing both documents helps reveal whether contractual discounts were applied and whether the requested balance matches the processed claim.
How Preventive Care Affects Your Deductible
Under the Affordable Care Act, most non-grandfathered health plans must cover specified preventive services without patient cost-sharing when applicable requirements are satisfied. Eligible services may include certain vaccinations, screenings, and preventive counseling provided in-network. However, not every service performed during a wellness appointment qualifies. Diagnostic testing prompted by symptoms or treatment of an existing condition may generate separate charges. Coverage also depends on factors such as age, recommended screening intervals, and applicable clinical guidelines.
Prescription Drug Deductibles and Coverage Rules
Prescription coverage may have its own deductible or share one with medical services. Insurers commonly organize medications into formulary tiers, with preferred generic drugs generally costing less than specialty treatments. Some prescriptions use fixed copayments, while others require percentage-based coinsurance. Pharmacy choice also matters because preferred network pharmacies may offer lower negotiated prices. Certain medications require prior authorization or step therapy. Reviewing the formulary and pharmacy network helps explain differences between expected and actual prescription costs.
What Happens When Your Plan Year Resets?
Health insurance deductibles and out-of-pocket accumulators generally reset at the beginning of each new plan year. Some policies follow the calendar year, starting January 1, while others use a different twelve-month coverage period. Previously accumulated spending usually does not carry forward automatically. The date treatment occurs and the insurer's claim-processing rules can affect which period receives credit. Checking your plan's renewal date helps explain why an appointment near year-end may create different financial obligations.
Changing Health Insurance Plans Midyear
Switching health insurance during the year can affect accumulated spending. Deductible and out-of-pocket amounts credited under your previous policy generally do not transfer automatically to a different insurer or plan. Employer changes, qualifying life events, and Marketplace special enrollment periods may create opportunities to obtain new coverage. Some employer-sponsored arrangements provide transition credits, but these are not guaranteed. Comparing effective dates, coverage gaps, and accumulator transfer provisions helps clarify the financial consequences of switching policies.
ACA Protections Against Unlimited Medical Costs
The Affordable Care Act prohibits annual and lifetime dollar limits on essential health benefits in covered plans subject to these protections. Essential health benefits include broad categories such as hospitalization, emergency services, prescription drugs, and maternity care. This restriction concerns the total dollar value of qualifying benefits insurers can provide, not the annual amount patients contribute through cost-sharing. Coverage exclusions, medical necessity requirements, and network rules still apply. USA.gov provides information about obtaining Marketplace coverage.
How to Prepare Financially for Major Medical Care
Major procedures can generate expenses before, during, and after treatment. Request a written estimate from the hospital or healthcare provider, including expected professional, facility, anesthesia, and follow-up charges. Ask your insurer whether the procedure requires prior authorization and whether all participating providers are covered. Estimates are not guarantees because treatment needs can change. A dedicated healthcare reserve can help manage payment timing, while available payment plans may reduce immediate cash-flow pressure.
What to Do When Your Medical Bill Looks Wrong
Unexpected medical charges deserve verification before payment. Compare the provider's itemized statement with the corresponding Explanation of Benefits, checking service dates, billing codes, contractual adjustments, and patient responsibility. Contact the billing office about duplicate or unfamiliar charges. If the insurer processed a claim incorrectly, request reconsideration or follow its formal appeal procedure. Keep copies of documents, payment confirmations, and correspondence. Incorrect deductible credits may require a corrected claim or insurer adjustment.
Final Checklist for Managing Health Insurance Costs
Effective healthcare cost management depends on maintaining accurate information throughout your coverage period. Keep current insurance documents accessible, monitor accumulated spending, and retain important claim records. Check benefit details when services or coverage circumstances change. Review insurer notifications about revised terms, network participation, and annual limits. Organize medical receipts separately from premium payments so spending categories remain clear. Consistent recordkeeping makes it easier to recognize unexpected charges and understand your remaining financial obligations.
How Deductibles Affect Emergency Room Visits
Emergency room visits can involve substantial cost-sharing, particularly when your deductible remains unmet. A single visit may generate facility charges alongside physician and diagnostic fees. Depending on your plan, you might owe a deductible, emergency room copayment, or coinsurance. Federal No Surprises Act protections generally require qualifying out-of-network emergency services to receive in-network cost-sharing treatment and prohibit certain balance bills. These protections do not eliminate ordinary deductible obligations. Emergency coverage rules should never delay necessary medical treatment.
Hospital Stays and Multiple Medical Bills
A hospital stay often produces several separate claims even when treatment occurs during one admission. The hospital may bill for the room, equipment, and facility services, while physicians, anesthesiologists, radiologists, and laboratories submit additional charges. Each claim can have different allowed amounts and processing dates. This explains why bills may continue arriving after discharge. Reviewing the complete episode of care helps distinguish legitimate separate services from potentially duplicated charges and clarifies total patient responsibility.
Specialist Visits and Referral Requirements
Specialist appointments may carry higher copayments than primary care visits, depending on your insurance policy. Some health maintenance organization plans require referrals from primary care providers, while other arrangements allow direct specialist access. Certain procedures also require prior authorization before treatment. Missing an applicable referral or authorization can result in denied coverage or additional expenses, subject to plan terms and applicable protections. Confirming these requirements with your insurer before scheduling helps prevent avoidable administrative complications.
How Deductibles Apply to Diagnostic Tests
Blood tests, X-rays, MRI scans, and other diagnostic procedures may be subject to your deductible and coinsurance. Their costs depend on the service, testing facility, negotiated rate, and coverage rules. A screening performed as qualifying preventive care may receive different treatment from testing ordered to investigate symptoms. Additional facility or interpretation fees can also apply. Before scheduled testing, checking whether the laboratory or imaging center participates in your network can help clarify expected charges.
What Happens When You Have Two Health Insurance Plans?
Having two health insurance policies does not mean every medical expense will be fully reimbursed. Coordination of benefits rules determine which policy pays first and how the secondary insurer considers remaining eligible charges. Primary coverage is generally processed before secondary coverage, with ordering determined by applicable coordination rules. Each plan may maintain separate deductibles and coverage restrictions. Secondary payments can reduce patient responsibility, but combined benefits generally cannot exceed allowable expenses under the applicable coordination provisions.
Employer Contributions and Healthcare Spending
Employer-sponsored health insurance often includes financial contributions that reduce employees' direct coverage costs. Employers may pay part of the monthly premium or contribute money to an eligible Health Savings Account. These payments can improve household cash flow, but they do not automatically satisfy insurance deductibles. HSA funds may help pay qualifying medical expenses when those expenses arise. When reviewing workplace benefits, distinguishing employer contributions from actual insurance payments helps explain the economic value of the compensation package.
Using an HSA or FSA to Pay Medical Expenses
Health Savings Accounts and Flexible Spending Arrangements can help eligible consumers pay qualified medical expenses with tax advantages. HSAs generally require qualifying coverage and other eligibility conditions, while healthcare FSAs are commonly offered through employers. HSA balances generally remain available across years and employment changes. FSAs usually follow plan-year spending rules, although permitted carryovers or grace periods may apply. IRS Publication 969 explains qualifying expenses and account requirements. Account reimbursements do not independently change insurance cost-sharing calculations.
Why Your Deductible Balance May Change
Deductible balances sometimes change after an insurer revises previously processed claims. A provider might correct a billing code, withdraw a duplicate claim, or submit additional information that changes the allowed amount. Delayed claims can also appear after newer services have already been processed. These adjustments may increase or decrease credited deductible spending. Insurers generally maintain updated accumulation records reflecting finalized claim decisions. Comparing adjustment notices with earlier statements helps explain unexpected changes in your account.
How to Reduce Healthcare Costs Before Meeting Your Deductible
Consumers who have not met their deductibles may still benefit from insurer-negotiated prices and careful provider selection. Insurance company cost-estimator tools can help compare covered services across participating facilities. Generic medications may offer lower prices than brand-name alternatives when clinically appropriate. Independent imaging centers and outpatient facilities sometimes charge less than hospital-based locations. Comparing total allowed amounts rather than advertised prices provides a clearer picture of potential savings. Coverage and medical suitability remain important considerations.
Building a Healthcare Budget for the Next Plan Year
A forward-looking healthcare budget starts with expected insurance premiums and anticipated treatment needs. Estimate recurring appointments, prescriptions, and planned procedures using available coverage information. Then consider a higher-cost scenario involving substantial eligible medical spending. Dividing your intended annual savings target by twelve provides a monthly contribution goal, which can be adjusted for affordability. Keeping a separate healthcare reserve may reduce reliance on credit when bills arrive. Revisit the budget when coverage, income, or household circumstances change.
A $4,000 medical bill arrives, and your health insurance plan has a $2,000 deductible. Does that mean you owe $2,000, the entire bill, or something in between? The answer depends on your coverage, the insurer's negotiated rate, and how much you have already paid toward your annual limits.
Understanding the difference between a health insurance deductible and an out-of-pocket maximum can help you avoid expensive surprises. Your deductible is generally the amount you pay for covered services before your insurer begins sharing certain costs. Your out-of-pocket maximum is the most you pay for covered in-network care during a plan year through applicable deductibles, copayments, and coinsurance.
These two limits work together, but they serve different purposes. Meeting your deductible does not necessarily make subsequent medical care free. You may still owe a fixed copayment or a percentage of the cost until you reach your out-of-pocket maximum. Some services, including certain preventive care, may be covered before you meet your deductible.
Monthly insurance premiums are a separate expense. They do not count toward either limit. Noncovered services and many out-of-network expenses can also leave you responsible for costs beyond your standard maximum.
Before choosing a policy, compare more than the monthly premium. Review the deductible, out-of-pocket maximum, provider network, prescription coverage, and cost-sharing rules. A plan with a lower premium can become more expensive when you need substantial medical care.
This guide explains how these limits work, which payments count, and what to check before making healthcare decisions.
Where people go wrong
Assuming Insurance Pays Nothing Before the Deductible. Many plans cover certain services before you meet your deductible. These may include preventive care, selected prescriptions, or office visits with fixed copayments. Assuming every expense applies to the deductible can distort your budget and discourage necessary care.
Confusing the Deductible With the Out-of-Pocket Maximum. Meeting your deductible usually does not eliminate all medical costs. You may continue paying copayments or coinsurance until reaching your out-of-pocket maximum. Treating these limits as interchangeable can lead to seriously underestimated healthcare expenses.
Counting Monthly Premiums Toward Annual Limits. Your monthly premium keeps your insurance active, but it does not count toward your deductible or out-of-pocket maximum. When calculating your annual healthcare budget, include premiums separately from the potential cost-sharing expenses associated with receiving medical care.
Assuming Every Medical Bill Counts Toward the Maximum. Payments for services your policy does not cover generally do not count toward your out-of-pocket maximum. Out-of-network charges may follow separate rules or remain excluded. Check your benefits before assuming that every medical payment moves you closer to your annual limit.
Choosing a Plan Based Only on Monthly Premiums. A cheaper monthly premium does not guarantee lower annual healthcare spending. Plans with lower premiums may have higher deductibles or cost-sharing requirements. Compare total annual premiums, expected medical expenses, and worst-case covered in-network costs before selecting coverage.
Ignoring Individual and Family Deductible Rules. Family policies may include individual deductibles, family deductibles, or special rules governing when coverage begins paying for each person. Assuming everyone must meet the same threshold can cause confusion about medical bills and how quickly family cost-sharing limits are reached.
Using Outdated HDHP Limits for HSA Decisions. IRS deductible and out-of-pocket requirements for HSA-qualified high deductible health plans can change annually. The 2024 figures are historical examples, not permanent thresholds. Verify the applicable tax year's requirements and other HSA eligibility conditions before making contributions.
Questions people ask
A deductible is the amount you generally pay for covered healthcare before your insurer begins sharing certain costs. An out-of-pocket maximum is the annual limit on eligible cost-sharing expenses for covered in-network services. After reaching that maximum, your insurer pays 100% of covered in-network benefits for the remainder of the plan year.
Fixed it?
Get one guide like this every Thursday.