Fixed Annuities vs. Indexed Annuities: How Returns, Growth Limits, and Risks Compare
Fixed annuities offer predictable interest, while indexed annuities tie potential growth to market benchmarks. Learn how caps, participation rates, spreads, surrender charges, and insurer guarantees affect your retirement savings.
What you’ll need
Tap to tick things off before you start.
What Is an Annuity and How Does It Work?
An annuity is a contract with an insurance company designed to accumulate savings or provide retirement income. During the accumulation phase, money earns interest or investment-related returns according to contract terms. During the payout phase, the insurer may provide scheduled payments, potentially for life. Purchasing an annuity transfers certain financial risks to the insurer in exchange for contractual promises. As FINRA explains, the specific guarantees and payment arrangements depend on the annuity purchased and its provisions.
Fixed Annuities vs. Indexed Annuities: Key Differences
The central distinction between fixed annuities vs indexed annuities is how interest is determined. Traditional fixed annuities use insurer-declared interest rates, subject to contractual guarantees, making credited growth relatively predictable. Fixed indexed annuities calculate interest using the performance of a specified market benchmark, creating greater uncertainty about future earnings. Indexed contracts also introduce more complicated crediting rules. The practical trade-off is straightforward: greater predictability with traditional fixed rates versus potential market-linked growth with contractual limitations.
How Fixed Annuity Interest Rates Work
A traditional fixed annuity credits interest according to rates established by its insurance company. Some contracts guarantee an initial rate for several years, while others permit periodic rate adjustments. The contract also specifies a guaranteed minimum rate that establishes a floor for future credited interest. For example, a $50,000 deposit earning a guaranteed 4% annually would accumulate approximately $52,000 after one year, before applicable charges. Actual growth depends on compounding rules, rate guarantees, and contract provisions.
The Hidden Trade-Off: Inflation and Missed Market Gains
Predictable interest does not guarantee that retirement savings will maintain their purchasing power. If an annuity earns 3% annually while inflation averages 5%, its real purchasing power declines despite a rising account balance. Fixed interest also creates opportunity costs during periods of strong market performance because earnings do not automatically increase alongside stock prices. These limitations become particularly important over long retirement horizons, when inflation compounds and differences in investment growth can become substantial.
How Indexed Annuities Calculate Market-Linked Returns
Fixed indexed annuities use a specified benchmark, often a stock market index, to calculate credited interest. The insurance company measures index performance over a defined period, such as one year, and applies the contract's crediting formula. Consumers do not directly purchase shares of the benchmark's underlying investments. Instead, they receive contractual interest based partly on index performance. Investor.gov emphasizes that calculation methods vary, so identical index movements can produce different credited returns across annuity contracts.
Cap Rates: Why Strong Market Gains Can Produce Smaller Returns
A cap rate establishes the maximum interest an indexed annuity can credit under a particular calculation method and measurement period. Suppose the benchmark increases 15% over one year, but the contract imposes a 6% cap. Assuming no additional restrictions, the annuity credits only 6%, leaving the remaining nine percentage points uncredited. Caps limit participation in strong market rallies and may be adjustable under contract terms. Always distinguish the advertised cap from guaranteed future crediting limits.
Participation Rates and Spreads: Two More Growth Limits
A participation rate determines what portion of positive benchmark performance enters the interest calculation. With a 70% participation rate and a 10% index gain, credited interest would be 7% before other applicable limitations. A spread works differently by subtracting specified percentage points from the measured gain. For example, a 2% spread applied to a 10% gain produces 8% before other restrictions. Insurers may adjust certain rates or spreads at renewal, subject to contractual guarantees.
Downside Protection: Fixed Indexed Annuities vs. RILAs
Standard fixed indexed annuities generally provide a zero percent floor for index-linked interest, preventing negative benchmark performance from producing negative credited interest. This protection does not necessarily prevent account reductions caused by withdrawals or contractual charges. Registered index-linked annuities, commonly called RILAs, operate differently and can expose investors to market losses beyond specified buffers or thresholds. Investor.gov distinguishes these products because their downside protection varies significantly. Understanding the exact product classification is essential when evaluating potential losses.
Surrender Charges and Early Withdrawal Restrictions
Annuities commonly impose surrender charges when withdrawals exceed permitted amounts during an initial contract period, sometimes lasting five to ten years or longer. Charges often decline annually until the surrender period ends. Some contracts permit limited withdrawals without surrender charges, although conditions vary. Taxable distributions before age 59 1/2 may also trigger a 10% federal additional tax unless an exception applies. These restrictions make annuities generally unsuitable for emergency savings or money needed soon.
How to Choose an Annuity and Evaluate Insurer Guarantees
Evaluating an annuity requires matching its contractual features with retirement objectives, income needs, and acceptable uncertainty. Compare guaranteed benefits, projected outcomes, and official product disclosures rather than relying on promotional illustrations. Investigate the issuing insurer's financial strength through independent ratings and available regulatory information. FINRA notes that annuity guarantees depend on the insurer's claims-paying ability. These contracts are not FDIC-insured bank deposits. Independent professional guidance can help clarify complex provisions before a substantial financial commitment.
How Annuity Fees and Optional Riders Affect Your Returns
Annuity expenses vary by product and can affect how much money remains available for retirement. Optional income riders may provide additional withdrawal benefits but typically carry recurring charges. Some contracts also impose administrative or other benefit-related fees. For example, a 1% annual rider charge on a $100,000 calculation base could represent $1,000, depending on the contract. FINRA recommends understanding all expenses before purchasing because advertised growth figures may not reflect every applicable deduction.
Understanding Annuity Taxes and Early Distribution Penalties
Annuity earnings generally grow tax-deferred until distributed. Taxable earnings from nonqualified annuities are usually taxed as ordinary income, while distributions from traditional IRA annuities generally follow IRA taxation rules. Withdrawals before age 59 1/2 may trigger an additional 10% federal tax unless an exception applies. Purchasing an annuity inside an IRA does not create additional tax deferral. Tax treatment depends on funding sources, distribution methods, and individual circumstances, making current IRS guidance important.
How Annuity Payout Options Affect Retirement Income
Annuities can offer several payout arrangements when accumulated savings are converted into income. A life-only option generally provides payments for one person's lifetime, while joint-life arrangements can continue payments for two covered individuals. Period-certain options guarantee payments for a specified number of years. Annuitization typically converts account value into an income stream, limiting access to the original principal. Payment amounts depend on age, selected guarantees, contract terms, and the insurer's payout calculations.
What Happens to Your Annuity When You Die?
Annuity death benefits depend on the contract and whether payments have begun. During accumulation, a named beneficiary may receive the account value or another contractually defined benefit. After annuitization, payments to heirs depend on the selected payout option. Beneficiaries may face income taxes on inherited earnings, and distribution requirements can vary. Naming primary and contingent beneficiaries helps clarify intended recipients. Reviewing these designations after major family changes can prevent unintended outcomes.
Fixed vs. Indexed Annuities: Comparing Realistic Growth Scenarios
Consider two hypothetical $100,000 contracts over one year. A fixed annuity crediting 4% grows to $104,000. An indexed annuity with a 6% cap could reach $106,000 if its benchmark gains 15%, or remain at $100,000 if the benchmark is flat or declines. These simplified examples exclude fees and assume annual crediting without additional restrictions. Real contracts may produce different results, and a single favorable year cannot establish which product performs better over retirement.
How to Read an Annuity Illustration Without Being Misled
An annuity illustration may display guaranteed values alongside hypothetical outcomes based on assumed interest rates or index performance. These projections are not promises of future earnings. Look for the assumptions used, the period illustrated, and whether crediting terms remain constant throughout the example. Compare guaranteed minimum values with illustrated account balances and income benefits separately. Investor.gov encourages examining contract disclosures carefully because appealing projections may depend on conditions that never occur.
Replacing an Existing Annuity: Costs and Hidden Risks
Replacing an annuity can involve surrender charges, lost guarantees, new waiting periods, and additional contractual restrictions. An attractive new interest rate may not compensate for benefits surrendered under the original policy. A qualifying Section 1035 exchange can generally transfer a nonqualified annuity directly into another annuity without immediate federal income taxation, subject to applicable requirements. However, tax treatment does not eliminate contract costs. Compare existing and proposed benefits before considering any replacement transaction.
When an Annuity May Not Be the Right Retirement Investment
Annuities may be unsuitable when savings must remain readily accessible or an investor has a short financial horizon. Limited emergency reserves increase the risk of needing funds before contractual restrictions expire. Concentrating too much retirement wealth in one insurance contract can also reduce flexibility and create dependence on a single issuer. Consumers seeking maximum investment upside may find contractual growth limitations unattractive. Product suitability depends on financial objectives, available resources, and the broader retirement portfolio.
Alternatives to Fixed and Indexed Annuities
Certificates of deposit, Treasury securities, bond funds, and diversified investment portfolios offer alternative approaches to retirement savings. Eligible bank CDs carry FDIC insurance within applicable limits, while Treasury securities are backed by the federal government. Bond funds provide diversification but can lose market value. Stock and bond portfolios offer greater investment flexibility alongside market risk. Liquidity, taxation, guarantees, and potential returns differ substantially across these choices. The Consumer Financial Protection Bureau provides retirement planning resources for broader comparisons.
Your Final Annuity Decision Checklist
Before signing an annuity contract, confirm that you understand its guaranteed benefits, non-guaranteed projections, withdrawal provisions, and complete disclosures. Obtain written answers to unclear questions and independently verify important product claims. Check the issuer's identity and review relevant consumer information from FINRA, Investor.gov, and state insurance regulators. Keep copies of signed documents and promotional materials. A careful review should establish what the insurer promises, what remains uncertain, and which contractual obligations apply.
How Annuity Crediting Methods Change Your Earnings
Indexed annuities can produce different credited interest even when they track the same benchmark. Annual point-to-point methods compare index values at the beginning and end of a term. Monthly averaging uses multiple observations, potentially reducing the effect of sharp market movements. Monthly sum methods combine individual monthly percentage changes, often applying monthly limits. Investor.gov explains that crediting formulas materially influence returns. Understanding the selected method matters because identical market performance does not guarantee identical credited interest.
Why Stock Market Dividends Usually Do Not Count
Many indexed annuities reference price indexes that exclude dividends paid by underlying companies. A price index measures changes in stock prices, while a total return index also reflects reinvested dividends. Consequently, an annuity linked to a price index may capture less growth than investors expect from published stock market total returns. Some contracts use specialized indexes with different dividend treatments. FINRA emphasizes understanding the exact benchmark because index selection significantly influences illustrated and actual credited returns.
What Happens When Interest Rates Rise or Fall?
Changes in market interest rates influence how insurers price new annuities and support contractual guarantees. Rising bond yields may allow insurers to offer more attractive fixed rates or indexed crediting terms on newly issued contracts. Falling yields can have the opposite effect. Existing contracts remain subject to their stated guarantees, although adjustable rates may change at permitted renewal dates. These adjustments are not automatic reflections of Federal Reserve decisions. Insurer investment results and competitive conditions also matter.
Understanding Market Value Adjustments
Some fixed and indexed annuities include a market value adjustment provision that changes the amount available when funds are withdrawn during a specified period. The adjustment can be positive or negative, depending on interest rate movements and the contract's formula. It is separate from ordinary surrender charges, although both may apply to the same transaction. A negative adjustment can substantially reduce withdrawal proceeds. Contract disclosures explain the calculation, applicable circumstances, and any limitations on adjustments.
How State Insurance Guaranty Associations Work
State insurance guaranty associations provide limited protection for eligible policyholders when a licensed insurance company becomes insolvent. Coverage depends on state law, residency, contract eligibility, and applicable benefit limits. These associations are not federal agencies and do not provide the same protection as FDIC deposit insurance. Benefits may be subject to statutory caps and administrative procedures. Consumers can obtain information from their state insurance department and the relevant guaranty association rather than assuming every annuity receives identical protection.
Who Regulates Different Types of Annuities?
Traditional fixed annuities and standard fixed indexed annuities are primarily regulated as insurance products by state insurance departments. Registered index-linked annuities are securities and are also subject to federal securities regulation, including applicable SEC requirements. Professionals selling registered products generally face securities registration and licensing obligations. FINRA oversees member brokerage firms and their registered representatives. Regulatory treatment affects disclosures, sales practices, and oversight, making the product's legal classification important when determining which consumer protections apply.
How Annuity Sales Commissions Can Influence Recommendations
Insurance companies often compensate annuity sales professionals through commissions incorporated into product pricing. Compensation may vary according to contract type, premium amount, surrender period, and insurer incentives. These differences can create conflicts when one product pays more than another. A recommendation should be evaluated against documented consumer needs rather than sales compensation alone. FINRA encourages investors to understand financial professionals' incentives. Asking how a representative is compensated helps clarify potential conflicts without automatically establishing misconduct.
How to Verify an Annuity Agent or Financial Advisor
Consumers can verify insurance agents through state insurance department licensing databases, which may show license status and disciplinary actions. Professionals selling securities products can also be researched through FINRA BrokerCheck or the SEC's Investment Adviser Public Disclosure system, as applicable. Credentials should match the products and services being offered. Registration alone does not establish expertise or guarantee trustworthy recommendations. Reviewing qualifications, employment history, disciplinary disclosures, and potential conflicts provides a more complete assessment before engaging a professional.
Understanding Free-Look Periods and Your Right to Cancel
Many states require annuity contracts to include a free-look period during which purchasers can review the issued policy and cancel under specified conditions. The permitted window and refund calculation depend on state law and contract type. Some refunds equal the premium paid, while others may reflect investment performance or applicable rules. Cancellation generally requires following the insurer's documented procedures within the deadline. Keeping delivery records, written notices, and confirmation of receipt helps establish whether cancellation requirements were satisfied.
How to Monitor Your Annuity After Purchase
Annuity ownership requires ongoing monitoring rather than assuming contractual performance will remain unchanged. Periodic statements can reveal credited interest, account values, benefit balances, charges, and changes to applicable rates. Comparing these figures with contract provisions helps identify discrepancies. Beneficiary information should remain current after major life events. Insurer notices may also announce adjustments affecting future crediting periods. Reviewing contract performance alongside evolving retirement objectives helps determine whether the annuity continues serving its intended financial purpose.
Choosing between fixed annuities and indexed annuities can be confusing, especially when both are marketed as ways to protect retirement savings. The difference is not simply that one is safe and the other offers more growth. Each comes with contractual guarantees, limitations, costs, and restrictions that can significantly affect your retirement income.
A traditional fixed annuity credits interest according to rates specified by the insurance company, subject to a contractual minimum. Some contracts guarantee an initial rate for several years, while others allow the insurer to adjust rates periodically. This predictability can appeal to people who prioritize stability over market exposure.
A fixed indexed annuity works differently. Its credited interest depends partly on the performance of a market benchmark, such as the S&P 500. However, you do not directly own the stocks in that index. Your earnings are calculated using contract rules that may include caps, participation rates, and spreads. These restrictions can substantially reduce your return even when the market performs exceptionally well.
For example, an index could gain 15% while your annuity credits only 6% because of its cap. Although a standard fixed indexed annuity generally protects against negative index-linked interest, fees or withdrawals may still reduce your account value. Other products, including registered index-linked annuities, can expose you to investment losses.
Before committing retirement savings, you also need to understand surrender charges, withdrawal allowances, insurer financial strength, and potential tax consequences. This guide explains how both products work, where their guarantees end, and what to examine before signing a contract.
Where people go wrong
Assuming Indexed Annuities Deliver Full Stock Market Returns. An indexed annuity does not replicate direct ownership of a stock market index. Caps, participation rates, spreads, and index calculation methods can substantially reduce credited interest. Comparing advertised market performance with actual contract crediting rules prevents unrealistic growth expectations.
Confusing the Initial Fixed Rate With a Lifetime Guarantee. Some fixed annuities guarantee an attractive initial rate for only a limited period. Afterward, the insurer may reset the rate, subject to contractual minimums. Always examine renewal provisions instead of assuming the opening rate continues throughout retirement.
Believing Zero Percent Protection Means You Cannot Lose Money. A zero percent index crediting floor generally protects fixed indexed annuities from negative index-linked interest, not every possible reduction in account value. Withdrawals, surrender charges, and rider fees can still matter. Registered index-linked annuities may also expose investors to market losses.
Ignoring Surrender Charges Before Investing. Annuity surrender periods can last several years, with potentially substantial charges for accessing funds early. Consumers sometimes commit money they later need for medical bills, housing, or emergencies. Review withdrawal provisions and maintain sufficient liquid savings outside the contract.
Overlooking Changes to Caps and Participation Rates. An indexed annuity's initial cap or participation rate may not remain unchanged throughout the contract. Insurers can adjust certain crediting terms within contractual limits. Evaluate minimum guarantees and renewal rules rather than projecting current promotional rates indefinitely.
Treating Insurance Company Guarantees Like FDIC Insurance. Annuities are insurance contracts, not FDIC-insured bank deposits. Their contractual guarantees depend on the issuing insurer's financial condition. State guaranty associations may provide limited protection for eligible contracts, but coverage varies and should never substitute for evaluating insurer strength.
Comparing Headline Rates Without Calculating Net Benefits. A competitive advertised rate does not reveal every expense or restriction. Optional riders, spreads, surrender charges, and tax treatment may affect financial outcomes. Compare contract illustrations over the same time horizon, including realistic withdrawal assumptions and applicable charges.
Questions people ask
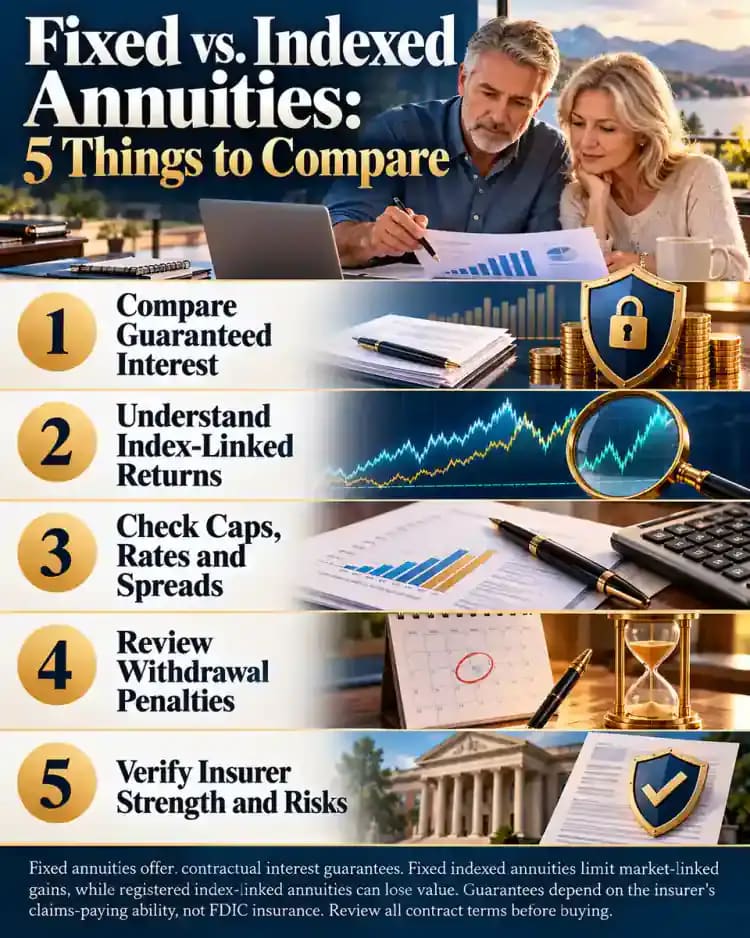
A traditional fixed annuity credits interest at rates established by the insurance company, subject to contractual guarantees. A fixed indexed annuity calculates interest partly from a market benchmark's performance. Indexed returns can vary and are often restricted by caps, participation rates, or spreads. Neither product provides direct stock ownership.
Fixed it?
Get one guide like this every Thursday.