The 4 Percent Rule: A Smarter Retirement Plan
Is the 4 percent rule enough for retirement? Learn how withdrawals, market downturns, inflation, taxes, and required minimum distributions affect your savings, plus practical ways to build a more flexible retirement income plan.
What you’ll need
Tap to tick things off before you start.
Understand What the 4 Percent Rule Actually Says
The 4 percent rule is a historical retirement withdrawal guideline, not a promise that your money will last forever.
Under its traditional interpretation, you withdraw 4% of your initial retirement portfolio during the first year. In subsequent years, you adjust that initial dollar amount for inflation rather than withdrawing 4% of the current balance.
The distinction matters. A fixed initial withdrawal adjusted for inflation can become a much larger percentage of your remaining investments after a market decline.
The guideline is most closely associated with approximately 30-year retirement periods and historically tested stock-and-bond portfolios. It does not automatically account for taxes, investment fees, personal circumstances, or unusual market conditions.
Calculate Your First-Year Withdrawal
Start with a hypothetical retirement portfolio worth $750,000.
Using the traditional calculation:
$750,000 x 0.04 = $30,000
The resulting first-year withdrawal is $30,000, equivalent to $2,500 per month before any applicable taxes.
For perspective, a $500,000 portfolio produces an initial withdrawal of $20,000, while a $1 million portfolio produces $40,000.
These figures represent withdrawals from savings, not necessarily total retirement income. Social Security, pensions, and other sources may supplement them.
Do not confuse a gross withdrawal with spendable income. If some distributions are taxable, the amount available for household expenses may be lower.
Learn Why Historical Research Matters
The guideline became popular through historical research examining how stock-and-bond portfolios performed across different retirement starting dates.
Research associated with William Bengen and later retirement withdrawal studies explored the sustainability of inflation-adjusted spending over approximately three decades.
The essential question was whether a portfolio could support withdrawals through difficult historical periods, not merely during average market conditions.
However, historical testing has limitations. Future returns, inflation, bond yields, fees, and taxes may differ from previous experience.
A strategy that survived particular historical periods is not guaranteed to survive every possible future environment.
Separate the Guideline From a Guarantee
The biggest mistake is interpreting historical portfolio survival as certainty.
A 4% initial withdrawal does not guarantee that savings will last 30 years, nor does it establish the correct withdrawal amount for every retiree.
Portfolio performance depends on market returns, inflation, investment costs, spending behavior, and retirement length.
Personal circumstances matter equally. Someone with a substantial pension may tolerate different investment risks than someone relying almost entirely on savings.
Use the guideline as a preliminary benchmark. Evaluate whether its assumptions match the actual financial obligations your portfolio must support.
Match the Plan to Your Retirement Timeline
A person retiring at 55 could potentially need savings for 40 years or longer. Someone retiring at 70 may have a different expected planning horizon.
The longer a portfolio must support withdrawals, the more exposure it has to inflation, market cycles, and unexpected expenses.
Life expectancy is also uncertain. Planning exclusively around an average lifespan can underestimate longevity risk.
Model several retirement lengths rather than choosing one precise endpoint. Consider how annual spending would affect savings across 25, 30, 35, and 40 years.
Longer retirement periods do not automatically make the 4 percent rule unsuitable, but they demand closer scrutiny.
Expect Spending to Change With Age
Retirement expenses seldom remain perfectly consistent.
Early retirement may involve extensive travel, hobbies, and activities. Some households subsequently reduce discretionary purchases. Later retirement can bring additional healthcare, transportation, or caregiving costs.
These patterns are possibilities rather than universal stages. Housing repairs, family responsibilities, and medical conditions may create substantial expenses at any age.
Divide projected expenses into categories such as housing, food, insurance, healthcare, transportation, travel, and emergencies.
Then distinguish essential spending from flexible spending. This separation becomes especially useful when markets perform poorly and temporary budget adjustments are necessary.
Examine Your Investment Allocation
Historical withdrawal research commonly evaluated diversified portfolios containing stocks and bonds.
Stocks offer long-term growth potential but introduce market volatility. Bonds may provide income and diversification, although they also carry interest-rate and credit risks.
Cash can help meet immediate spending needs, but excessive cash holdings may lose purchasing power when inflation exceeds returns.
Your allocation affects both expected growth and the severity of possible losses.
A portfolio's historical withdrawal success rate cannot simply be transferred to a significantly different portfolio. Review the mix of investments behind any sustainability estimate.
Recognize the Risks of Extreme Allocations
Holding nearly everything in cash can reduce short-term market volatility while increasing the possibility that purchasing power declines over decades.
An entirely stock-based portfolio may offer more growth potential but can experience severe losses at precisely the wrong time.
Neither extreme automatically provides an ideal retirement solution.
Investment diversification seeks to balance competing risks, although it cannot eliminate losses.
Consider the interaction between investment allocation, retirement length, essential spending, and available income outside the portfolio. The appropriate balance depends on those factors rather than an arbitrary percentage.
Understand Sequence of Returns Risk
Sequence of returns risk describes how the order of investment gains and losses influences retirement outcomes when money is being withdrawn.
Two portfolios can experience the same average investment return but finish with different balances because their returns occur in different sequences.
Poor performance early in retirement is particularly dangerous. Withdrawals remove money while investments are depressed, potentially reducing the assets available for later recovery.
When no withdrawals occur, rearranging identical periodic returns does not change the ending value. Once withdrawals enter the calculation, their timing becomes crucial.
This explains why average annual returns alone provide an incomplete retirement forecast.
See Why an Early Market Crash Hurts
Imagine retiring with $800,000 and withdrawing $32,000 during the first year.
If your portfolio then suffers a hypothetical 25% investment loss on the remaining $768,000, its value falls to approximately $576,000 before other adjustments.
Your original $32,000 withdrawal now represents about 5.6% of that smaller balance, even before increasing withdrawals for inflation.
This simplified example excludes taxes, fees, and intrayear market movements. Actual outcomes depend on precisely when withdrawals and investment returns occur.
The lesson is straightforward: a withdrawal amount that initially appears modest can become considerably more demanding after investment losses.
Understand the Cost of Selling Investments Low
Suppose you need $10,000 from an investment priced at $100 per share. You would sell 100 shares.
If its price falls to $50, raising the same $10,000 requires selling 200 shares.
Selling additional shares after a decline reduces the number available to participate in a potential recovery.
This does not mean every sale during a downturn is a mistake. Retirement portfolios exist partly to fund spending, and withdrawals may be unavoidable.
It does mean that predetermined spending flexibility and diversified sources of liquidity can help manage the consequences of unfavorable markets.
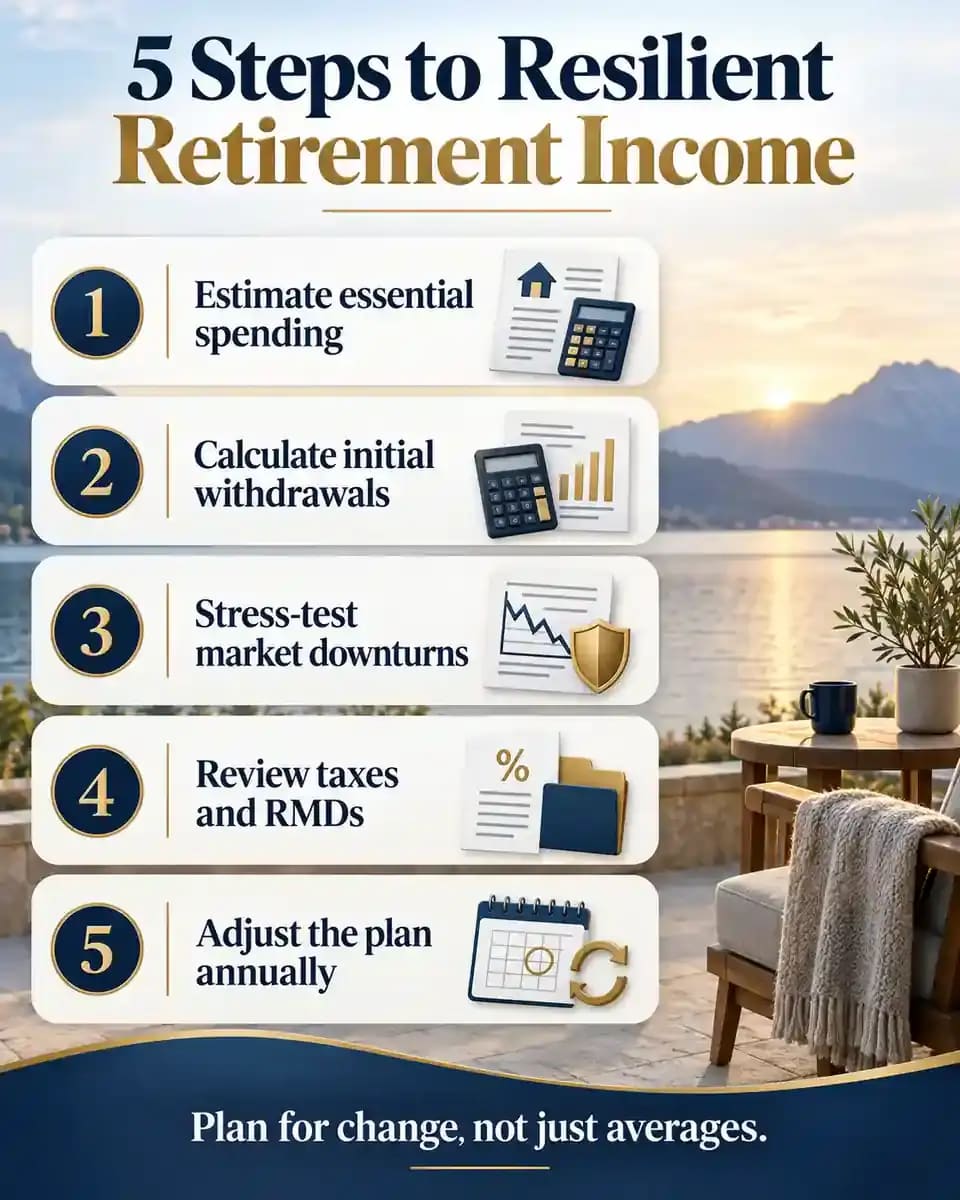
Stress-Test Several Market Environments
Do not evaluate retirement readiness using only an assumed average return.
Consider scenarios involving a strong first decade, a severe early downturn, prolonged weak returns, and a period of unusually high inflation.
Compare their potential effects on investment balances and annual withdrawals.
Also test what happens when unfavorable conditions overlap. Falling stock prices combined with expensive living costs can create greater pressure than either problem alone.
Forecasts are estimates, not predictions. Their purpose is to reveal vulnerabilities and help identify spending decisions that could improve resilience.
Calculate How Inflation Changes Withdrawals
The traditional 4 percent rule increases the original withdrawal amount with inflation.
Suppose the first-year withdrawal is $40,000 and inflation is 3% during the following year.
The second-year withdrawal becomes $41,200. If inflation remains 3% for another year, the third-year withdrawal becomes $42,436.
Those increases aim to preserve purchasing power, not to reflect portfolio performance.
Persistent inflation raises nominal spending requirements while investment balances may fluctuate independently.
Because inflation varies, model several rates instead of assuming that living costs will always increase by the same percentage.
Calculate Retirement Income After Taxes
A retirement withdrawal is not necessarily equivalent to spendable income.
For example, withdrawing $40,000 from a fully taxable traditional IRA creates different tax consequences than receiving a qualified $40,000 Roth IRA distribution.
Traditional IRA withdrawals are generally included in ordinary income, except for amounts attributable to nondeductible contributions or other applicable exclusions.
Federal taxes, possible state taxes, and interactions with other income can affect the final amount available.
Estimate both gross withdrawals and net spending needs. Otherwise, a retirement budget may appear balanced while overlooking a substantial recurring expense.
Compare Traditional and Roth Retirement Accounts
Different account types have different tax rules.
Traditional IRAs and traditional 401(k)s commonly contain pretax savings, with taxable withdrawals generally treated as ordinary income.
Roth accounts generally use after-tax contributions. Qualified Roth distributions may be received federal income tax-free when applicable requirements are satisfied.
Traditional IRA distributions can also involve previously taxed basis, while nonqualified Roth withdrawals require closer examination.
SEP and SIMPLE IRAs have additional provisions that can matter for business owners and self-employed workers.
The IRS IRA distribution guidance explains important differences and exceptions. Account labels alone should not determine withdrawal decisions.
Know the Age 59 1/2 Withdrawal Rules
Withdrawals from IRAs before age 59 1/2 may trigger an additional 10% federal tax on the taxable portion unless an exception applies.
This additional tax can apply on top of ordinary income taxes.
Exceptions exist for certain qualifying situations, but they involve specific eligibility requirements. Roth contribution withdrawal rules also differ from the rules governing Roth earnings.
SIMPLE IRA withdrawals during the first two years of participation may face a different, higher additional tax.
The IRS guidance on early IRA distributions provides further details.
Early retirement planning should therefore distinguish accessible funds from money that could trigger additional taxes.
Build a Strategy for Early Retirement Access
Retiring before age 59 1/2 requires more than calculating an annual portfolio withdrawal.
You also need to understand which assets are accessible, which distributions are taxable, and when additional withdrawal taxes might apply.
Taxable investment accounts, cash savings, eligible Roth IRA contributions, and certain qualifying retirement-plan distributions can have different accessibility rules.
Some special exceptions require strict conditions and may not apply equally to IRAs and employer plans.
Map expected expenses against available resources for the years before ordinary retirement account access becomes simpler. Have a professional verify any complex distribution strategy.
Understand Tax Bracket Management
Retirees sometimes manage taxable income by coordinating withdrawals from different account categories.
For example, taxable investments, traditional retirement accounts, and Roth accounts may produce different federal tax outcomes.
Taking distributions in a particular sequence can affect marginal tax rates, taxable Social Security benefits, Medicare-related costs, and future retirement account balances.
However, withdrawing everything from one account simply because its current tax treatment appears favorable can create problems later.
The objective is not necessarily to pay the smallest tax bill in one isolated year. A more useful framework considers potential taxes across the entire retirement period.
Learn What Required Minimum Distributions Mean
Required minimum distributions, commonly called RMDs, are mandatory withdrawals from certain retirement accounts after reaching the applicable starting age.
They generally apply to traditional IRAs and many tax-deferred employer retirement accounts.
Their purpose is to prevent indefinite tax deferral.
The obligation depends on account type and individual circumstances. For example, Roth IRAs do not require lifetime RMDs for their original owners, and designated Roth employer accounts generally have no lifetime RMD requirement beginning in 2024.
The Investor.gov RMD resource provides additional background on mandatory retirement withdrawals.
Identify Your Applicable RMD Starting Age
The SECURE Act 2.0 changed the starting age for many retirement account holders.
Under the current framework, people born from 1951 through 1959 generally begin RMDs at age 73, while those born in 1960 or later generally begin at age 75.
Older birth cohorts may fall under earlier rules.
For traditional IRA owners, the first RMD is generally due by April 1 of the calendar year following the year they reach their applicable RMD age. Subsequent annual RMDs are generally due by December 31.
Certain employer plans may allow eligible participants who are still working to delay distributions. Confirm the rules applicable to each account.
Understand the Penalties for Missing an RMD
Failing to withdraw the required amount can trigger a substantial federal excise tax.
Under current IRS rules, the tax is generally 25% of the shortfall. It can be reduced to 10% when a qualifying correction is completed within the applicable correction window.
The IRS may waive the tax when a shortfall resulted from reasonable error and appropriate corrective action is taken.
These are not automatic reductions or waivers.
Keep reliable records, verify RMD calculations, and monitor distribution deadlines. If a shortfall occurs, promptly review the applicable correction procedures with a qualified tax professional.
Calculate a Hypothetical RMD
An RMD is generally calculated using the previous December 31 account balance divided by an applicable IRS life expectancy factor.
Suppose an IRA had a prior year-end balance of $600,000 and the applicable factor were 26.5.
$600,000 / 26.5 = approximately $22,642
The factor of 26.5 appears in the IRS Uniform Lifetime Table for age 73, although a different table may apply depending on beneficiary circumstances.
This calculation is illustrative. Actual RMDs require the correct age, account balance, beneficiary information, and applicable IRS table.
IRA owners with multiple accounts should also understand which RMDs may be aggregated and which must be satisfied separately.
Understand How RMDs Interact With the 4 Percent Rule
RMD obligations and voluntary retirement spending plans operate under different rules.
The traditional 4 percent strategy calculates withdrawals from an initial portfolio value and adjusts them for inflation. RMDs use applicable account balances and IRS distribution factors.
Consequently, an RMD can exceed the amount someone planned to withdraw for living expenses.
However, mandatory distribution does not necessarily mean mandatory spending. Money remaining after applicable taxes may generally be saved or invested in a taxable account.
An RMD cannot ordinarily be rolled over to another tax-deferred retirement account.
Separate the legal requirement to distribute funds from the personal decision about how much to spend.
Consider Flexible Withdrawal Guardrails
A flexible withdrawal strategy allows spending to respond to changing portfolio conditions.
One approach establishes upper and lower withdrawal-rate thresholds, sometimes called guardrails.
When the current withdrawal rate rises beyond a specified threshold because the portfolio has fallen, discretionary spending may be reduced. When investments perform exceptionally well, spending may increase within predetermined limits.
Guardrails require careful design. Their thresholds, adjustment sizes, and review frequency affect outcomes.
They do not guarantee retirement success and may require uncomfortable spending reductions during prolonged market weakness.
The practical advantage is having decisions planned before stressful market events occur.
Maintain a Practical Liquidity Plan
Holding some accessible funds can reduce the need to sell volatile investments to cover immediate expenses.
A liquidity plan might combine checking balances, cash reserves, and relatively stable short-term investments.
Each option involves trade-offs. Cash loses purchasing power during inflation, while short-term investments can carry interest-rate, credit, or liquidity risks.
No universal cash reserve size suits every retiree.
Consider how predictable your income is, how much spending is essential, and how easily portfolio holdings can be sold.
Liquidity provides flexibility, but it should complement a long-term investment strategy rather than replace one.
Review Your Retirement Plan Annually
Retirement planning should continue after your final working day.
An annual review can compare actual spending against projected expenses, check portfolio allocation, examine investment costs, and update assumptions about inflation and longevity.
It should also account for changes in household income, tax rules, healthcare needs, and required distribution obligations.
Large market movements or major life events may justify additional reviews.
Avoid confusing regular oversight with constant trading. Frequent portfolio changes can introduce costs and emotional decisions.
The objective is to maintain a coherent income strategy while making thoughtful adjustments when circumstances change.
Coordinate Social Security With Portfolio Withdrawals
Portfolio savings are only one component of retirement income for many Americans.
Social Security benefits can provide recurring income that reduces the amount required from investments.
Claiming age affects monthly benefits, and decisions may have important consequences for spouses, survivors, taxes, and lifetime income.
Delaying benefits may increase monthly payments within applicable rules, but it can also require funding additional years from other resources.
There is no universally optimal claiming age.
Evaluate Social Security alongside pensions, employment income, healthcare expenses, and portfolio withdrawals rather than treating each decision independently.
Plan for Healthcare and Unexpected Expenses
A retirement budget should provide room for costs that do not follow a predictable monthly pattern.
Healthcare premiums, prescriptions, dental treatment, home maintenance, and family emergencies can create sudden financial demands.
Long-term care expenses may be especially significant, although needs vary considerably.
Distinguish recurring healthcare costs from possible large one-time expenses. Examine relevant insurance coverage, exclusions, deductibles, and out-of-pocket responsibilities.
Avoid assuming that every unexpected expense can be funded by increasing retirement withdrawals without affecting long-term sustainability.
A resilient strategy recognizes uncertainty and maintains some capacity to respond.
Use Professional Guidance for Complex Decisions
A qualified financial planner can help evaluate withdrawal sustainability, asset allocation, retirement timing, and spending flexibility.
A tax professional can help examine distribution rules, taxable income, RMD obligations, and potentially costly account decisions.
Ask how advice is compensated, whether the professional acts as a fiduciary in the engagement, and what services are included.
Useful questions include how a proposed plan behaves during prolonged downturns, which assumptions drive the results, and what circumstances would trigger a change.
Request clear explanations rather than relying on projected returns alone.
Professional analysis cannot eliminate financial risk, but it can help identify overlooked interactions between investment decisions and tax requirements.
Create Your Personal Retirement Review Checklist
A useful retirement withdrawal plan should answer several questions before money leaves an investment account.
How much income is required for essential expenses? Which income sources are predictable? How would an early market decline affect withdrawals? What spending can change without undermining basic needs?
Also examine which accounts are taxable, whether early distribution rules apply, and when mandatory withdrawals begin.
Document the assumptions behind your plan and establish a schedule for reviewing them.
The 4 percent rule can remain a useful reference, but retirement resilience comes from understanding its limitations and responding intelligently when financial conditions change.
The 4 percent rule is one of the best-known retirement planning guidelines. It offers an appealingly simple idea: withdraw a manageable amount from your savings each year and give your investments a reasonable chance of lasting throughout retirement.
But retirement is rarely simple. Markets decline, inflation increases living expenses, tax rules affect withdrawals, and unexpected costs can disrupt even carefully constructed budgets.
A retirement strategy that looks sustainable on paper may become uncomfortable when several of these problems occur simultaneously.
This guide explains the 4 percent rule, how its original assumptions work, and where it can fall short. You will learn how sequence of returns risk, investment allocation, taxes, and required minimum distributions influence retirement income. You will also discover practical approaches to making withdrawals more adaptable.
Important: This article provides general financial education, not individualized investment, financial, legal, or tax advice. Examples are hypothetical, and investment outcomes are never guaranteed.
Where people go wrong
Withdrawing 4% of the Current Balance and Calling It the Original Rule. The traditional guideline begins with 4% of the initial portfolio and adjusts that dollar amount for inflation. Taking 4% of the remaining balance annually is a different variable-withdrawal strategy with different spending outcomes.
Assuming Historical Success Guarantees Future Results. Past market studies cannot predict future returns, inflation, taxes, or retirement longevity. Historical sustainability should be treated as evidence, not certainty.
Ignoring Sequence of Returns Risk. Major early losses combined with ongoing withdrawals can significantly weaken long-term portfolio sustainability. Average returns alone conceal this risk.
Treating Gross Withdrawals as Spendable Income. Traditional retirement account distributions may generate income taxes. Budgeting without considering tax treatment can overstate available retirement spending.
Using an Inappropriate Investment Allocation. A portfolio dominated by cash may struggle against inflation, while an excessively aggressive allocation can create uncomfortable losses during withdrawal years.
Overlooking Early Withdrawal Rules. Retirement account distributions before age 59 1/2 may trigger additional federal taxes unless specific exceptions apply. Early retirees should understand account accessibility.
Missing RMD Deadlines. Required minimum distribution shortfalls can create substantial excise taxes. Calculations, account-specific requirements, and deadlines should be verified annually.
Assuming Mandatory Withdrawals Must Be Spent. An RMD requires a qualifying distribution, not necessarily consumption of the entire amount. Funds remaining after applicable taxes can generally be saved or reinvested outside the retirement account.
Never Updating the Retirement Plan. A withdrawal strategy established at retirement may become unsuitable as spending, investments, health, household circumstances, and tax regulations change.
Questions people ask
The 4 percent rule is a withdrawal guideline that begins with 4% of the initial retirement portfolio during the first year and adjusts that dollar amount for inflation in subsequent years. It was developed from historical portfolio research involving approximately 30-year retirement periods. It is not a guarantee.
Fixed it?
Get one guide like this every Thursday.